
Blue Moon, The Elmet Group, and EQ Resources Announce a US$150-$175 Million Investment into the Springer Tungsten Complex, Nevada, to Strengthen the U.S. Tungsten Supply Chain
Source: PR Newswire
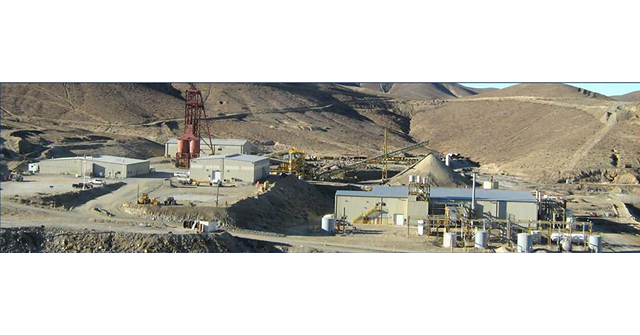
Blue Moon Metals, Elmet Group and EQ Resources signed a binding agreement for a U.S. tungsten supply-chain buildout centered on Nevada's Springer complex, supported by approximately US$150 million from Elmet and a further US$25 million standby commitment. Elmet will provide Blue Moon a US$50 million tungsten prepayment facility, invest US$25 million in Blue Moon equity at a 31.8% premium, and inject US$75 million into a 70%-owned APT-processing joint venture. The planned APT plant targets 4,000 tonnes per year of capacity, while Springer mine and mill production is targeted for Q4 2027 and APT restart for 2H 2028; closing remains subject to diligence, definitive agreements and regulatory approvals.
Analysis
MOON’s equity re-rating hinges less on tungsten pricing than on converting a historically documented asset into financeable, independently verified reserves and completing definitive agreements. The premium equity raise reduces near-term funding uncertainty, but the concentrate prepayment effectively encumbers 25% of sales cash flow; that can materially constrain mine-level free cash flow during ramp-up. The key 1-3 month catalyst is closing plus the first funding tranche, while the more consequential 6-18 month risk is whether drilling, metallurgical work and construction milestones validate a 2027 restart rather than create another capital call.
ELMT gains strategic vertical integration and potential preferential access to a scarce defense input, but the market should discount the economic benefit until contract pricing, APT conversion margins and government-investment terms are disclosed. Its principal risk is execution concentration: it is assuming operatorship of a restarted processing facility while upstream feed is initially dependent on a single unverified mine. EQ Resources (EQR.AX) is the cleaner operating beneficiary because its contracted feed optionality can monetize existing production even if Springer ramps slowly; it also has upside if its ore-sorting process is adopted, though this remains test-work rather than a proven commercial outcome.
The consensus may overvalue the domestic-supply narrative relative to timing. APT capacity is not equivalent to profitable output: ramp delays, recovery shortfalls, power/reagent costs, and tungsten-price weakness can erase processing margins, while Blue Moon’s minimum delivery obligations introduce asymmetric downside if mine commissioning slips. Conversely, a successful domestic qualification by defense/aerospace customers could support long-duration price premia beyond spot tungsten, an upside not likely reflected until customer contracts emerge.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- MOON: treat as a 45-day closing catalyst trade only after confirming TSXV approval, definitive agreements and receipt of the first US$25m tranche. Accumulate modestly on completion; target a 20-30% re-rating versus a 10-15% stop if financing closes but resource/drilling disclosure is delayed or raises technical uncertainty.
- ELMT: maintain/establish a small long for 6-12 months only if management discloses project-level return hurdles, APT pricing mechanics and government capital terms. Upside comes from strategic multiple expansion; exit if the investment is largely non-recourse economically or requires material incremental corporate funding.
- Long EQR.AX / short MOON as a 6-12 month execution pair: EQR has diversified operating feed and contractual processing optionality, while MOON carries reserve-verification, construction and delivery-obligation risk. Close the pair if Springer publishes a compliant resource and fully funded construction plan with credible commissioning evidence.
- Set alerts for a compliant NI 43-101 resource, ore-sorting recovery data, final capex budget, and any revision to the Q4-2027/2H-2028 schedule. Do not underwrite full project value before these disclosures; each is a binary valuation inflection point.
More News
- Analysis-US rail fuel surcharges on grain hit record highs, squeezing farmers in harvest season
- Department of War Makes Landmark $450 Million Committed Investment in The Elmet Group to Secure America’s Tungsten Supply Chain
- S&P Dow Jones Indices loosens Canadian index inclusion criteria
- Strait of Hormuz talks postponed due to Yemen events, says Iran
- Satellite images show extent of damage to Saudi Arabia’s oil pipeline that bypasses Strait of Hormuz
- Yemen’s Houthis seize more islands in southern Red Sea