
BMO Named Official Bank of the Los Angeles Lakers
Source: PR Newswire
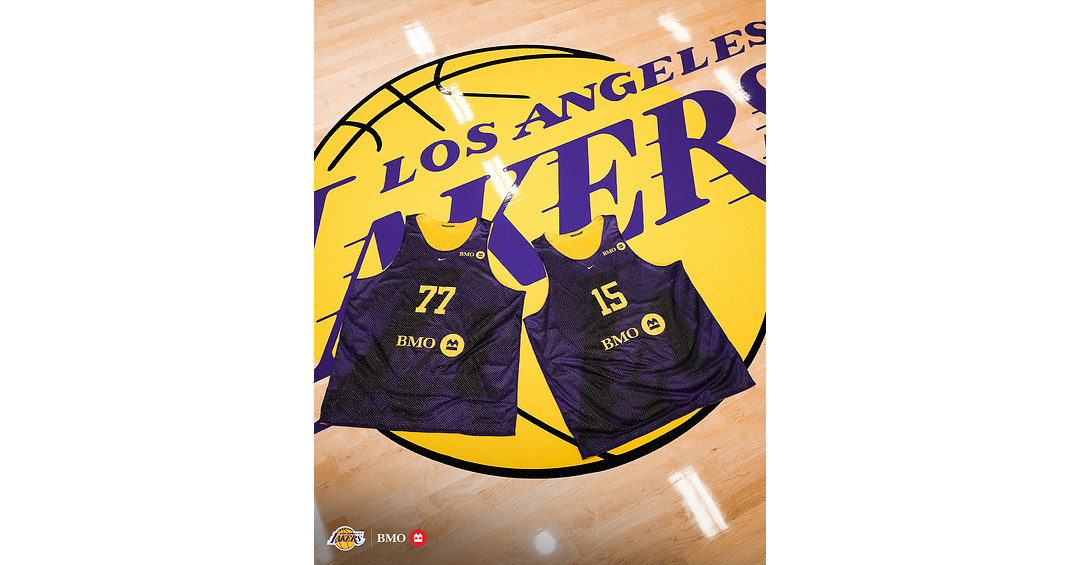
BMO signed a long-term partnership to become the Los Angeles Lakers’ exclusive Official Bank, beginning with the 2026-27 NBA season. The deal includes BMO branding on training camp materials and newly designed practice jerseys, naming rights for “BMO Courtside Reserve” premium floor seats, and a “League of Stars” legends program Presented by BMO. BMO also plans financial empowerment and small-business spotlight initiatives across Southern California, with no stated financial terms.
Analysis
This reads more like a distribution-and-relevance spend than an earnings event. For BMO, the only way this matters is if the partnership converts into cheaper core deposits, SMB relationships, or wealth referrals in Southern California; otherwise it is just SG&A with brand lift that is hard to underwrite. The market should treat any initial enthusiasm as a sentiment trade, not a fundamentals re-rate.
The competitive angle is more interesting than the press release suggests. BMO is signaling a willingness to buy local relevance in a market where JPM, WFC, BAC, and USB already have deeper operating density; that tells me the real battleground is affluent retail and small-business wallet share, not sports marketing. If BMO can stitch this into banker-led acquisition and community lending, the second-order effect is modest deposit beta improvement and better cross-sell, but the edge is likely measured in basis points, not a step-change.
The main risk is overinterpretation: sponsorship exposure rarely shows up in revenue before 2-4 quarters, and it can just as easily be offset by NIM pressure or a slower U.S. growth backdrop. The thesis would be falsified if BMO’s next U.S. deposit and fee-income prints do not improve, or if expenses rise without evidence of client acquisition. TISI has no obvious read-through here.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in BMO: treat this as a brand-investment headline with minimal near-term EPS impact; wait for the next quarterly U.S. deposit and fee-income data before underwriting any rerate.
- Watch BMO over the next 1-2 quarters for Southern California deposit growth, SMB loan production, and wealth cross-sell; only become constructive if those metrics inflect, otherwise the partnership is just expense.
- Relative-value idea: if BMO outperforms on U.S. growth metrics, consider long BMO / short a U.S. regional bank proxy (KRE) over 3-6 months; the upside is modest multiple support, but the trade needs operating proof.
- Avoid buying short-dated calls on this news alone; implied upside from brand activation is too uncertain, and the risk/reward is poor unless the next print confirms measurable client acquisition.
More News
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Brian Sullivan: Why the 'real' price of oil is likely $30-$40 higher than where it is now
- Penske Automotive agrees to be taken private by Penske, Mitsui
- Supermicro promised a new CFO in December 2024. A $2.5 billion smuggling case and a co-founder’s arrest later, it has one
- Blackstone President Jon Gray Bets Big on AI Boom
- What's behind the sell-off in AI neocloud stocks like CoreWeave and Nebius