
SANY Heavy Truck Debuts Production-Ready Electric Truck Portfolio at IAA Transportation 2026
Source: PR Newswire
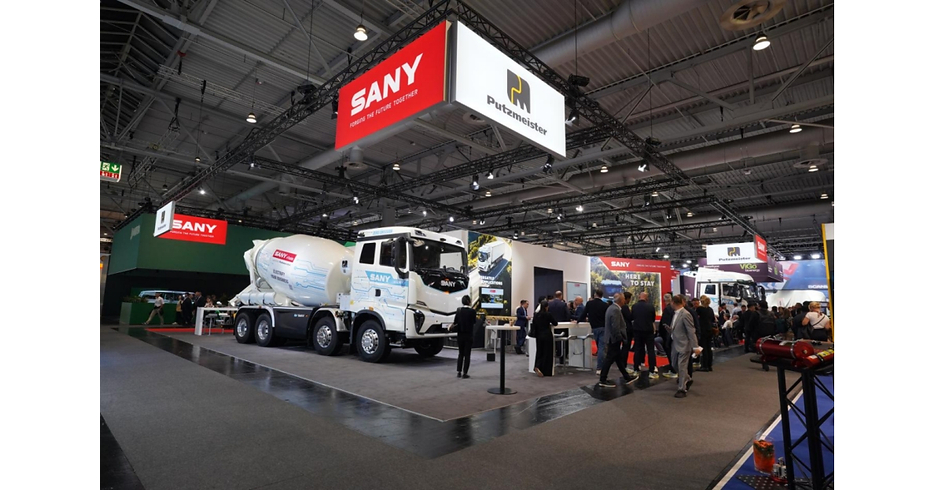
SANY debuted its production-ready SE636 battery-electric heavy-duty truck at IAA Transportation 2026, featuring a 636 kWh battery, up to 500 km of stated range and EU Whole Vehicle Type Approval. The company said more than 70,000 electric heavy-duty trucks are operating globally, while its European fleet has logged over 20 million km across 15 markets since 2022. SANY is supporting its European expansion through roughly 650 service workshops and 24/7 roadside assistance, signaling a sustained push into commercial-vehicle electrification.
Analysis
The investable implication is competitive rather than a direct SANY equity catalyst: a credible low-cost Chinese entrant raises the probability that European battery-electric truck pricing converges faster than incumbents expect. Daimler Truck (DTG.DE), Traton (8TRA.DE), Volvo (VOLV-B) and Paccar (PCAR) are most exposed in standardized regional-haul and vocational segments, where fleet buyers can use a new certified alternative to extract concessions even before SANY achieves material share. The near-term risk is margin dilution through higher dealer incentives, bundled service contracts and residual-value guarantees rather than an immediate volume shock.
SANY's claimed operating footprint should be treated as commercial validation, not proof of European unit economics. The critical missing data are delivered European units, fleet utilization, charging/depot partnerships, warranty reserves, financing availability and all-in total cost of ownership versus diesel and incumbent BEV models. Without those metrics, this is not sufficient to underwrite a share-loss thesis; heavy-truck purchasing remains constrained by charging access, payload penalties and fleet financing, all of which favor incumbent dealer and captive-finance ecosystems.
Over 1-3 months, watch European OEM order commentary for electric-truck discounting, service-margin pressure, or higher residual-value support. Over 6-18 months, Chinese competition could be structurally more disruptive to vocational applications, where SANY can leverage its construction-equipment and Putzmeister customer relationships to cross-sell trucks, mixers, service and financing. The contrarian view is that European incumbents may benefit if low-cost competition accelerates fleet conversion and expands the addressable zero-emission market faster than it erodes pricing; Volvo's and Daimler's service density and financing moat remain the primary thesis falsifiers for a bearish read.
A reversal of competitive concerns would be signaled by weak European registrations, failure to establish OEM-backed charging/financing partnerships, or evidence that fleet uptime and resale values lag incumbent offerings. Conversely, disclosed multi-year fleet orders or a localized assembly announcement would warrant reassessing incumbent BEV margin assumptions.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- No standalone trade on this release: wait for independently reported European registrations, customer orders and pricing before assigning meaningful market-share impact.
- Establish a 3-6 month monitoring pair, long VOLV-B / short DTG.DE in modest size, only if Daimler reports incremental BEV incentive or residual-value support while Volvo maintains service-margin guidance; target 5-8% relative return, stop on Daimler guidance reaffirmation or evidence of stronger-than-expected electric order conversion.
- Use Traton (8TRA.DE) as the highest-beta competitive-risk watch item: initiate a tactical short only after evidence of price cuts or weaker European order intake, with risk capped at 3-4% because Scania's premium brand and service attachment can offset initial vehicle-margin pressure.
- Monitor Paccar (PCAR) for second-order read-through in European DAF operations, but do not short absent evidence that competition is reaching dealer pricing; North American earnings diversification materially reduces direct exposure.
- Set alerts around 2027 European CO2-compliance milestones and any SANY fleet-financing or charging-partnership announcement; these are more consequential catalysts than trade-show product demonstrations.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- MBS and Saudi Arabia Face Crisis With Key Oil Pipeline Shut for Weeks
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Oil’s next test: Saudi Arabia races to restore a key safety valve for prices
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research