
Award-Winning Hilton Garden Inn Wayne Reveals a Fresh, Modern Look
Source: PR Newswire
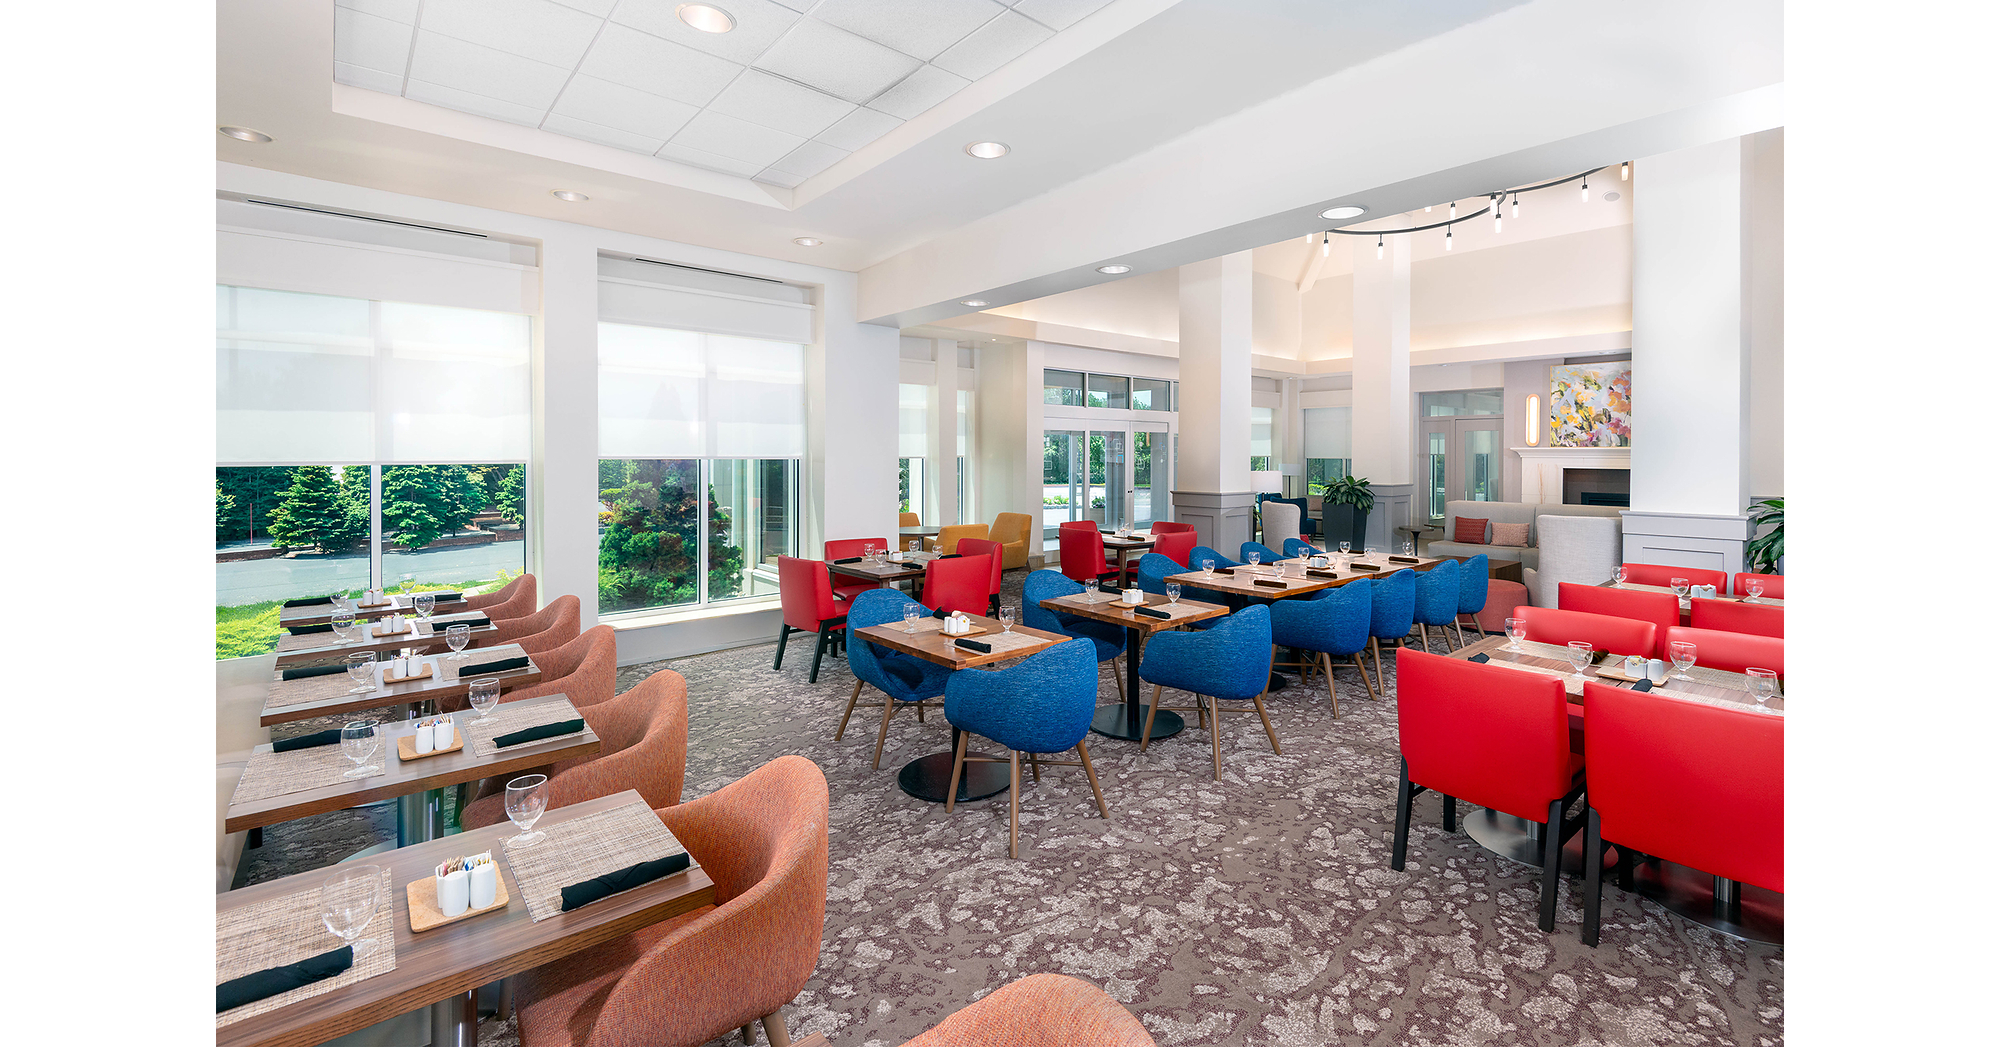
Hilton Garden Inn Wayne (125 rooms) completed a renovation, upgrading the lobby, bar/restaurant, fitness center, banquet space, boardroom, and guest-room amenities, including complimentary Wi-Fi and an indoor pool/whirlpool. The announcement highlights expanded meeting capacity of 2,300 sq. ft. with upgraded A/V and on-site catering, plus a convenient location about 25 miles from Manhattan. This is largely a property upgrade/operations update with limited implications for public-market pricing.
Analysis
This reads more like routine upkeep than a fresh earnings signal, but it does reinforce an important lodging mechanism: in a slower-growth travel market, asset quality is often the main way operators defend rate rather than fill. The economic value accrues mostly to the branded platforms with distribution and loyalty power, while the capex burden sits with the owner/franchisee; that asymmetry tends to favor HLT, MAR, and CHH over lower-quality hotel owners that must spend to stay competitive.
Second-order, the bigger story is not this one property but the pressure on smaller, undercapitalized operators to keep pace with brand standards. Over 6-18 months, that can widen the gap between well-capitalized franchisees and independents, supporting branded RevPAR resilience while compressing FCF for owners with aging portfolios or leveraged balance sheets. The flip side is that if renovation payback does not translate into ADR uplift within 1-2 quarters, the market will start treating these programs as maintenance capex with poor returns.
Near term, this is not a tradable catalyst on its own. The falsifier is simple: if upcoming lodging prints show softer occupancy and no pricing power, renovation announcements will be seen as defensive spending rather than a demand tailwind. The real watch item is whether this is part of a broader industry reflagging/refresh cycle; if not, the move is noise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
neutral
Sentiment Score
0.10
Key Decisions for Investors
- No immediate trade on this announcement alone; treat it as noise unless we see a cluster of similar renovation/capex disclosures and then rising RevPAR in the next 1-2 quarters.
- Watch-list long HLT / MAR on dips for a 3-6 month thesis that brand quality and distribution gain share as weaker owners defer capex; thesis breaks if franchisee commentary turns to pressure on fee growth or renewal rates.
- If lodging data soften, consider short PK or APLE vs long HLT as a 6-12 month quality/capex pair: branded platforms should hold pricing better while asset-heavy owners absorb reinvestment drag.
- Set an alert around the next quarterly hotel earnings cycle: if ADR fails to accelerate after renovation spend, avoid chasing any 'asset refresh' narrative and fade hotel-exposed names on strength.
More News
- Musk says Terrafab chip factory could outperform rivals despite challenges
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- Cerebras Is About as Big as Nvidia's Data Center Business Was Nearly a Decade Ago. The Similarities Mostly End There.
- How Supreme Court justices are leaning in major 401(k) case over private funds and underperformance