
Yutong inaugure son premier centre de services complet en Europe
Source: PR Newswire
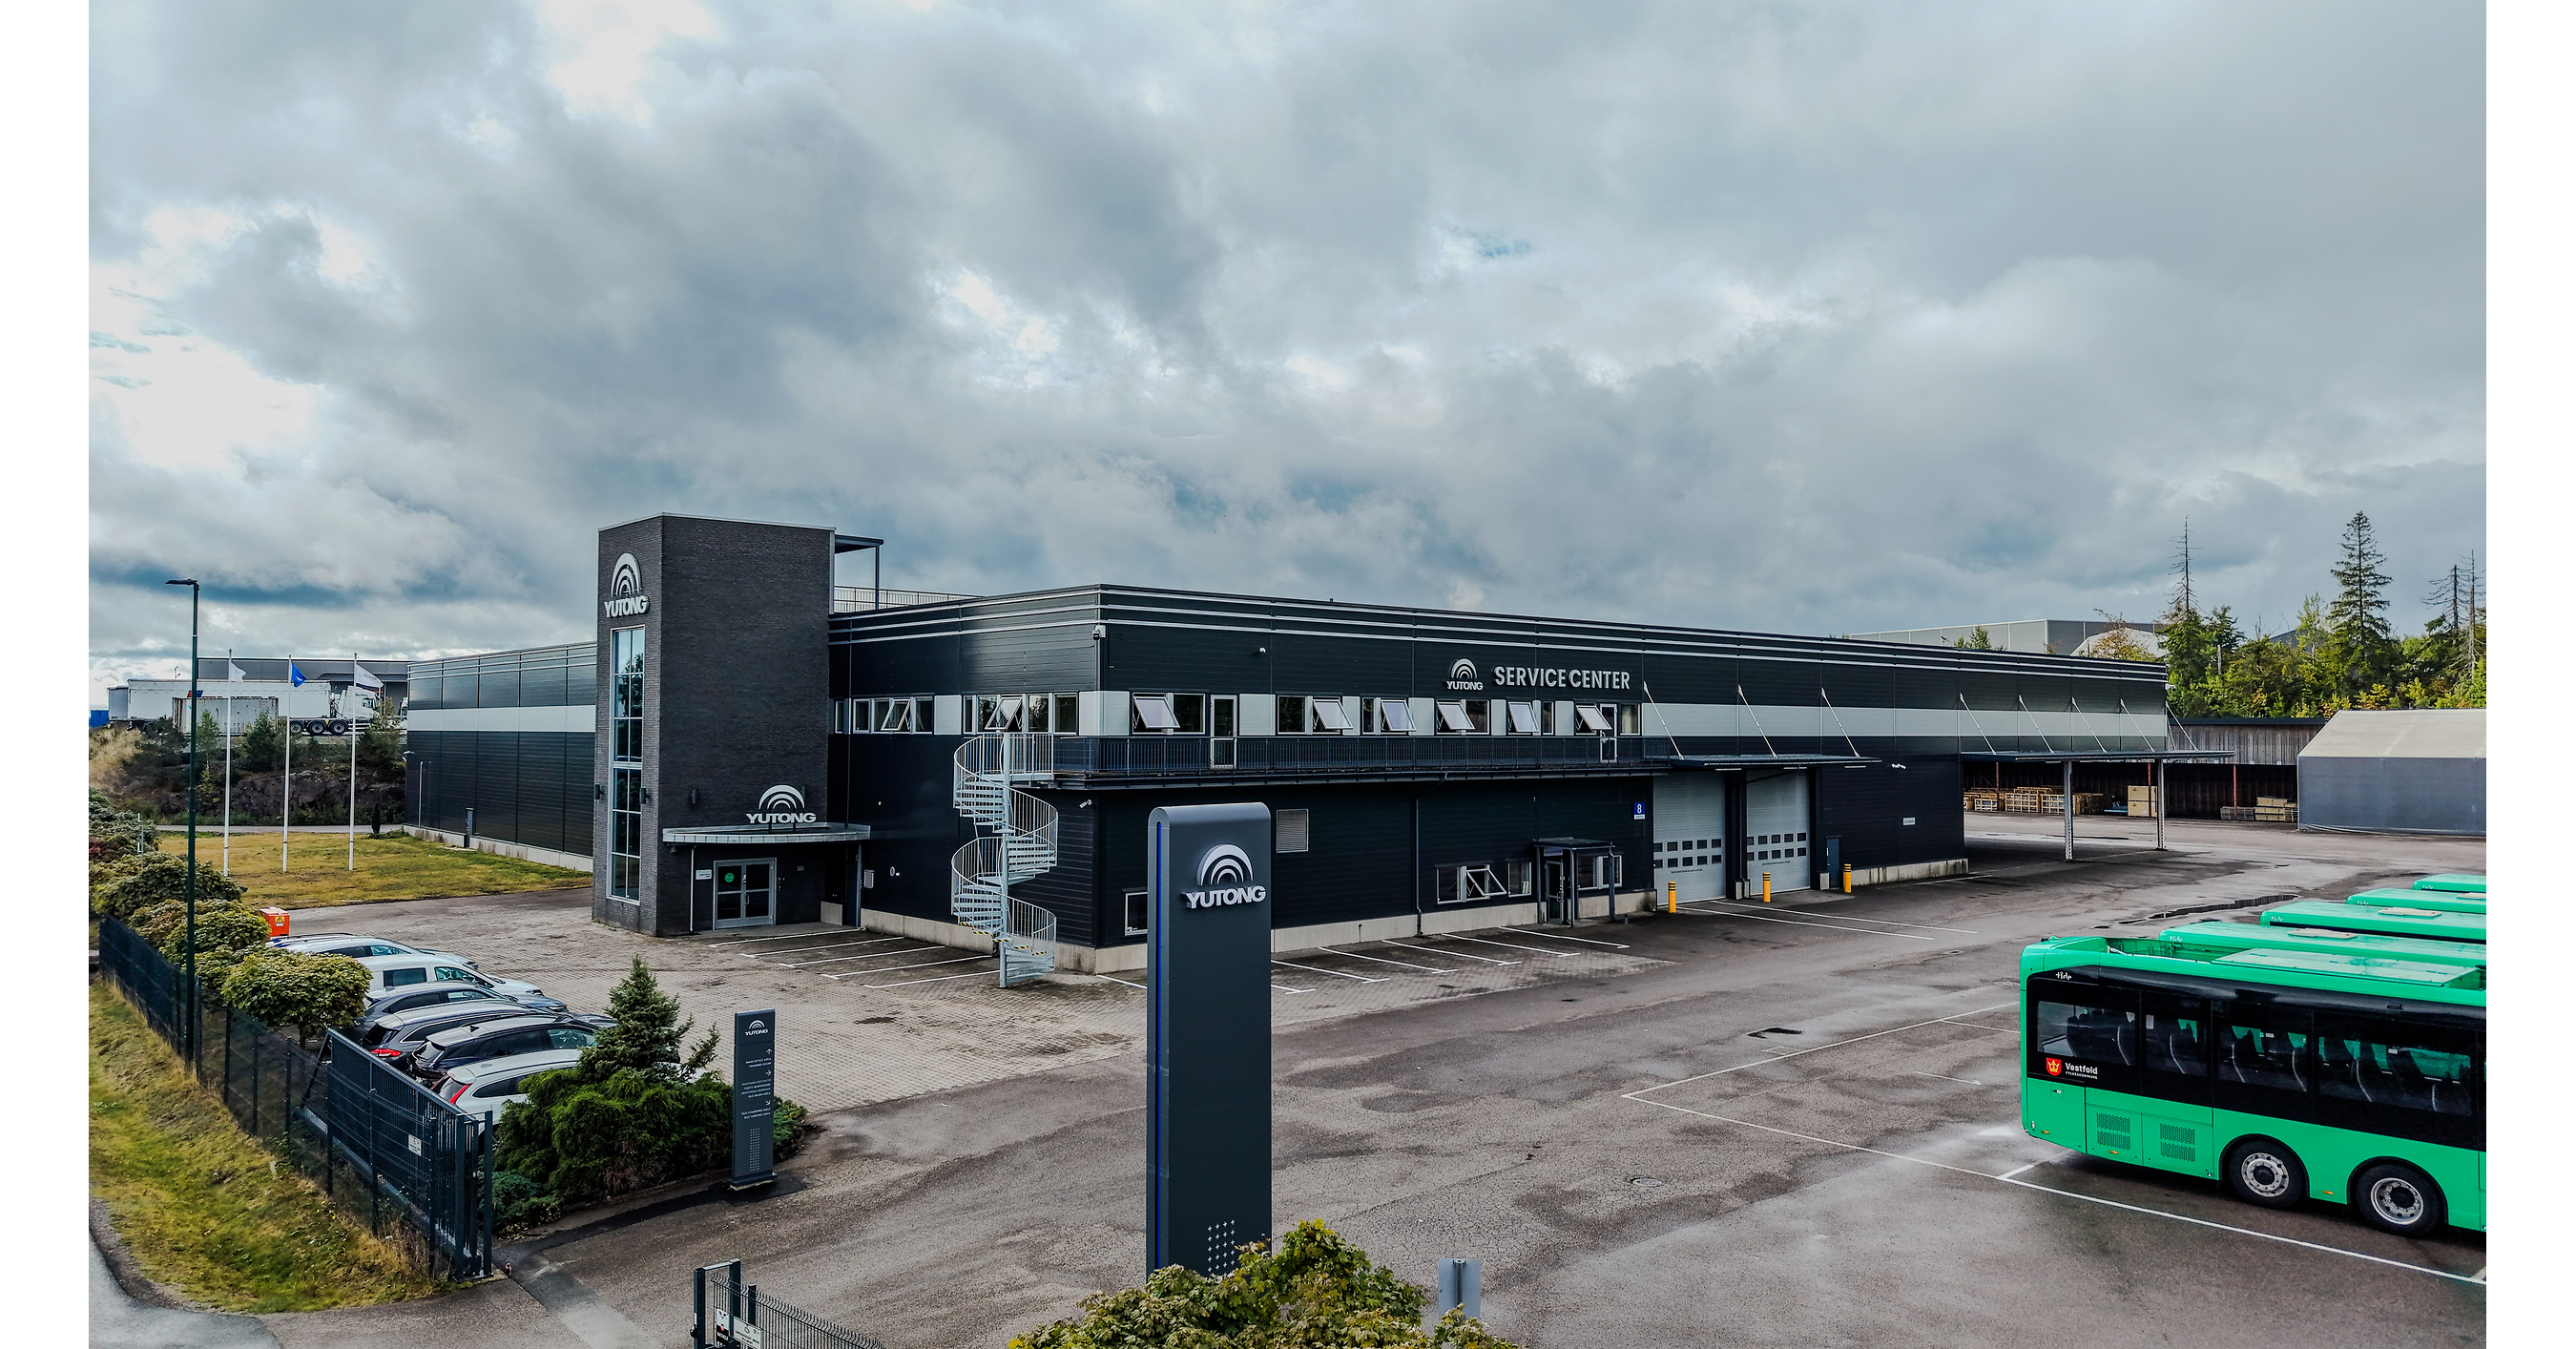
Yutong Bus opened its first full-service European center in Stokke, Norway, spanning 38,941 square meters with 6,074 square meters of built space and a 2,300-square-meter spare-parts warehouse. The facility provides electric-bus delivery, maintenance, inspections, training and 4,500 original-parts references, aiming to reduce fleet downtime and total ownership costs for Norwegian operators. The investment strengthens Yutong's European after-sales infrastructure and supports Norway's public-transport electrification, though the announcement does not disclose financial commitments or revenue impact.
Analysis
The strategic signal is not incremental European bus demand but a shift in Yutong's bid economics: local lifecycle support reduces the perceived residual-value, uptime and warranty risk that has historically protected incumbent OEMs in public-transit tenders. This is most consequential in Northern Europe, where procurement increasingly weights availability guarantees and total cost of ownership rather than upfront vehicle price. The likely pressure point is on Volvo B (VOLV-B.ST), Daimler Truck (DTG.DE) and TRATON/Scania (8TRA.DE), whose installed service networks have been a key non-price moat; competing may require more aggressive service-level commitments, raising warranty and field-service costs before revenue is affected.
There is no near-term tradable earnings impact from one facility, and the announcement is company-sourced without disclosed fleet contracts, capacity utilization or service-margin economics. Over 1-3 months, watch Nordic and Benelux electric-bus tender awards, especially awards that separate vehicle and maintenance contracts: repeat Yutong wins would validate that localized support is converting into share gains. Over 6-18 months, the larger risk to European OEMs is margin dilution rather than unit loss, as Chinese entrants can bundle lower-priced hardware with parts availability and uptime guarantees; the thesis is falsified if incumbents retain tender win rates without concessions in service pricing or contract terms.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No directional position on this announcement alone: Yutong's listed parent, Zhengzhou Yutong Bus (600066.SS), and relevant European peers require tender-level evidence before underwriting an earnings revision.
- Create a 3-month alert for Nordic/Benelux zero-emission bus tenders: initiate a modest long 600066.SS / short VOLV-B.ST relative-value position only if Yutong wins at least two meaningful European contracts with multiyear maintenance attached. Target 10-15% relative return; exit if Volvo retains comparable tender share or discloses stable service-contract margins.
- For existing long positions in DTG.DE or 8TRA.DE, monitor order-book commentary for electric-bus pricing, warranty provisions and service attachment rates at the next earnings update. A decline in service profitability or higher provisions is a more actionable negative catalyst than headline vehicle deliveries.
- Avoid broad EV or battery-equity exposure as a read-through: the relevant transmission channel is transit-OEM aftermarket competition, not incremental battery demand, and the facility itself does not establish a material change in European fleet volumes.
More News
- Iran says won’t allow US warships to get close as Trump ponders new attacks
- Israelis hold final rally against Netanyahu ahead of what may be the most consequential election in the country’s history
- Sudan’s soaring fuel prices make getting by harder for workers
- Trump set to announce plan by Audi to build a U.S. factory in Georgia, source says
- Ukraine says Starlink and Starshield high speed restrictions have been lifted
- Why popular airplanes are getting scrapped years early
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Research Systems for Hedge Funds: A Pilot Design
- Weekly Update: New Reporting Features, UI Improvements, and Chat Optimizations