
Northern Virginia Oral Surgeons Davary & Smith Mark First Year as an Independent Practice in Sterling
Source: PR Newswire
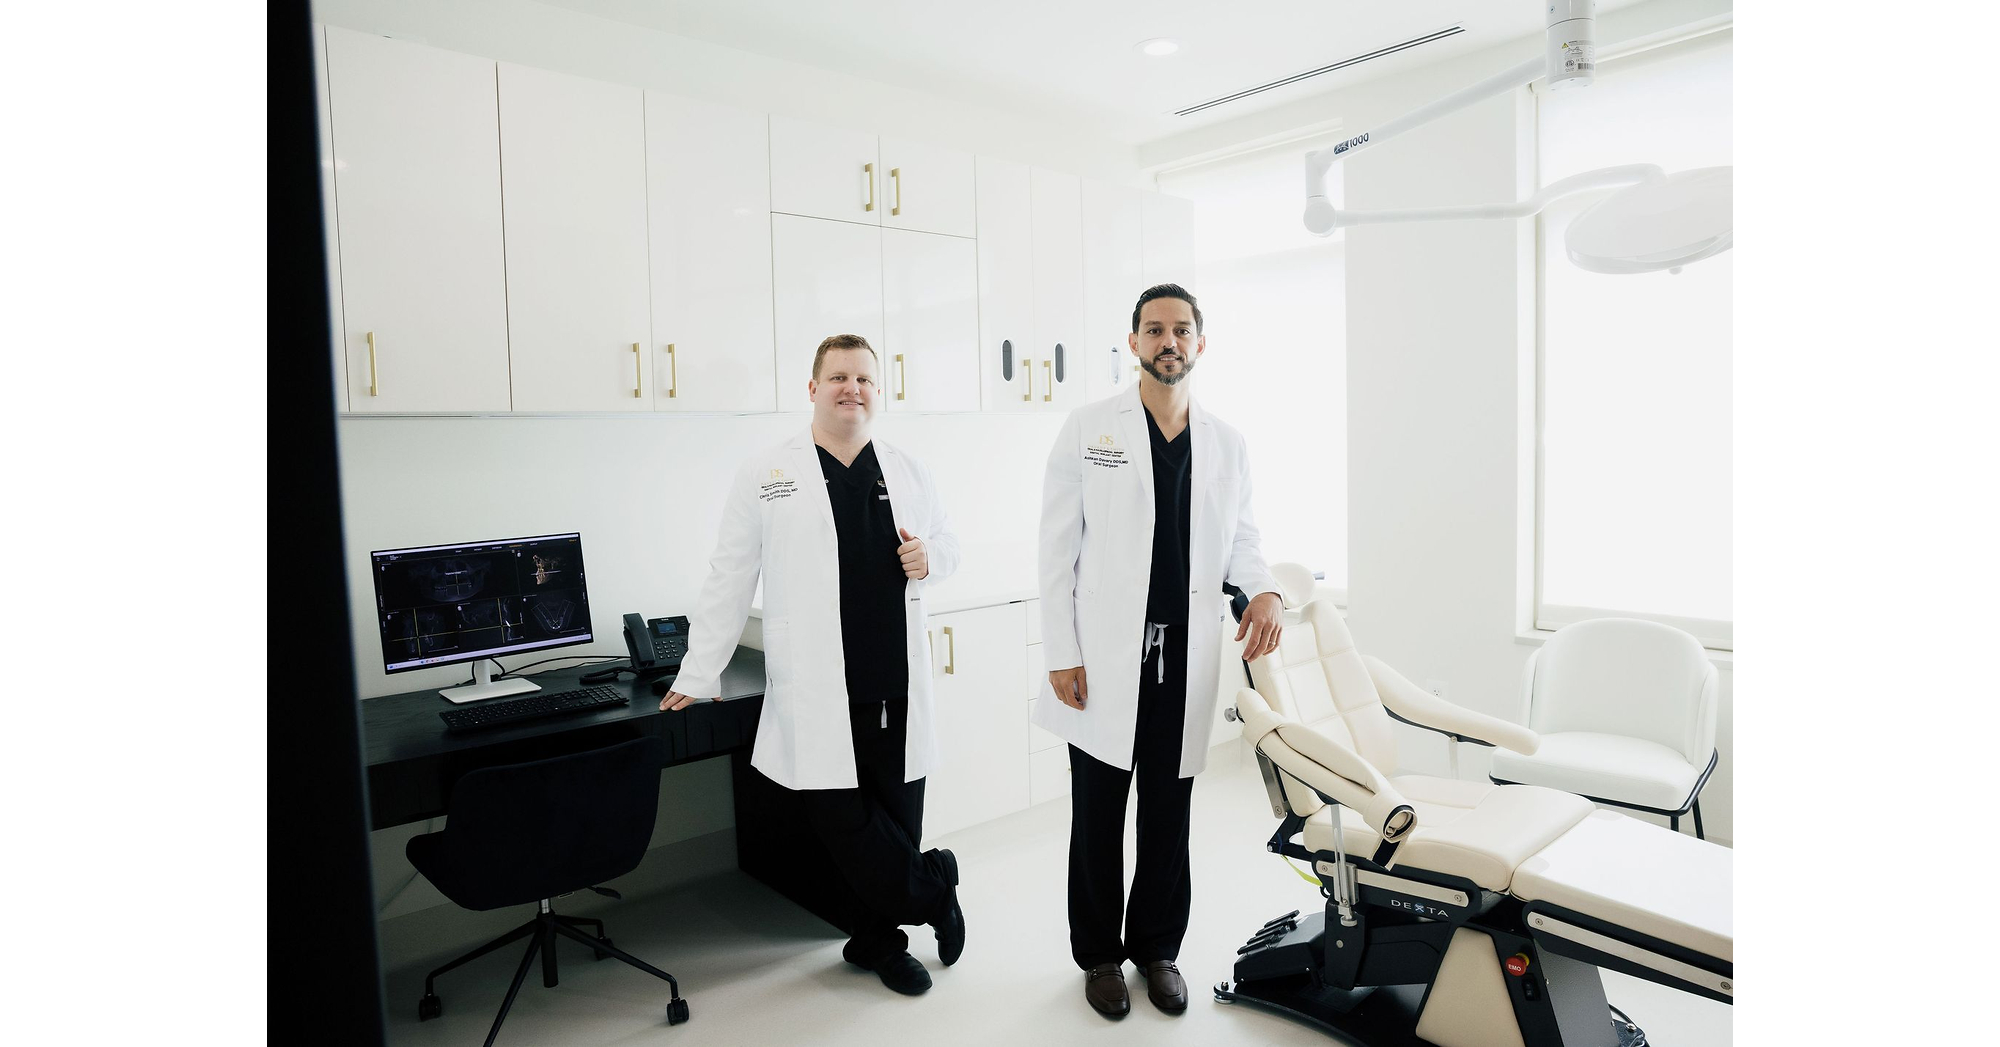
Davary & Smith Oral & Maxillofacial Surgery marked its first year of operations in Northern Virginia, highlighting its independently surgeon-owned model and NFPA 99 Category 1 hospital-standard anesthesia facility. The practice said it provides services ranging from wisdom-tooth extraction to full-arch implants and uses non-opioid pain-management protocols, including EXPAREL. The announcement contains no financial results, growth metrics, funding activity, or material market-moving development.
Analysis
This is a local private-practice marketing release with no directly investable issuer, no disclosed patient volumes, payer mix, pricing, utilization, or capital structure, and therefore no basis for a public-markets trade. The relevant read-through is modestly negative for PE-backed dental-service organizations if independent surgeon-owned practices can use higher-acuity capabilities and direct-to-consumer acquisition to retain profitable implant and complex-extraction cases; however, one facility’s first-year claims are not evidence of a scalable competitive shift.
The more investable mechanism is procedure mix rather than the operator itself. Higher-margin implant, full-arch, and sedation-enabled cases can pull revenue from general-dentistry networks toward specialists, while office-based complex care may marginally reduce demand for hospital outpatient capacity. This is directionally supportive for implant and digital-dentistry equipment ecosystems such as DENTSPLY SIRONA (XRAY), Envista (NVST), and Straumann (STMN.SW), but the incremental volume implied here is immaterial relative to their geographic diversification.
Over the next 6-18 months, the key structural question is whether independent specialty practices gain share as PE platforms face clinician-retention, reimbursement, and leverage constraints. That thesis requires corroboration through specialty-practice formation data, implant procedure growth, and evidence of weakening same-store production at consolidators; absent those data, assigning a valuation impact would be speculative. The contrarian view is that independent practices may expand the referral funnel rather than displace platforms, particularly where corporate groups lack hospital-grade anesthesia capacity and instead refer complex cases externally.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.22
Key Decisions for Investors
- No new position: treat this as non-actionable company-specific publicity rather than a sector catalyst; do not extrapolate to public dental-equipment or care-delivery names.
- Place XRAY and NVST on a 1-3 month watchlist for broader evidence that high-acuity implant volumes are accelerating: verify through quarterly implant consumables growth, management commentary on specialist demand, and U.S. elective-procedure trends before considering exposure.
- For any future PE dental-consolidation thesis, monitor clinician turnover, same-store production, and net leverage at relevant private operators; a documented loss of complex-case share to independents would support a relative short, while stable referral economics would falsify it.
More News
- Here’s the ‘core economic flaw’ in the AI bull case as stock and bond trades unravel, according to a top economist
- Biotech stocks are surging. How investors can play the new drug innovation boom
- Braskem creditors, shareholders near deal on $11bn debt restructuring
- Instacart reportedly discussed selling itself with DoorDash and Uber
- Nvidia's role as AI financier faces first big test as neoclouds take market hit
- Trump set to announce plan by Audi to build a U.S. factory in Georgia, source says