
Zoomlion Strengthens European Localization through Expanded Service, Manufacturing, and Technology Collaboration
Source: PR Newswire
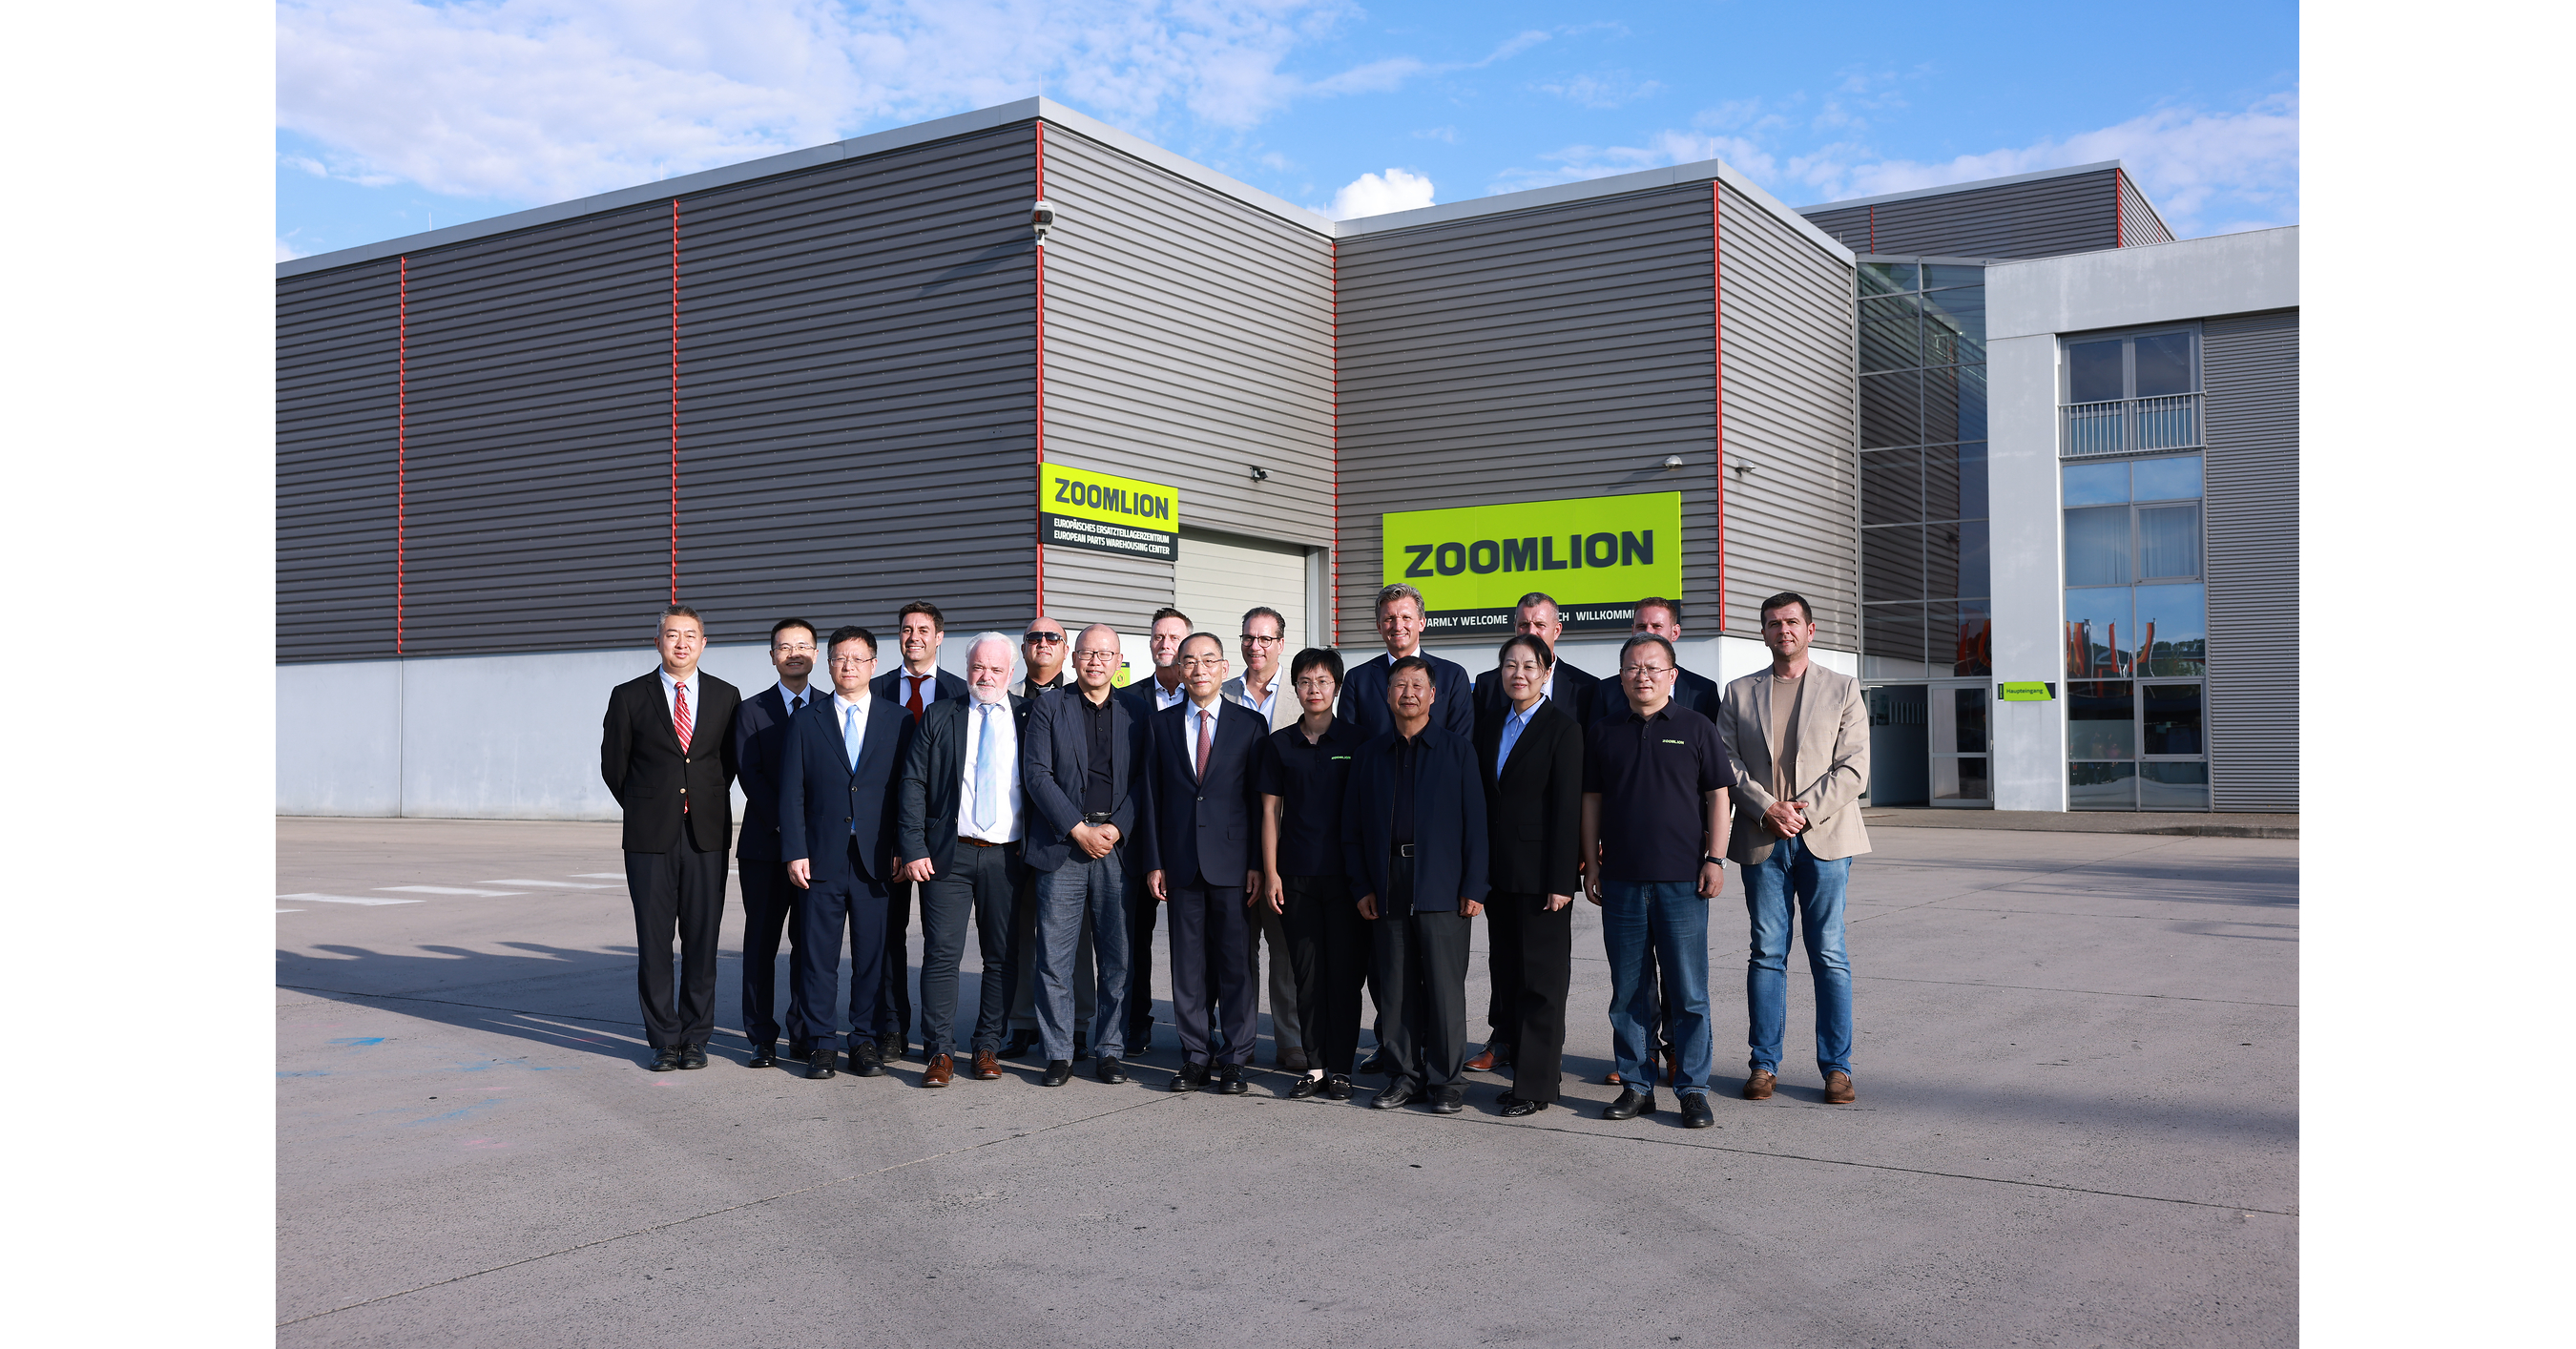
Zoomlion will deepen its Europe localization by expanding local sales, manufacturing, and service networks, with a focus on faster spare-parts availability and improved long-term service responsiveness. The company plans to roll out a customer-facing digital service platform to automate service task assignment and tracking. Management also highlighted ongoing support for German subsidiary m-tec, including technology development such as R&D and 3D-printing applications.
Analysis
The near-term read-through is modestly positive for ZLIOY, but the bigger implication is defensive rather than transformational: management is trying to reduce the two biggest friction points in heavy equipment exports — downtime risk and after-sales credibility. If executed well, that can improve win rates in Europe and stabilize pricing, but it usually comes with lower gross margin because local inventory, field service, and manufacturing dilute the leverage of a pure export model.
Competitive dynamics matter more than the press release tone suggests. A deeper European footprint can pressure regional incumbents such as Liebherr, Wacker Neuson, Manitou, and Volvo CE at the margin, especially in smaller fleets where service response is a purchase criterion. The second-order effect is on dealer economics: better parts availability can shift value away from third-party distributors toward OEM-controlled service, improving attachment rates but requiring working capital and a stronger balance sheet.
The main risk is that Europe becomes a capex sink before it becomes a profit engine. Localization typically raises fixed costs, inventory days, and compliance overhead before utilization catches up; that can mute any share gains for 6-18 months. The market may be overreading this as a growth inflection when it may simply be a retention strategy in a tougher regulatory and procurement environment.
Contrarian view: if European customers still demand proven uptime, financing, and brand trust, the real benefit may accrue first to the local incumbents and not Zoomlion, despite the company’s expansion plans. The thesis would be falsified if Europe revenue growth, service revenue mix, or gross margin fails to improve over the next 2-3 quarters while receivables and inventory continue to rise.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Ticker Sentiment
Key Decisions for Investors
- No immediate long in ZLIOY on this headline alone; wait 1-2 quarters for proof in Europe revenue growth, gross margin, and inventory turns before paying for the localization story.
- If you want exposure, use a staggered starter long in ZLIOY only on pullbacks, with a hard stop if Europe growth does not accelerate in the next earnings cycle; this is a 6-12 month thesis, not a catalyst trade.
- Relative-value idea: long global service-heavy industrials with recurring revenue exposure versus ZLIOY until the company demonstrates that localization is accretive rather than margin-dilutive.
- Watch for falsifiers: rising receivables/inventory or flat European order intake over the next 2-3 quarters would argue the expansion is consuming capital faster than it creates franchise value.
More News
- AI Capex, Gamble or Jackpot?: Market Snapshot
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- ‘I told you so’: China’s chip sector is making breakthroughs—and U.S. export controls are the reasons why
- UK's Healey Plans to Raise Bank Taxes
- One Singapore ship was sunk, but here's why others are still transiting the Strait of Hormuz
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt