
Sizing Up Cerebras Systems: Why Its Latency Moat Makes It A Buy For Aggressive Growth Investors
Source: seekingalpha.com
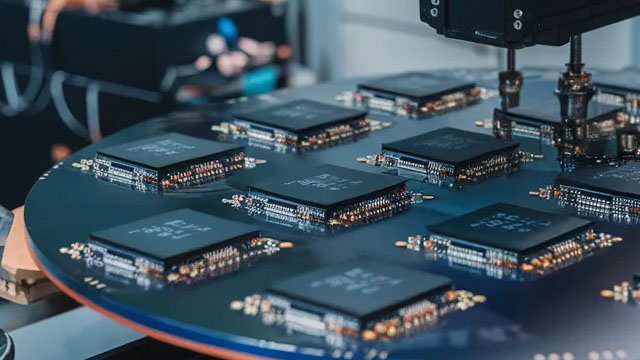
Cerebras is positioning its CS-4 chip and wafer-scale architecture to lead in AI inference, targeting latency-sensitive workloads and aiming to justify a premium valuation through gross margin expansion and improved core operating margin toward GAAP profitability. The article flags key risks that could derail traction, including Nvidia’s entrenched ecosystem, potential manufacturing yield challenges, and weaker competitiveness for models/applications that need large KV caches.
Analysis
This looks less like a broad AI displacement story and more like a narrow attack on the lowest-latency slice of inference. That matters because the economically relevant moat in AI infra is not just chip speed, but software portability, deployment tooling, and the ability to serve mixed workloads; if the workload shifts toward large-context, high-KV-cache inference, CBRS’s addressable niche shrinks quickly while NVDA’s ecosystem advantage compounds.
The real near-term variable is execution quality, not product claims. Gross margin and utilization will likely drive the stock more than revenue headlines, because a wafer-scale architecture can look elegant on paper but still fail the P&L if yields are uneven or datacenter ramp is lumpy. Watch the next 1-3 quarters for evidence that fixed-cost absorption is improving; absent that, premium valuation can compress fast even if bookings appear healthy.
Second-order effects are asymmetric: a credible edge-inference alternative could pressure pricing in latency-sensitive workloads, but it is unlikely to dent NVDA’s core training franchise or its large-batch inference economics in the next 6-18 months. The contrarian risk is that the market underestimates how quickly a small, highly targeted inference win can become sticky if developers standardize around it; if CBRS shows successive margin expansion and any sign of software adoption, the bear case weakens materially. Falsifiers for the short thesis are simple: two consecutive quarters of gross margin expansion, improving operating leverage, and evidence that large-KV-cache limitations are being offset by workload-specific wins.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly negative
Sentiment Score
-0.15
Ticker Sentiment
Key Decisions for Investors
- Short CBRS on strength into any post-news multiple expansion; use a 1-3 month horizon and cover if gross margin guidance improves by more than expected or if utilization inflects sharply higher.
- Pair trade: long NVDA / short CBRS as a relative-value expression of ecosystem durability versus execution risk; the trade benefits if AI inference demand broadens without validating a niche hardware challenger.
- Set a watch item on CBRS next earnings for gross margin and core operating margin progression; if both fail to improve, treat the stock as a valuation-air-pocket candidate rather than a growth compounder.
- If CBRS prints two clean quarters of yield and margin improvement, reverse the position and consider a tactical long for 6-18 months, as the market may be underestimating operating leverage from a concentrated product mix.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- Wall Street is pitching data centers as a major real estate bet. The risks are piling up
- AI predicts Palantir stock price for end of Q4 2026
- Nvidia-Backed Lumentum Says It Can't Keep Up With AI Demand. The Stock Is Surging
- From H-1B to CEO: How Satya Nadella traveled the path the U.S. just cut off for Microsoft workers