
Archer Aviation Stock Is Down 50%. Is Now Finally the Time to Buy?
Source: fool.com
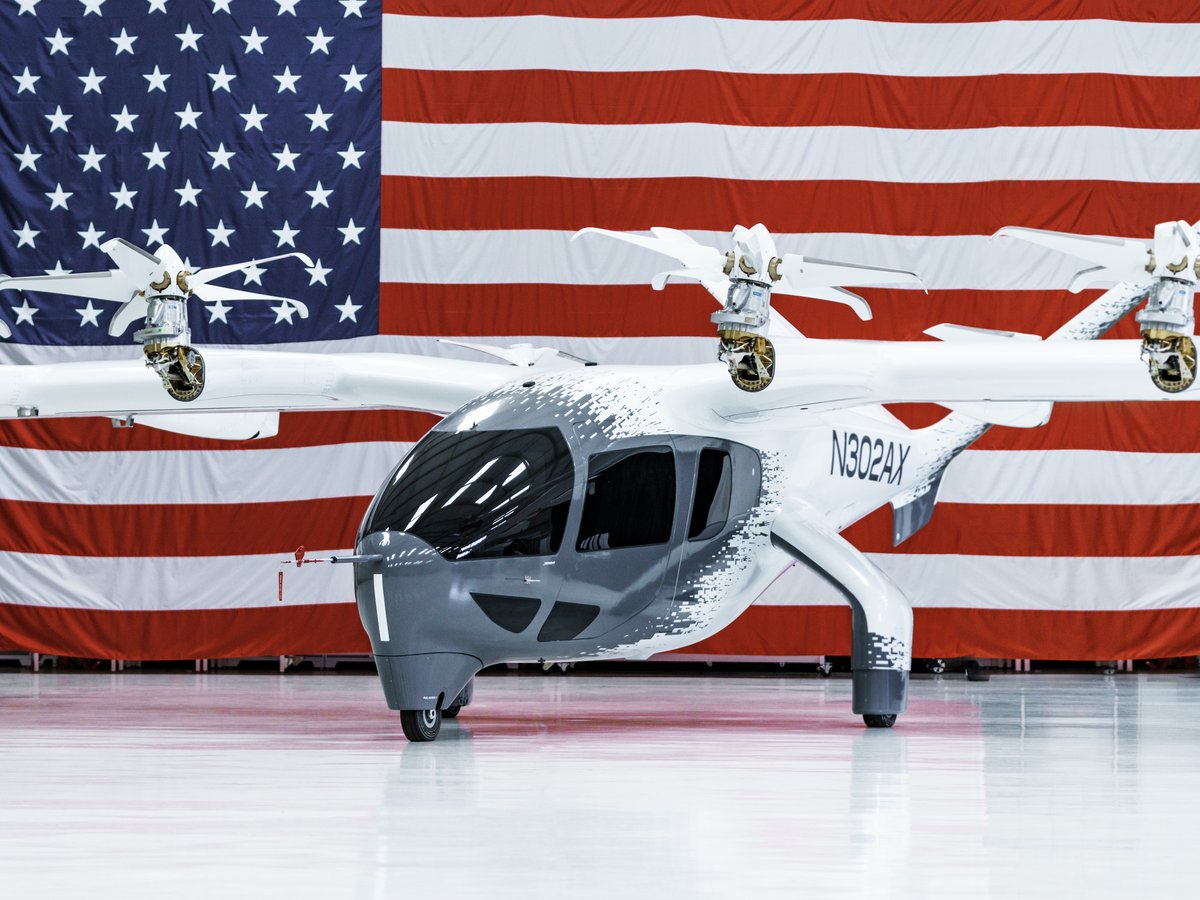
Archer Aviation shares have fallen more than 50% in 2026, from about $8 to less than $4. The article says the company remains years from proving that its eVTOL air taxis can be profitable, with demand, fares, operating costs, and production capacity still uncertain. The stock may suit long-horizon investors comfortable with volatility, but others may prefer to avoid it.
Analysis
ACHR: optionality is cheapened, not de-risked. The selloff may improve the payoff for investors underwriting certification and a new urban-air-mobility market, but it does not itself resolve the key valuation variables: certification timing, production yield/cost, funding runway, and whether route-level fares cover operating and maintenance costs. In the near term, expect milestone headlines and risk appetite to dominate fundamentals; a certification delay or financing that materially dilutes existing holders could overwhelm any broad eVTOL enthusiasm. Over 1–3 months, track regulatory milestones and cash consumption against management’s stated plan. Over 6–18 months, the decisive evidence is repeatable aircraft production and credible unit economics—not reservations or launch-city announcements. Competitors such as Joby could benefit from any ecosystem validation, but also compete for capital, suppliers, and regulatory attention; relative execution matters more than the sector label. Contrarian point: the price decline may tempt investors to treat ACHR as a conventional beaten-down growth stock, when it remains a long-duration, execution-dependent option. The thesis improves only with independently verifiable progress; absent that, a low share price is not a margin of safety.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mixed
Sentiment Score
-0.10
Ticker Sentiment
Key Decisions for Investors
- No immediate directional trade on the article alone. Keep ACHR on a milestone watchlist; before adding, verify current cash runway, expected cash burn, financing capacity, and the latest certification schedule.
- For long exposure, scale in only after a verifiable regulatory milestone and evidence that production plans are translating into repeatable output. Size as venture-like risk; the downside case includes further delay, dilution, or failure to establish viable fare economics.
- Avoid using Joby as a simple hedge: both names may move with sector sentiment and regulatory news. Consider a relative-value position only after comparing certification progress, liquidity/runway, and production plans using current filings.
- Falsify the cautious thesis if ACHR demonstrates sustained certification progress, credible manufacturing execution, and improving cash-burn visibility. Reassess negatively on a material schedule slip, adverse regulatory development, or financing that substantially expands the share count.
More News
- Wall Street Thinks Archer Aviation Is a Buy. Here's Why I Don't.
- SpaceX closes $40 billion debt deal for AI chips, Elon Musk says
- Earnings playbook: Alphabet, Microsoft, Amazon and more report this week. Here's what to expect
- More pain may be coming for the AI trade. Why I’m not giving up on it
- Saudi Arabia intercepts missiles and drones as fighting with Houthis rages
- AI Spending Fears Threaten to Swamp Big Tech’s Strong Earnings