
WHP Global, G-III Apparel Group and I.T Group Announce Partnership to Accelerate Marc Jacobs Growth in Greater China
Source: PR Newswire
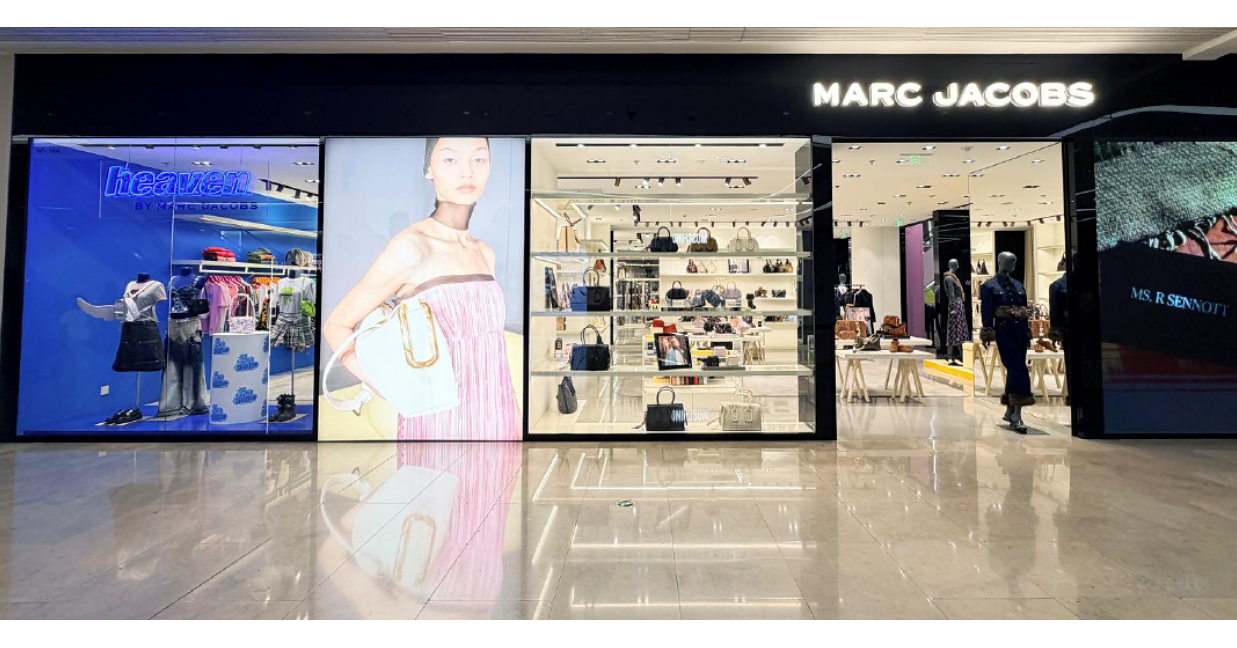
I.T Group acquired Marc Jacobs’ existing Greater China operating business and signed a new long-term licensing agreement with WHP Global and G-III Apparel Group to expand the brand in the region. I.T plans to invest in boutiques, shop-in-shop locations, digital commerce and wholesale distribution; the parties characterized the partnership as a growth milestone but disclosed no financial terms or quantified targets.
Analysis
The key signal is a test of whether G-III and WHP can turn Marc Jacobs ownership into repeatable, lower-capital licensing economics—not evidence yet of meaningful earnings accretion. Transferring the existing China operating business may reduce G-III’s direct exposure to local retail costs and execution, but could also replace reported operating revenue with royalties; the net value depends on deal economics and how G-III’s ownership and revenue share are structured. Neither is disclosed here.
Near term, the announcement is a modest validation point for G-III’s recently acquired brand portfolio, but the market should not capitalize expansion plans as realized sales. Over 1–3 months, watch for disclosed royalty terms, treatment of the transferred business in G-III reporting, and evidence of sell-through rather than store-opening targets. Over 6–18 months, I.T Group’s local retail and digital execution could expand distribution; the counter-risk is discounting or over-expansion diluting brand positioning, compounded by Greater China demand and geopolitical volatility.
The contrarian point: a local operator with an established multi-brand platform is not automatically incremental demand. It may shift existing Marc Jacobs sales between channels or accelerate footprint without attractive unit economics. No direct read-through to Lands’ End or Levi Strauss is justified by this brand-specific deal. Falsify the positive thesis if G-III’s disclosures show material operating revenue lost without offsetting royalties, or if expansion fails to translate into sustained sell-through and brand pricing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.40
Ticker Sentiment
Key Decisions for Investors
- No standalone trade on the release: keep GIII on the watchlist rather than buying the headline, given undisclosed economics and uncertain consolidated earnings impact.
- At G-III’s next disclosure, verify the ownership/economic split with WHP, the China business’s contribution before transfer, expected royalty structure, and whether transferred sales leave reported revenue. Reassess only when these bridge to earnings or cash flow.
- If those disclosures show attractive recurring royalties with limited G-III capital or operating exposure, consider a measured long GIII on a post-announcement pullback; invalidate if management indicates the revenue transfer is material and royalties do not offset it.
- Track I.T Group’s store productivity, online sell-through, and discounting over the next 6–18 months. Store-count growth without healthy full-price demand would undermine the brand-expansion thesis.
More News
- Marc Jacobs partners with I.T Group for Greater China expansion
- Federal Reserve is likely to hold interest rates steady in October. Here's what that means for consumers
- From Wall Street to Silicon Valley, Anthropic IPO poised to have massive 'trickle-down effect'
- Anthropic’s IPO filing shows explosive growth, risks and staggering costs
- EQT becomes the nation’s leading natural gas ‘juggernaut’ with a $13B deal as data center, export demand surges
- Microsoft offers buyouts to nearly 30% of workforce in ongoing AI shift