
Piramal Pharma Strengthens Future Ready Operations with 22.6% Emissions Reduction, 41% Renewable Energy and Zero USFDA OAI Observations
Source: PR Newswire
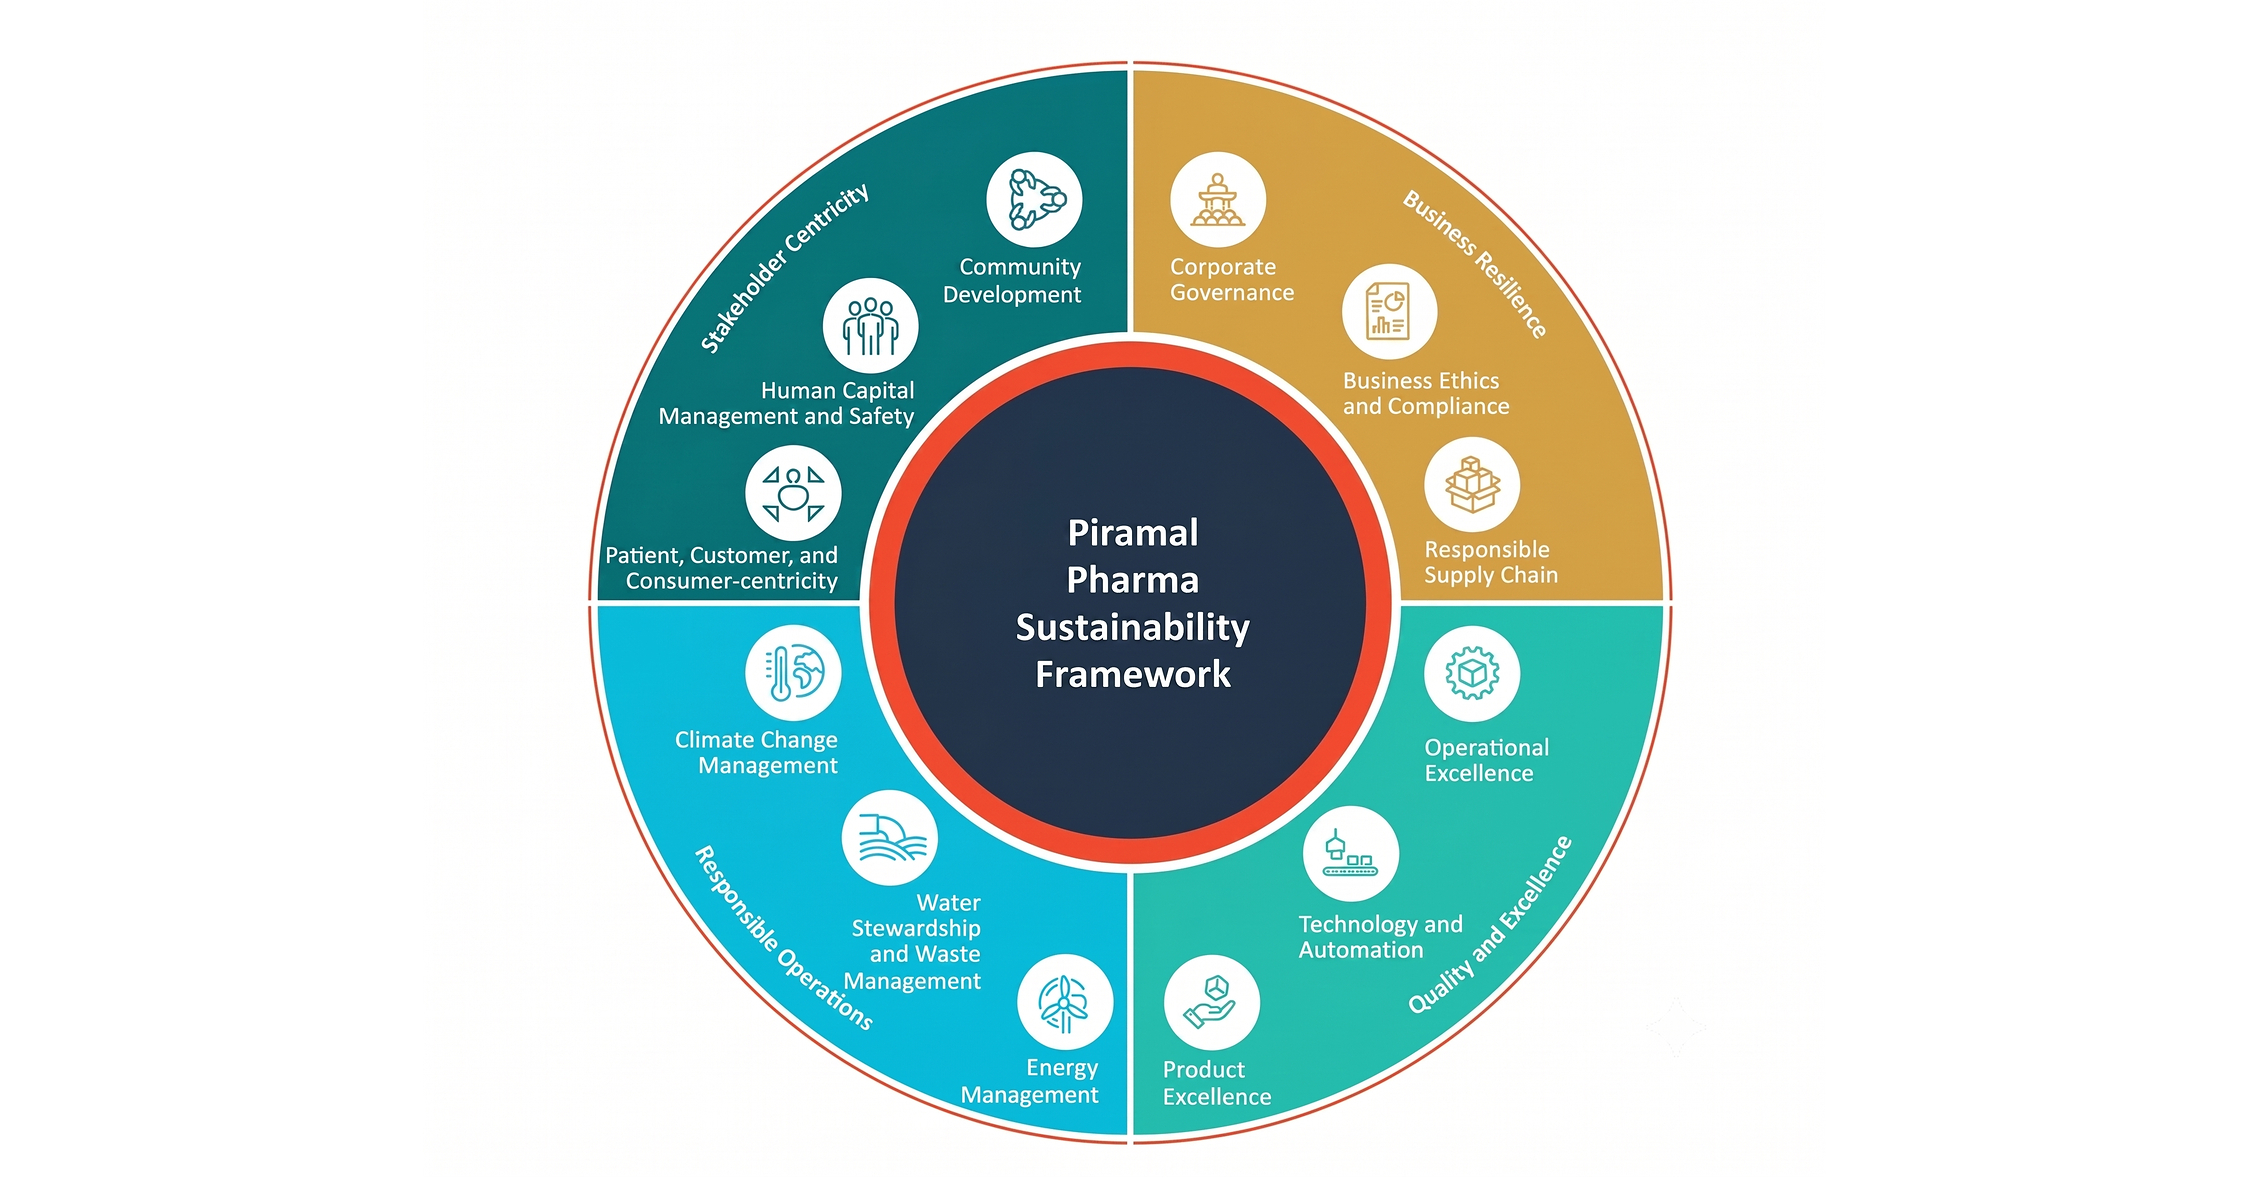
Piramal Pharma reported a 22.6% reduction in Scope 1 and Scope 2 emissions vs the FY2022 baseline and increased renewable energy to 41% of total energy use. The company also highlighted zero USFDA Official Action Indicated (OAI) observations across three USFDA inspections alongside 38 total regulatory inspections. Operational capability expansion was supported by a planned US$90 million investment for advanced therapeutics at its Lexington and Riverview facilities, with no data breach incidents during the period.
Analysis
For Piramal Pharma, the market-relevant signal is not the sustainability scorecard; it is the compounding effect of cleaner inspection history plus digital quality systems on future bid conversion. In CDMO and complex generics, a clean USFDA record can matter more than a quarter of incremental growth because it lowers customer switching friction and supports pricing discipline. That creates a slow-burn advantage versus Indian peers with more visible regulatory overhang, but it is unlikely to show up in revenue immediately.
The trade-off is capital intensity. The new manufacturing expansion and systems rollout should improve long-run mix and compliance resilience, yet near-term it likely depresses free cash flow and may keep headline multiples capped if investors focus on execution risk rather than ESG optics. The first-order beneficiaries are customers and partners that value de-risked supply, including AbbVie-linked exposure through the India JV; the second-order loser is any rival CDMO that competes mainly on cost rather than regulatory quality.
Contrarian view: this looks modestly underappreciated only if the company can translate better compliance into faster commercial wins over the next 2-3 quarters. If the next inspection cycle is clean and advanced therapeutics capacity ramps without margin dilution, the stock can rerate on lower perceived operational risk. Falsifiers: any USFDA observation, capex delay, or weaker-than-expected FCF conversion would unwind the thesis quickly.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.28
Ticker Sentiment
Key Decisions for Investors
- PHMMF: small long on pullbacks, 3-6 month horizon; thesis is regulatory de-risking and customer-win optionality, but size modest because the ESG headline alone is not an earnings catalyst.
- Pair trade: long PHMMF vs short a basket of higher-regulatory-risk Indian pharma/CDMO names over 1-2 quarters; looking for relative multiple expansion if inspection quality remains clean.
- ABBV: monitor as a secondary beneficiary only; no direct trade from this release, but a cleaner India supply/partner ecosystem modestly supports long-duration sourcing resilience.
- Set an alert for the next USFDA interaction and 1H execution on the $90m expansion; if margins or FCF deteriorate while capex rises, take profits or avoid adding.
- If you need a catalyst-based entry, wait for post-report weakness rather than chasing the print; the asymmetric setup is lower downside from de-risking, not an immediate re-rating.
More News
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Bank of America is bullish on these top stocks ahead of earnings
- As companies pour billions into Earth-based AI infrastructure, Google is taking the data center race off-planet
- AI's Supercharging a Scam Economy Bigger Than the Cocaine Trade
- How U.S. know-how is fracking Australia into a gas boom, from Texas oilmen to Trump’s energy secretary
- The world needs Ukraine’s grain. Its farmers are running out of reasons to plant
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance
- Can Hedge Funds Use ChatGPT? A Control Framework