
HCW Announces New 140-Room Tapestry Collection by Hilton Hotel at Horseshoe Indianapolis
Source: PRWeb
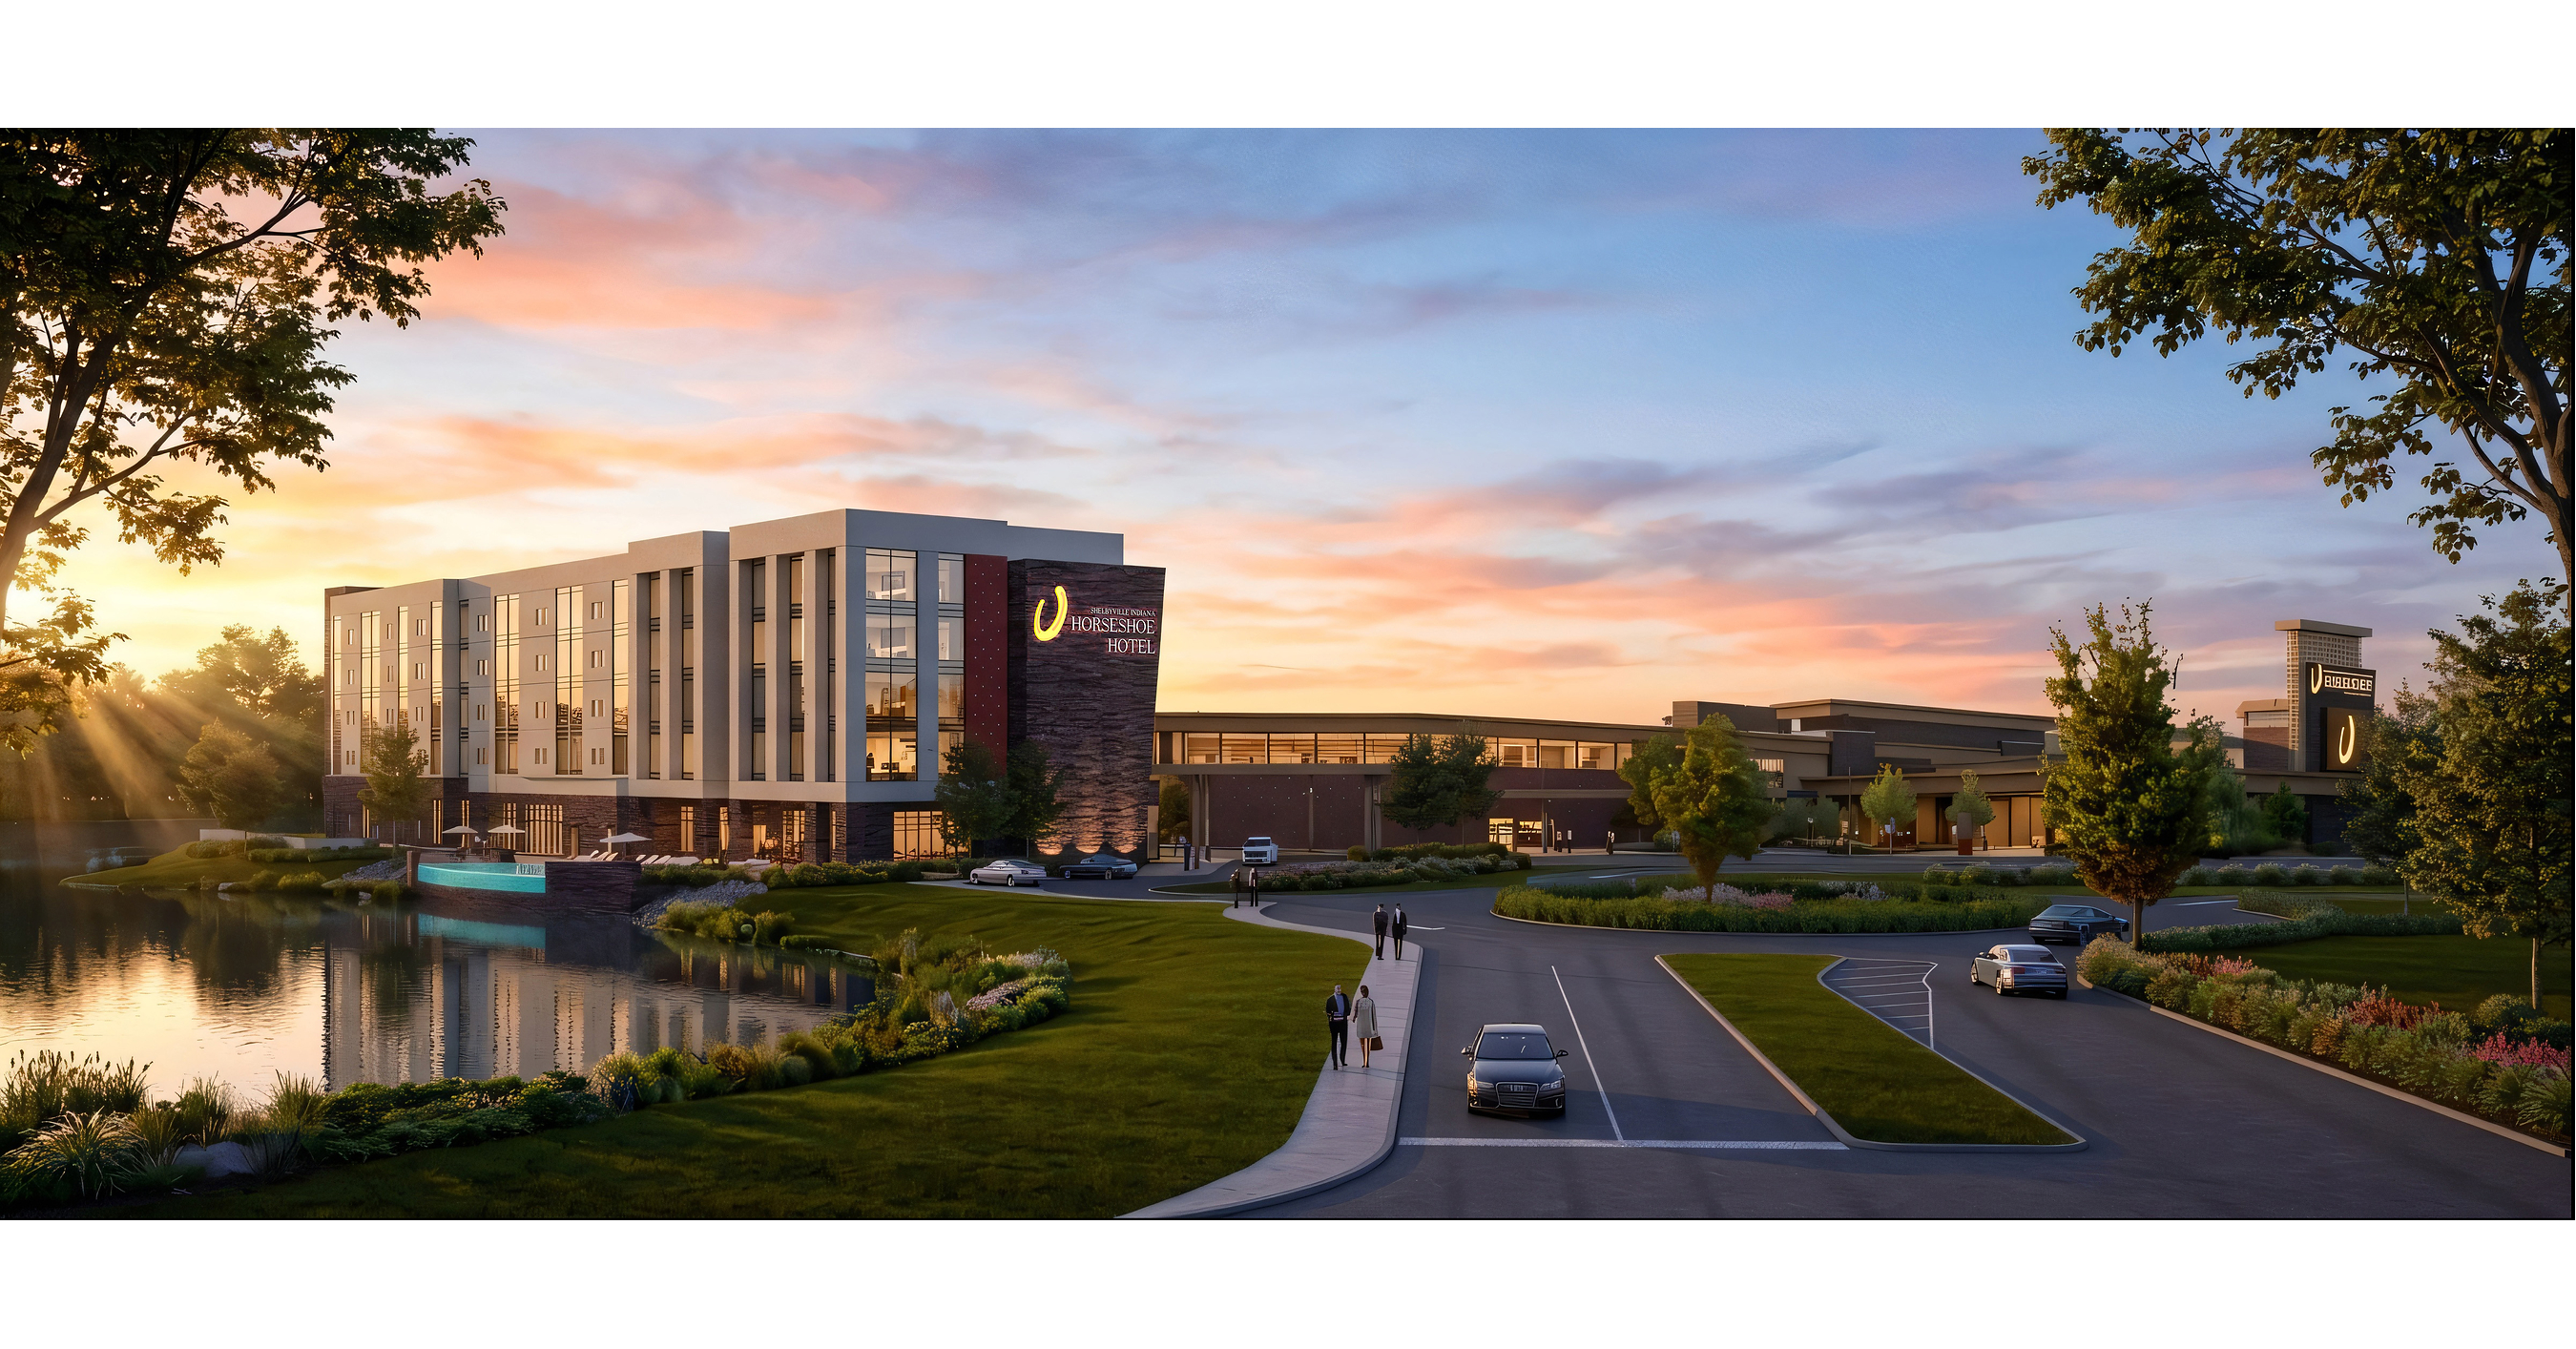
HCW plans to break ground in fall 2026 on a 140-room, five-story, 109,324-square-foot Tapestry Collection by Hilton hotel adjacent to Caesars Entertainment's Horseshoe Indianapolis. The property, scheduled to open in spring 2028, will add lodging, a restaurant and bar, infinity pool, fitness center and 1,648 square feet of meeting space to support casino, racing, group and leisure visitors. The development is a positive incremental expansion for the Shelbyville destination, but no project cost, financing terms or expected financial contribution was disclosed.
Analysis
The financial effect on CZR is likely immaterial at the consolidated level: 140 rooms cannot move system EBITDA meaningfully, and the asset appears developer-owned rather than a Caesars balance-sheet commitment. The relevant signal is operational—incremental overnight capacity can lift casino visitation frequency, event capture and non-gaming spend, but only if the property meaningfully converts drive-in customers into multi-night stays rather than displacing existing regional hotel supply. The first measurable catalyst is not groundbreaking but 2027 disclosure of commercial terms, including any casino cross-marketing, room-block commitments, or revenue participation.
HLT gains a capital-light distribution and loyalty node with negligible near-term fee impact. The more useful read-through is that Hilton's soft-brand model remains attractive for independent developers seeking reservation-system reach without full-brand standardization; this is supportive at the margin for unit-growth durability, not a reason to revise earnings. For HCW, construction cost inflation, financing availability, and local labor scarcity are more material than demand assumptions given the long pre-opening period.
Contrarian view: local gaming-hotel additions often generate less incremental gaming revenue than modeled because regional casino customers are predominantly same-day visitors and room demand spikes around discrete racing/events. If the hotel is priced at a premium to Indianapolis-area alternatives, occupancy may rely on costly promotional packages, limiting any downstream casino-margin benefit. No standalone trade is warranted from this announcement; use it as a 2027 operating-data watch item rather than a 2026 earnings catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- Maintain neutral CZR on this development; do not underwrite EBITDA upside until management quantifies lodging economics or shows sustained growth in Horseshoe Indianapolis hotel-package, visitation, and non-gaming revenue metrics during 2027-28.
- Maintain existing HLT exposure rather than add on the announcement. Reassess only if Tapestry/soft-brand net unit growth and fee-revenue guidance improve at quarterly results; a single 140-room opening has no meaningful valuation implication.
- Create a 2027 diligence alert for project financing, construction progress, and room-rate positioning. Delays beyond spring 2028 or a material local supply increase would falsify even the modest destination-capture thesis.
- For gaming exposure, prefer CZR only through a broader fundamental catalyst—deleveraging, Las Vegas demand stabilization, or improved digital profitability—rather than this regional lodging project; risk is that promotional spend rises without incremental casino win.
More News
- Canaccord says NFL Week 1 results modestly unfavorable for operators
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- Saudi coalition says Houthi drone destroyed near Mecca
- Iran war increasing inflation, straining US munitions: congressional report
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks