
Bitmine Immersion Technologies (BMNR) gibt bekannt, dass der ETH-Bestand 6,04 Millionen Token erreicht hat und sich der Gesamtbestand an Kryptowährungen sowie an Barmitteln und marktfähigen Wertpapieren auf 15,1 Milliarden US-Dollar beläuft
Source: PR Newswire
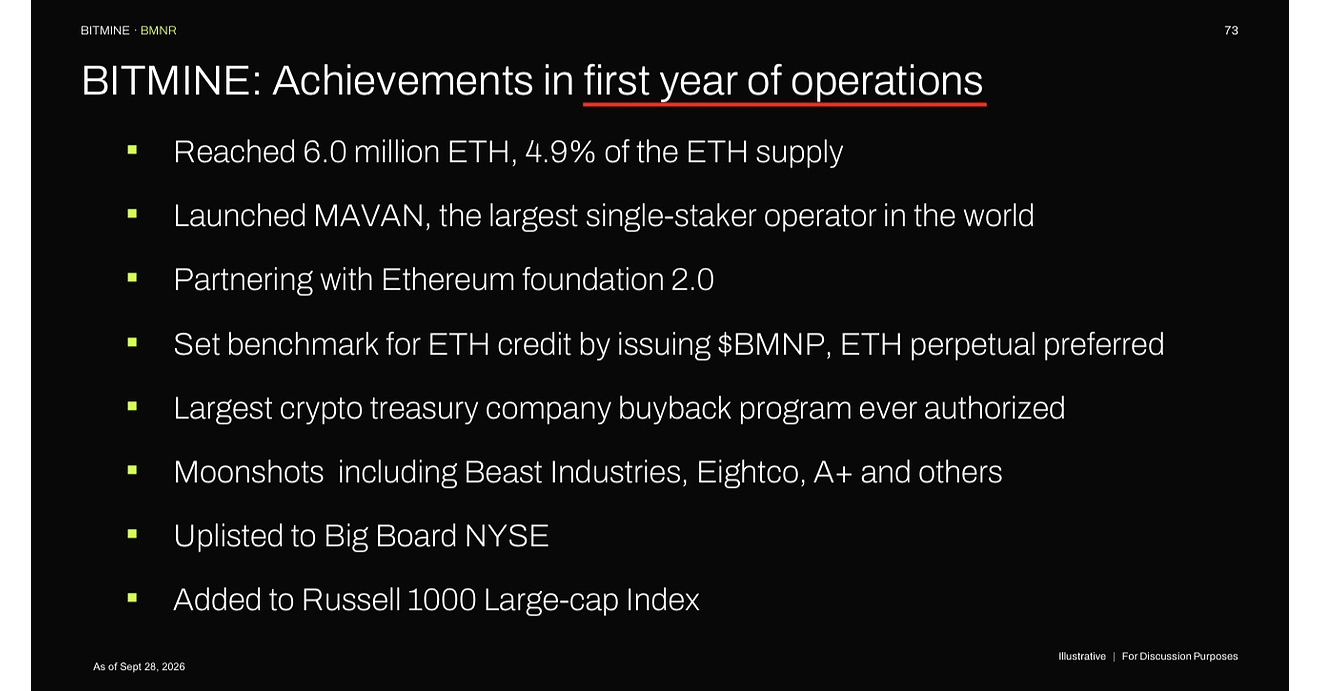
Bitmine reported total crypto, cash, marketable securities and “Moonshot” holdings of $15.1 billion as of October 18, including 6,041,481 ETH valued at $2,365 per token—about 4.9% of ETH’s 122.1 million-token supply. The company said 5,067,309 ETH, valued at $12 billion, was staked; Chairman Tom Lee cited projected annual staking rewards of about $309 million at current scale, or $369 million if all ETH were staked under the stated assumptions. Lee also said investor risk appetite had weakened amid AI-related concerns, geopolitical tensions, election uncertainty and rising bond yields, while expressing optimism about crypto’s longer-term outlook.
Analysis
The key exposure is not simply ETH beta: BMNR is turning a concentrated, volatile treasury into an equity whose performance may also depend on its premium to marked asset value, funding access and staking execution. A falling ETH price can therefore hit both NAV and the equity multiple; if the premium compresses at the same time, BMNR may underperform spot ETH materially. Verify share count, debt and preferred-stock claims, and the current premium/discount to independently marked NAV before treating the stock as a proxy for ETH.
Near term, the chairman’s bullish framing is not a catalyst by itself. In a risk-off tape, renewed ETH purchases may support sentiment but also raise questions about capital sources and dilution. Over 1–3 months, track ETH price, BMNR’s NAV premium, actual net staking yield, and any financing or custody disclosures. Over 6–18 months, institutional MAVAN growth could create a fee business less dependent on treasury appreciation, but the release does not establish external client traction or economics. Concentration of this scale also creates second-order protocol, custody and liquidity risks: operational disruption, slashing, a staking exit bottleneck, or forced sales could affect confidence in ETH as well as BMNR.
Contrarian view: the headline asset value can obscure equity-level downside convexity. Conversely, if the market increasingly values verified staking cash flows rather than token accumulation, BMNR could earn a more durable infrastructure multiple—but that requires evidence of third-party revenues. ORBS exposure is too small relative to the stated portfolio to support a standalone thesis from this disclosure.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Ticker Sentiment
Key Decisions for Investors
- Do not chase BMNR solely on the accumulation announcement. For any long, first reconcile diluted equity value, debt/preferred claims and independently priced liquid assets to calculate the equity’s NAV premium; the release does not provide enough information to do that.
- Set a relative-value alert: consider short BMNR versus long ETH only if BMNR’s premium to NAV is demonstrably elevated and widening while ETH itself remains stable. The thesis is premium compression, not a bearish ETH call; exit if the premium narrows or verified staking revenues justify the valuation.
- Monitor the next 1–3 months for actual staking yield net of fees, custody/validator concentration, external MAVAN customers, and capital-raising or dilution disclosures. A lower realized yield, slashing/outage, or equity issuance would weaken the accumulation thesis.
- Falsify the bullish case if ETH weakness combines with a sharp BMNR NAV-premium contraction, or if reported staking income materially trails the implied run rate. A sustained premium supported by audited third-party staking revenue would instead argue against the relative-value short.
More News
- Strategy buys another $22 million of Bitcoin, increases planned share buybacks
- Recent crypto IPOs have been a wipeout for most investors. Will the next wave be better?
- Strategy buys bitcoin and repurchases preferred shares in weekly update
- BlackRock, GIC among investors chasing Indian telecom major Jio's IPO as anchor bids top $26 billion
- Nscale, Anthropic Eye $45 Billion Cloud Deal as AI Trade Rebounds
- Asia stocks slump as AI jitters hammer Korean chipmakers ahead of tech earnings
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for CFA Charterholders: An Evidence Standard
- Weekly Update: Unstructured Data Search, Ask AI, and Advanced Futures Data