
Report maps China's emissions trajectory
Source: PR Newswire
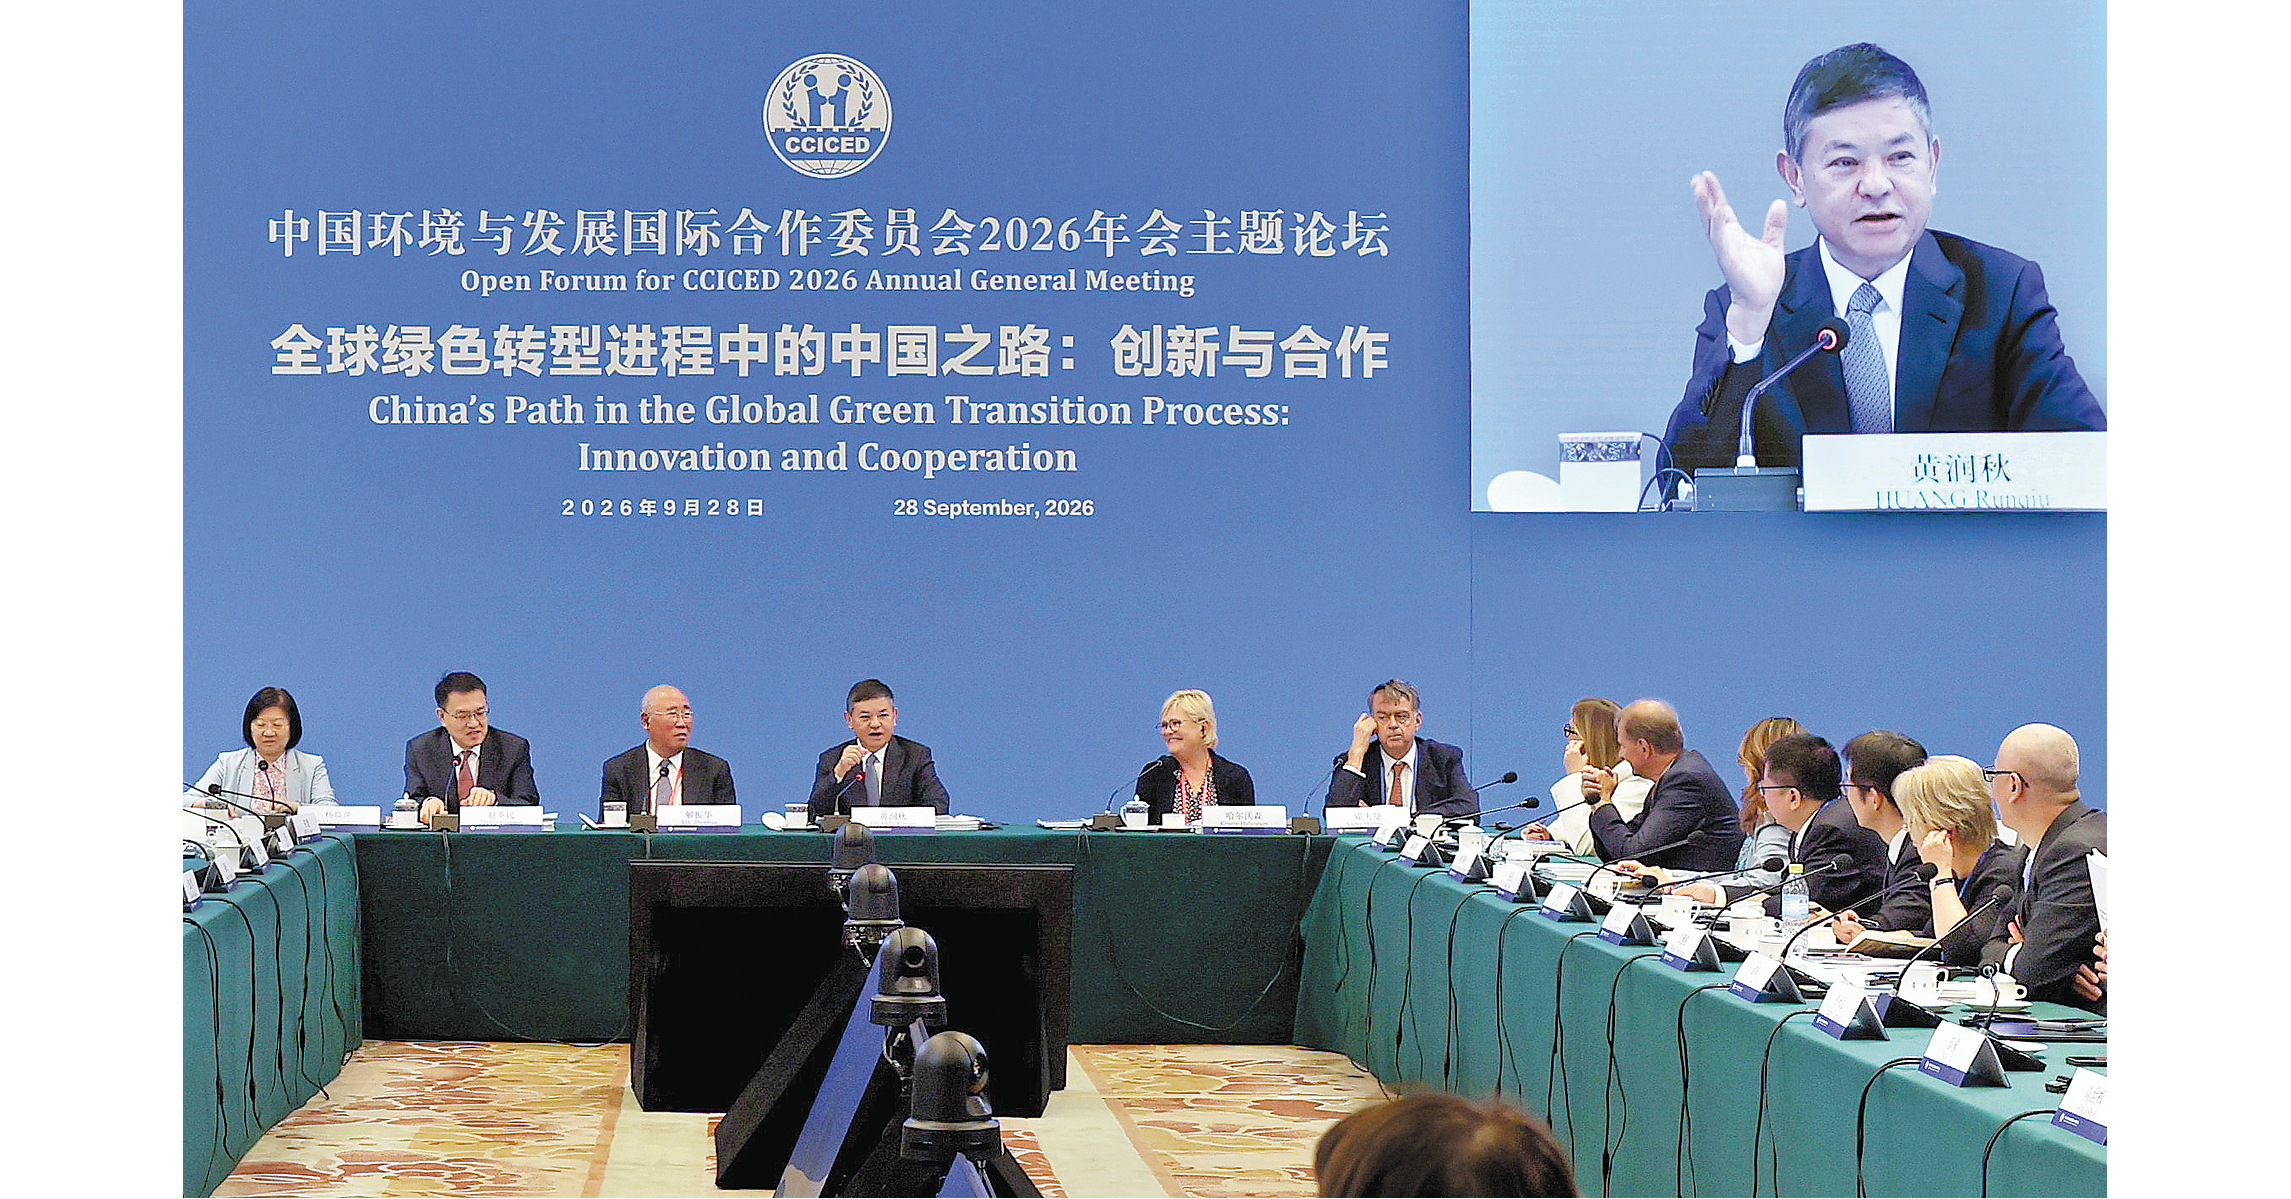
China's CO2 emissions are projected to peak in 2027-29 and decline by more than 10% from that peak by 2035, while its 2035 economy-wide greenhouse-gas reduction target is 7%-10% below peak levels. Carbon-emissions intensity had already fallen more than 51% from 2005 levels by 2024, with coal's energy share declining to 53.2% from 56.8% in 2020 and nonfossil fuels rising to 19.8% from 15.9%. The report identifies rising decarbonization costs, grid and storage constraints, costly hydrogen and carbon-capture technologies, critical-mineral risks, and transition impacts on coal, steel and cement employment as key obstacles; green industries could represent roughly 20% of GDP by 2035.
Analysis
This is not yet a binding policy catalyst; the investable signal is that China’s next planning cycle is likely to shift capital intensity from renewable generation toward grid flexibility, storage, transmission and industrial electrification. Incremental solar and wind capacity without dispatchability increasingly depresses project returns through curtailment and weak capture prices, favoring suppliers with grid-integration exposure such as CATL (300750.SZ), Sungrow (300274.SZ) and NARI Technology (600406.SS) over commodity-like module manufacturers. The first confirmation point is the final 15th Five-Year Plan implementation detail, particularly capacity-market, storage-remuneration and transmission-spending provisions, over the next 1-3 months.
The less obvious near-term winner is thermal-power flexibility rather than coal demand itself. A grid built around intermittent generation requires dispatchable reserve capacity; absent credible pricing for capacity and ancillary services, utilities will underinvest and renewable curtailment becomes a political and economic constraint. That creates a 6-18 month upside case for efficient Chinese generators and grid equipment, while leaving pure coal miners exposed to a structurally deteriorating demand mix once power-sector flexibility is adequately funded.
The industrial-decarbonization timeline argues against pricing a rapid earnings inflection in hydrogen, carbon capture, or green-steel technologies. These remain dependent on subsidies, low-cost clean power and carbon-market tightening; companies marketing demonstration projects should not receive commercial-scale multiples without contracted offtake. Conversely, rising physical-climate adaptation needs support a separate infrastructure theme—grid hardening, flood control and utility modernization—that is less dependent on carbon-price economics.
GTH has no identifiable operating linkage to Chinese power, climate finance, or energy-transition supply chains; this information does not alter its earnings outlook. Consensus may overreact to renewable deployment headlines, while the durable bottleneck is monetizable system reliability rather than generation volume.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No action in GTH: maintain neutral exposure unless management identifies a direct China energy-transition revenue stream; the article provides no fundamental catalyst for the ticker.
- Watch for 15th Five-Year Plan grid, storage and capacity-payment rules over the next 1-3 months; on explicit funding mechanisms, favor a basket long CATL (300750.SZ), Sungrow (300274.SZ) and NARI Technology (600406.SS) versus a short China solar-manufacturing proxy such as KGRN. Thesis risk: subsidy support remains generation-centric or storage procurement drives uneconomic price competition.
- For liquid U.S. implementation, use a small long LIT position only after Chinese storage-policy confirmation rather than buying on this report; target a 6-12 month horizon and limit risk with a 10-12% stop, as LIT remains exposed to lithium-price deflation and broad EV-demand weakness.
- Avoid initiating long positions in hydrogen/CCUS developers solely on planning rhetoric. Upgrade only when project-level offtake, regulated returns, or carbon-market price floors are disclosed; failure to secure these within the 2026-30 plan period would likely compress long-duration valuation premiums.
More News
- UK Prime Minister Burnham says Iran 'played a part' in British air base incident
- South Korea’s exports hit record high on AI boom
- In photos: China's Xi hardens Taiwan warning as country celebrates week-long National Day holiday
- Asian stocks dip, bonds in focus after torrid September
- September Ends on a Grim Market Note: Evening Briefing Americas
- RAM supply set to worsen, says Micron, as CEO celebrates ‘much higher’ prices
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How the 2026 Milan-Cortina Winter Olympics Will Reshape Company Revenues and Stock Performance
- Can Hedge Funds Use ChatGPT? A Control Framework