
European Approval for Production Organisation Dutch Flying Car Company PAL-V
Source: PR Newswire
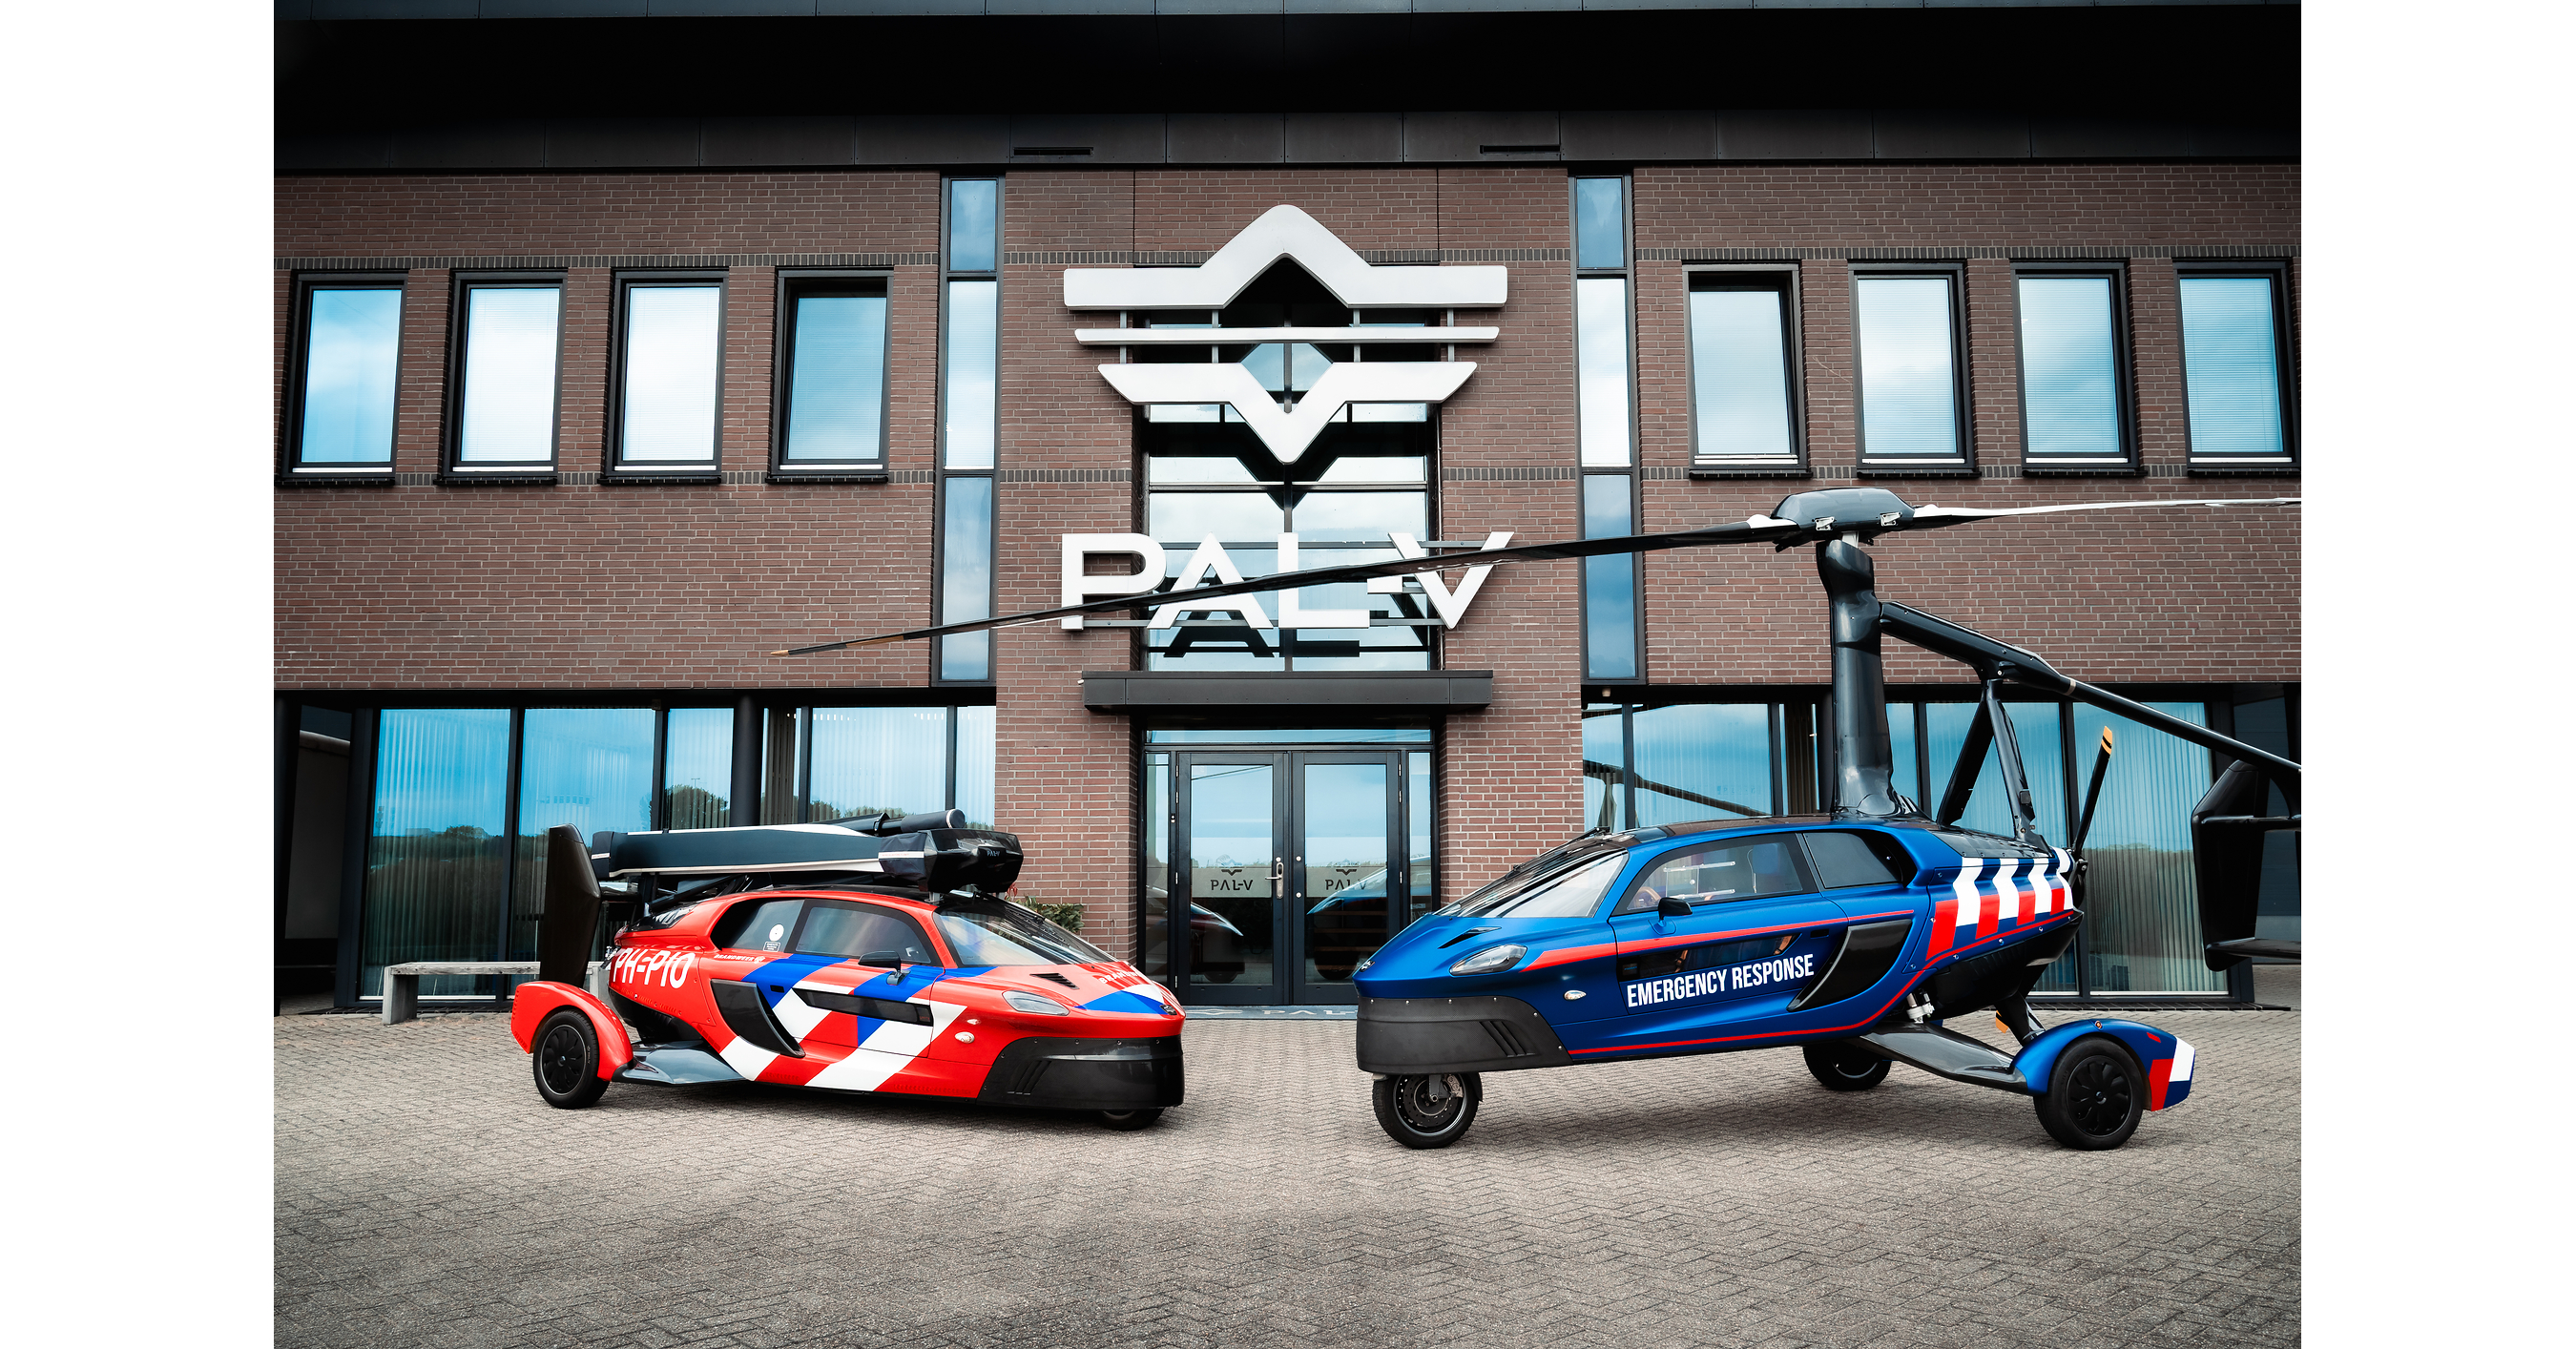
PAL-V received European Aviation Safety Agency Production Organisation Approval, allowing it to manufacture aviation products under EASA regulations alongside its existing automotive production approvals. The Dutch flying-car company said it is the first FlyDrive advanced-air-mobility company to secure the approval and has reservations sufficient to fill its first three years of production. The certification removes a key manufacturing-regulatory hurdle, though PAL-V remains a private company and no production, revenue, or delivery figures were disclosed.
Analysis
This is a certification-process signal rather than an investable earnings event: PAL-V is private, and production authorization does not establish type certification, delivered-unit economics, insurance availability, customer financing, or scalable supplier throughput. The claimed reservation coverage is particularly low-quality as a demand indicator absent disclosed deposits, cancellation terms, production rate, and conversion history. Public AAM valuations should not re-rate on this announcement alone.
The more relevant read-through is regulatory optionality for European aerospace suppliers. If PAL-V converts into deliveries over the next 12-24 months, EASA-compliant avionics, propulsion, composite, and certification-service providers gain a small but strategically valuable reference program; listed proxies include Safran (SAF.PA), Thales (HO.PA), Hexcel (HXL), and Dassault Systèmes (DSY.PA). However, a roadable-aircraft architecture is unlikely to validate the unit economics of airport-to-airport eVTOL operators such as Joby (JOBY), Archer (ACHR), or Lilium-related assets: vehicle weight, dual-regulatory requirements, and limited payload create a different cost curve.
Contrarian view: the first production approval may prove a competitive moat only in a niche, not evidence of mass-market fly-drive adoption. Certification expertise has option value, but the bottleneck shifts from regulators to operating rules, hangar/road infrastructure, pilot training, liability insurance, and affordability. The key falsifier is independently disclosed firm-order conversion and a credible serial-production rate with gross-margin targets; without those, this remains a private-company milestone with no actionable public-market transmission.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.58
Key Decisions for Investors
- No directional trade in JOBY, ACHR, or broad AAM ETFs on this release; treat any sympathy rally as a fade candidate only if it exceeds 5-10% without accompanying FAA/EASA certification or firm-order evidence.
- Create a 12-month watchlist for SAF.PA, HO.PA, HXL, and DSY.PA rather than initiating positions. Upgrade only if PAL-V identifies contracted suppliers, disclosed production cadence, and paid-order conversion; supplier revenue exposure is currently unknowable.
- For existing speculative AAM longs, maintain exposure only through binary-event sizing and use PAL-V as evidence that production-system certification can precede commercial scale by years—not as validation of near-term revenue forecasts. Reassess after next FAA/EASA type-certification milestones and quarterly cash-burn updates.
- Monitor European aviation insurance pricing, EASA operating-rule developments, and PAL-V delivery disclosures over the next 6-18 months. A first commercial delivery with disclosed unit price, deposit conversion, and service economics would be the threshold for a more constructive European aerospace-supply-chain thesis.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- U.S. oil holds above $100, Brent at five-month high as Iran says it’s prepared for warfare
- PG&E’s CEO says AI is ‘the best thing that could’ve ever happened to the grid’
- The mobile ambitions of SpaceX see telecom stocks get hit again. What the latest developments mean.
- Defense giant Saab sees orders triple after Gripen fighter jet deal with Ukraine
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Sector Analysis, Improvements on Research Data, and Performance Enhancements
- Choosing an AI Copilot for Equity Research