
HiTHIUM supera los 200 GWh en envíos
Source: PR Newswire
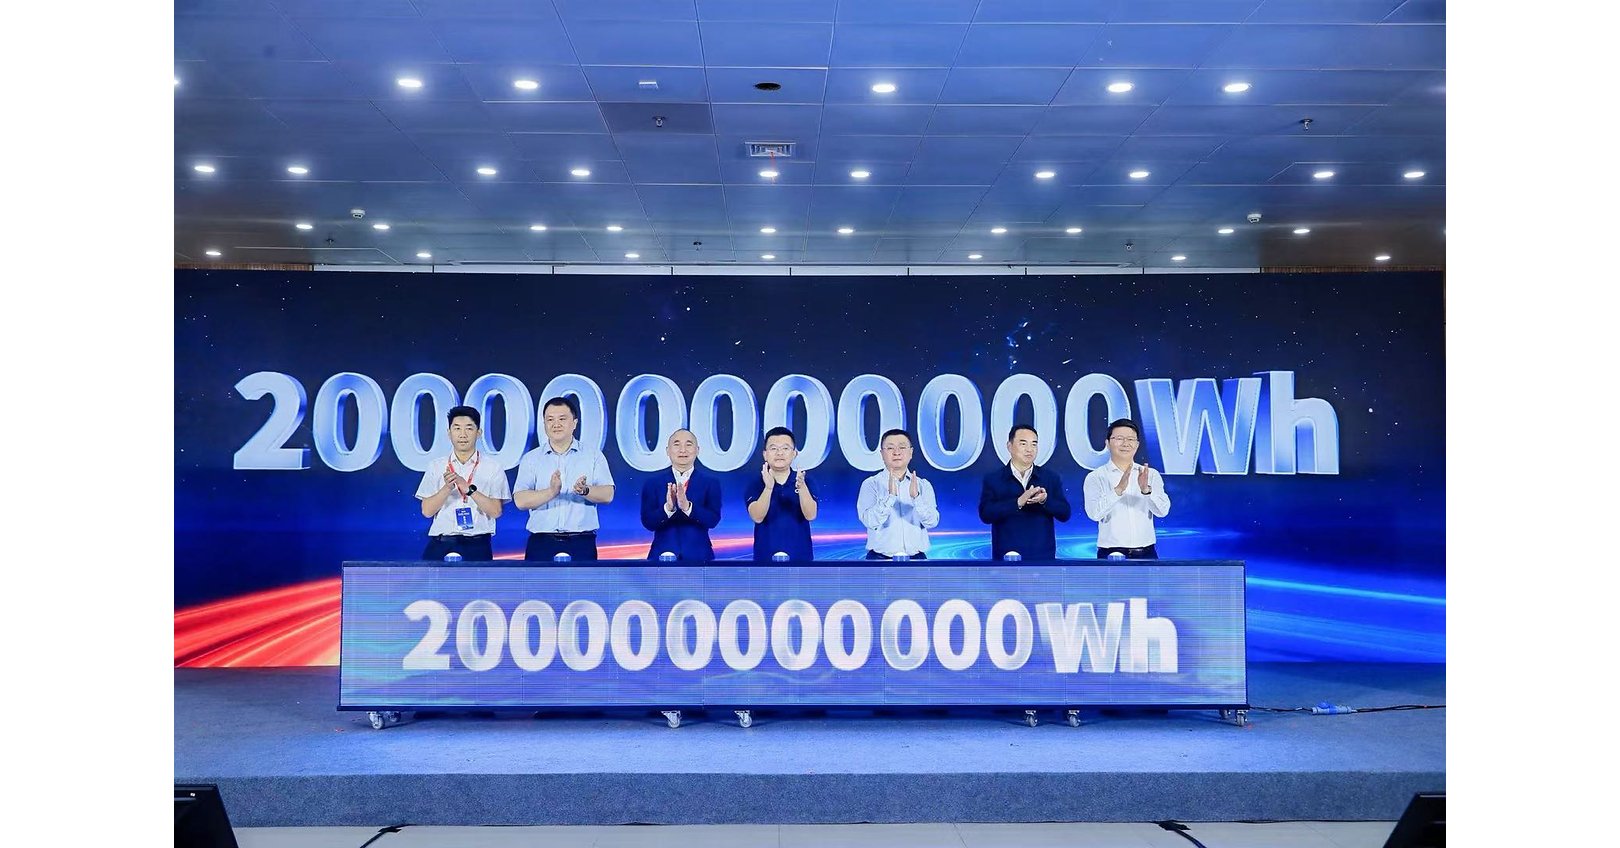
HiTHIUM informó que sus envíos acumulados de almacenamiento de energía alcanzaron 200 GWh el 15 de octubre de 2026, frente a más de 100 GWh en agosto de 2025. La empresa señaló que subió del quinto puesto mundial en 2023 al segundo en 2025 y en el primer semestre de 2026. Planea ampliar su tecnología de almacenamiento de larga duración, su fabricación y distribución global, y alcanzar los próximos 100 GWh en envíos.
Analysis
Scale is strategically relevant only if it lowers delivered system cost and converts into profitable, repeatable projects. Cumulative GWh shipped is not evidence of realized pricing, utilization, cash generation, or the economics of HiTHIUM’s LDES offering; the release does not define the shipment scope or provide those measures. The near-term read-through is therefore competitive, not an earnings upgrade: greater procurement and project-delivery capability could help HiTHIUM win bids, while intensifying price pressure on cell and system suppliers. CATL, BYD, EVE Energy, and Sungrow are plausible competitors to monitor; Fluence and Tesla may face tougher pricing in some storage tenders, but exposure varies by market and project.
The contrarian point is that shipment leadership can coexist with weak returns if capacity growth outruns demand or customers capture cost savings through lower bids. A further risk is treating an LDES product launch as proof of bankable performance: field reliability, warranty terms, and project-level economics take time to establish. Over days, the announcement alone is a weak trading catalyst. Over 1–3 months, tender wins, realized pricing, and customer/project disclosures matter more; over 6–18 months, localization, utilization, and cash conversion will determine whether scale becomes an advantage. No direct HiTHIUM security is identified in the supplied data.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.55
Key Decisions for Investors
- No standalone trade on the announcement. Treat it as a competitive signal, not a confirmed earnings inflection; avoid inferring revenue or margins from cumulative GWh.
- Set an alert for the next 1–3 months: verify shipment definitions, project awards, realized pricing, and whether LDES deployments are operating projects rather than product announcements. Reassess only if independently corroborated data show wins without material price concessions.
- Monitor CATL, BYD, EVE Energy, and Sungrow for evidence of bid-price or market-share pressure, and Fluence and Tesla for tender commentary. A relative-value position would require confirmation that comparable regional/project exposure is translating into guidance or margin changes.
- Falsify the scale-to-advantage thesis if subsequent disclosures show falling realized prices, weak factory utilization, delayed projects, or no improvement in cash conversion; validate it only with repeat orders, field-performance evidence, and sustained project economics.
More News
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Dow falls 189 points as AI stocks slide and oil prices surge
- Wall Street Anxiety Spreads as AI Rout Meets $110 Oil Shock
- All the news about the iPhone Duo
- The Tesla Roadster should go into production in 2028, but don't get your hopes up