
Stryker showcases Foot & Ankle innovation at AOFAS 2026 with Prophecy® Surgical Planning for Incompass™ and Hoffmann® LRF smartHEX™
Source: PR Newswire
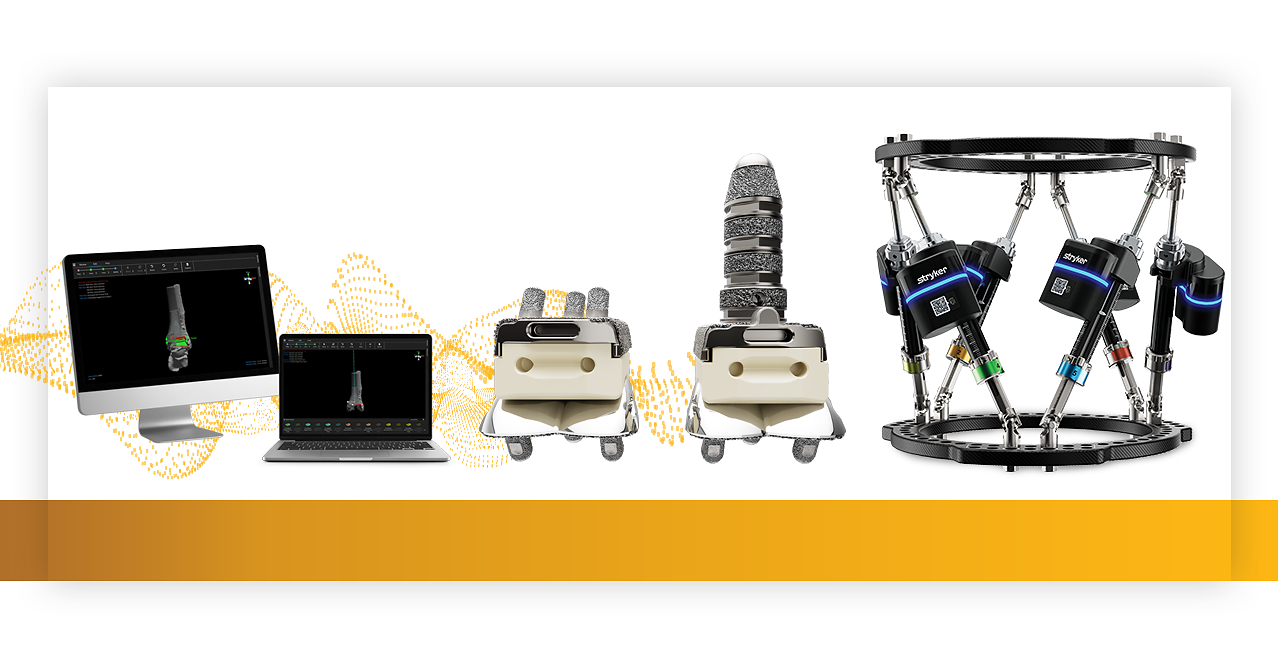
Stryker launched Prophecy Surgical Planning for its Incompass Total Ankle System and introduced the Hoffmann LRF smartHEX limb-reconstruction platform at the 2026 AOFAS meeting. Prophecy, which has supported more than 100,000 ankle cases over 14 years, adds patient-specific 3D planning and two fixation options to Incompass, while smartHEX adds expanded frame components, mobile patient guidance and updated planning software. The launches strengthen Stryker's connected-care and foot-and-ankle product offering, but no financial guidance or revenue impact was disclosed.
Analysis
This is strategically supportive of SYK's Orthopaedics moat but immaterial to near-term consolidated estimates absent evidence of procedure pull-through. The value is not the planning feature itself; it is the potential to raise switching costs by embedding surgeon workflow, implant selection and post-operative compliance into one ecosystem. If adoption improves conversion to Incompass or reduces revision/operating-room variability, SYK can defend pricing and modestly expand mix in a category where surgeon preference and training create durable share gains.
The most relevant competitive read-through is negative for smaller, implant-only foot-and-ankle vendors that lack integrated planning and digital follow-up capabilities; however, the addressable total-ankle market remains niche relative to SYK's group revenue. Zimmer Biomet (ZBH), Enovis (ENOV), and Johnson & Johnson's DePuy franchise face a longer-term risk that SYK converts digital planning into a broader account-level contracting advantage, especially at ambulatory surgery centers. Over the next 6-18 months, verify this through disclosed Incompass utilization, Foot & Ankle growth versus the Orthopaedics segment, and any evidence of improved gross margin rather than management's adoption claims.
No material catalyst is likely in the next several days: this is conference-led product marketing, not an independently validated clinical or reimbursement event. Consensus may underappreciate the recurring software/data opportunity, but it may also overstate it if hospitals view planning as a bundled, non-monetized sales tool. The thesis is falsified if Orthopaedics organic growth fails to outpace peers over two consecutive quarters, or if selling investment rises without an accompanying mix/margin benefit.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No standalone event trade in SYK; retain/add only on broader medtech weakness, with the product launch treated as a 6-18 month qualitative support rather than an earnings-revision catalyst.
- Watch SYK versus ZBH and ENOV over the next 2-3 earnings cycles: initiate a long SYK / short ZBH pair only if SYK shows Foot & Ankle or Orthopaedics growth acceleration of at least 200 bps versus ZBH while maintaining gross margin. Exit if SYK's segment growth premium does not emerge after two reports.
- Set an earnings-call watch item for Incompass conversion, planning attach rates, ASC adoption, and any incremental software/service revenue disclosure. Without those KPIs, do not underwrite multiple expansion from the connected-care narrative.
- For existing SYK longs, reassess if incremental Orthopaedics selling expense accelerates while segment margin contracts by more than 50 bps year-over-year; that would indicate digital workflow is functioning as a costly commercial tool rather than a pricing or share lever.
More News
- US official says upcoming spectrum auctions could generate more than $100 billion
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- AI Buildout Hits Inflation as Fed Hikes Rates
- OpenAI discloses six more instances of ’concerning’ AI model behavior
- The Competition's Response to Tesla Robotaxi Day
- Snap tries to bring AR glasses to enterprise market, partnering with Nvidia, AWS and Salesforce