
Angels on Call Homecare Named 2026 Best of Home Care Employer of Choice, Outperforming National Workforce Benchmarks
Source: PR Newswire
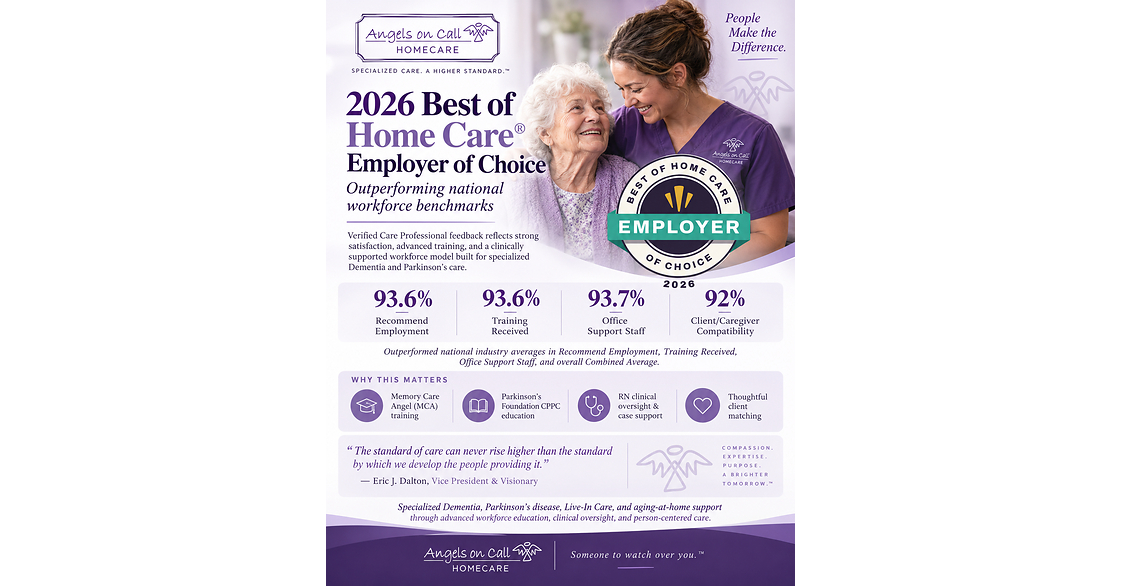
Angels on Call Homecare was named a 2026 Best of Home Care Employer of Choice, reporting Care Professional satisfaction scores of 93.6% for recommending employment and training received, 93.7% for office support, and 92.0% for client-caregiver compatibility. The company said its results exceeded national industry averages and highlighted specialized dementia and Parkinson's training, RN case-manager oversight, and dual accreditations. The award is positive validation of workforce quality but is unlikely to have material public-market impact.
Analysis
This is privately held, localized-provider marketing rather than a public-company fundamental catalyst; it does not independently establish pricing power, utilization gains, or a material change in labor costs. The relevant public-market read-through is modestly favorable for home-based care operators if specialized training improves caregiver retention, because turnover is a principal driver of recruiting expense, unfilled hours, and wage inflation. However, a higher-acuity workforce model can initially dilute margins unless reimbursement rates or private-pay mix rise faster than training, RN oversight, and retention investments.
Over 6-18 months, aging-in-place demand and acuity migration from institutional settings remain structurally supportive for diversified home-health platforms such as Elevance Health (ELV) and UnitedHealth (UNH) through Medicare Advantage benefit design, as well as post-acute operators with home-health exposure such as Encompass Health (EHC). The non-obvious constraint is reimbursement: specialized dementia and Parkinson's care creates customer value, but traditional home-care reimbursement often does not fully compensate clinical differentiation. Scale operators with payer contracts, data on avoided admissions, and capacity to convert specialized services into MA supplemental benefits should gain share; fragmented agencies may simply absorb higher labor costs.
No near-term trade is warranted from this release. A more investable signal would be evidence that MA plans expand in-home support reimbursement, states improve Medicaid home- and community-based-services funding, or public operators report lower turnover and improved contribution margins without wage pressure. The thesis is falsified if labor-cost growth remains above reimbursement growth, or if state budget pressure slows HCBS rate increases over the next two quarters.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No action on the release itself: treat it as non-material private-company publicity, not confirmation of sector-wide earnings upside.
- Place ELV and UNH on a 1-3 month policy and earnings watchlist; consider a long only if management identifies measurable growth in home-based supplemental benefits or reduced medical-cost trend from avoided institutional utilization. Key risk: MA rate/reimbursement pressure can outweigh care-management savings.
- Monitor EHC quarterly for home-health volume, labor-cost, and margin commentary; a positive setup requires sequential labor stabilization plus maintained guidance. Avoid adding if clinician compensation and contract labor continue to outpace revenue per visit.
- For a structural aging-in-place expression, prefer a diversified long basket of ELV/UNH over pure-play fragmented home-care exposure over 6-18 months; exit or reassess if state HCBS funding or MA benefit funding is curtailed.
More News
- What investors need to know about Alphabet's stock-busting earnings report
- Our next steps for Alphabet stock after earnings disappoint at nearly every turn
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- Fortinet’s stock is taking a dive after earnings. Here’s why.
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns
- Microsoft's Big Bets on AI Start to Pay Off