
Arrow Provides Operational and Mid Year 2026 Reserves Update
Source: feeds.newsfilecorp.com
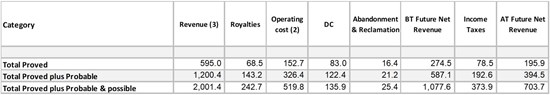
Arrow Exploration's mid-year 2026 2P reserves increased 82% to 21.4 MMboe, while 1P reserves rose 110% to 11.4 MMboe, driven by the Icaco discovery, Mateguafa development and the Thorsby acquisition. Before-tax NPV-10 increased to $410 million for 2P reserves and $193 million for 1P reserves, versus $244.5 million and $95.9 million at year-end 2025, respectively. Corporate output exceeds 6,000 boe/d, with further growth expected as Icaco-7 through Icaco-10 are brought online; however, higher-category Tapir reserves depend on regulatory approval of license extensions beyond February 2028.
Analysis
The investable issue is not reserve scale but conversion quality. AXL's value uplift is increasingly concentrated in undeveloped and extension-dependent barrels, so the market should apply a materially higher discount to headline NAV than to producing cash flow; the relevant near-term rerating catalyst is sustained well-level productivity and funded development execution, not another reserve booking. The Canadian acquisition also diversifies jurisdiction but introduces lower-value gas weighting and likely raises corporate decline-management capital needs versus the Colombia-led oil growth narrative.
The critical asymmetry sits with Ecopetrol (EC): its consent and the Tapir contract-extension process give it effective leverage over AXL's asset-duration and ownership certainty. A favorable regulatory/partner outcome could collapse part of AXL's political-risk discount within 1-3 months, while delay would impair the economic basis for probable/possible volumes and could force a sharp NAV haircut despite unchanged near-term production. EC itself is too large for this to be a meaningful earnings catalyst; its exposure is optional strategic upside rather than a trade driver.
Consensus may over-credit the reported recycle and replacement ratios because acquisition-added reserves dominate the period and reserve-engineering price decks embed a supportive forward commodity environment. The more contrarian positive is that successful pad development can lower unit infrastructure and water-handling costs, making incremental Colombian barrels more valuable than static NPV suggests; this requires evidence in realized operating costs and decline curves over the next two quarterly updates. Given AIM/TSXV liquidity, any long should be sized for a wide bid-ask and event-driven gaps rather than treated as a liquid E&P beta expression.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.72
Ticker Sentiment
Key Decisions for Investors
- Place AXL on a 1-3 month catalyst watch rather than initiate on the release alone; buy only after formal Tapir extension/assignment progress and two additional Icaco wells demonstrate repeatable production. Target a 25-40% rerating if those conditions reduce duration risk; exit if regulatory timing slips beyond the next reporting cycle or new-well results imply materially steeper declines.
- For existing AXL exposure, separate valuation into PDP versus undeveloped/extension-dependent inventory and cap position size to the loss scenario in which only producing and near-term developed reserves receive credit. Do not underwrite 2P/3P NAV at face value until development capex, funding sources, and contract duration are independently reconciled.
- Avoid using EC as a directional proxy for the AXL thesis: the potential benefit is immaterial to EC's consolidated earnings. Instead, monitor EC disclosures and Colombian regulatory communications as the highest-value signal for AXL's timing and ownership-risk discount.
- Use Brent downside protection for any AXL long through a modest short Brent/long put overlay over the next 3-6 months; the reserve valuation is sensitive to a supportive long-dated oil deck, while small-cap equity liquidity can amplify a commodity-driven de-rating. Reassess if Brent holds below $70/bbl or if AXL revises capital spending upward without matching production guidance.
More News
- From Yanbu to Sohar: Tracking Saudi Arabia’s alternative oil routes
- Bank of England set to defy Fed’s rate-hike lead, despite rising inflation
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- Oppenheimer reiterates Salesforce stock rating after investor day
- Galliford Try launches £15m share buyback programme
- DST Global Advisors sells $109.3m in Chime Financial shares