
Orogen Royalties Enters into Agreement to Sell the Slaughterhouse Copper-Gold Project to Seabridge Gold
Source: Newswire
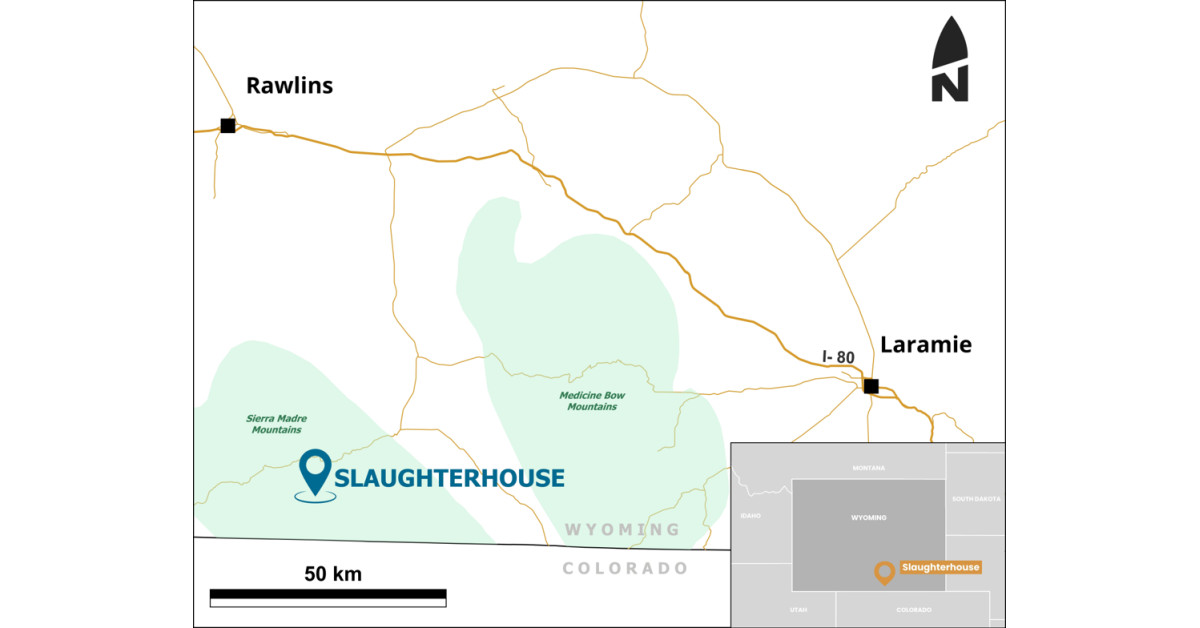
Orogen agreed to sell Seabridge Gold a 100% interest in its Slaughterhouse copper-gold project in Wyoming for US$300,000 at closing and up to US$2.55 million in milestone payments. Orogen will retain a 2.5% NSR royalty on the project, with a 0.5% buydown available for US$5 million, plus a 0.5%-1% NSR royalty on qualifying projects generated in the surrounding 2,400-square-kilometre area. Closing is subject to customary conditions; the transaction provides Orogen with milestone consideration while preserving royalty exposure to future development and discoveries.
Analysis
The transaction is more meaningful as a transfer of exploration risk than as a near-term earnings event. Seabridge Gold (SEA) acquires a district-scale option while deferring most consideration until drilling, a resource estimate, and ultimately production; the cash commitment disclosed at closing is small in absolute terms, but the project still competes for exploration capital and management attention. The potential strategic payoff is asymmetric, but geological analogies and grab-sample grades do not establish continuity, scale, recoverability, or economic value. Treat the promotional comparison with South Australian deposits as a hypothesis, not a valuation input.
Orogen Royalties receives limited upfront cash and preserves royalty leverage, but the meaningful value is long-dated and contingent. The production-stage payment is an advance against royalties, not additive production proceeds. Area-of-interest royalties could create broader upside if Seabridge generates additional projects, though their scope and conditions need close review. No immediate read-through to copper prices, competing miners, or First Majestic Silver (AG), whose mention only describes an existing Orogen royalty asset.
Near term, closing is the main execution check; over 1–3 months, look for funded drill plans and evidence of systematic testing. Over 6–18 months, metres drilled and results determine whether the optionality gains substance. A failure to fund or complete drilling, weak continuity, or a resource that does not support economic follow-up would undermine the thesis. There is insufficient evidence here to infer material valuation impact for either listed company or a durable sector signal.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No event-driven position is warranted from the announcement alone; avoid treating the geological analogies or selected grab samples as evidence of a discovery with commercial scale.
- For SEA, monitor closing, exploration-budget disclosures, and actual drill execution before underwriting project value; reassess if capital allocation is redirected or the 10,000-metre milestone is delayed.
- For Orogen Royalties, value the retained royalties as contingent exploration options rather than near-term cash flow; verify the area-of-interest conditions and royalty buydown terms before assigning material value.
- Revisit the thesis on systematic drill results and any published resource estimate. A lack of continuity or no credible path to resource definition would falsify the positive exploration-option view.
More News
- Why is Domino’s Pizza Enterprises stock sliding today?
- Oil rises amid growing Mideast tensions between Iran-backed Houthis and Saudi Arabia
- South Korean carmaker Hyundai plans 'strategic' investment of $15.5 billion in India by 2032
- Applied Materials’ $5 billion AI lab aims to cut chip development time in half—and restore Silicon Valley’s edge
- Wells Fargo CFO on Earnings, Deals, Consumer Strength
- Bank of America hit with more than $1.2 billion in penalties over money-laundering violations