
ROSEWOOD HONG KONG NAMED NO.1 IN THE 50 BEST HOTELS 2026 FOR THE SECOND CONSECUTIVE YEAR
Source: PR Newswire
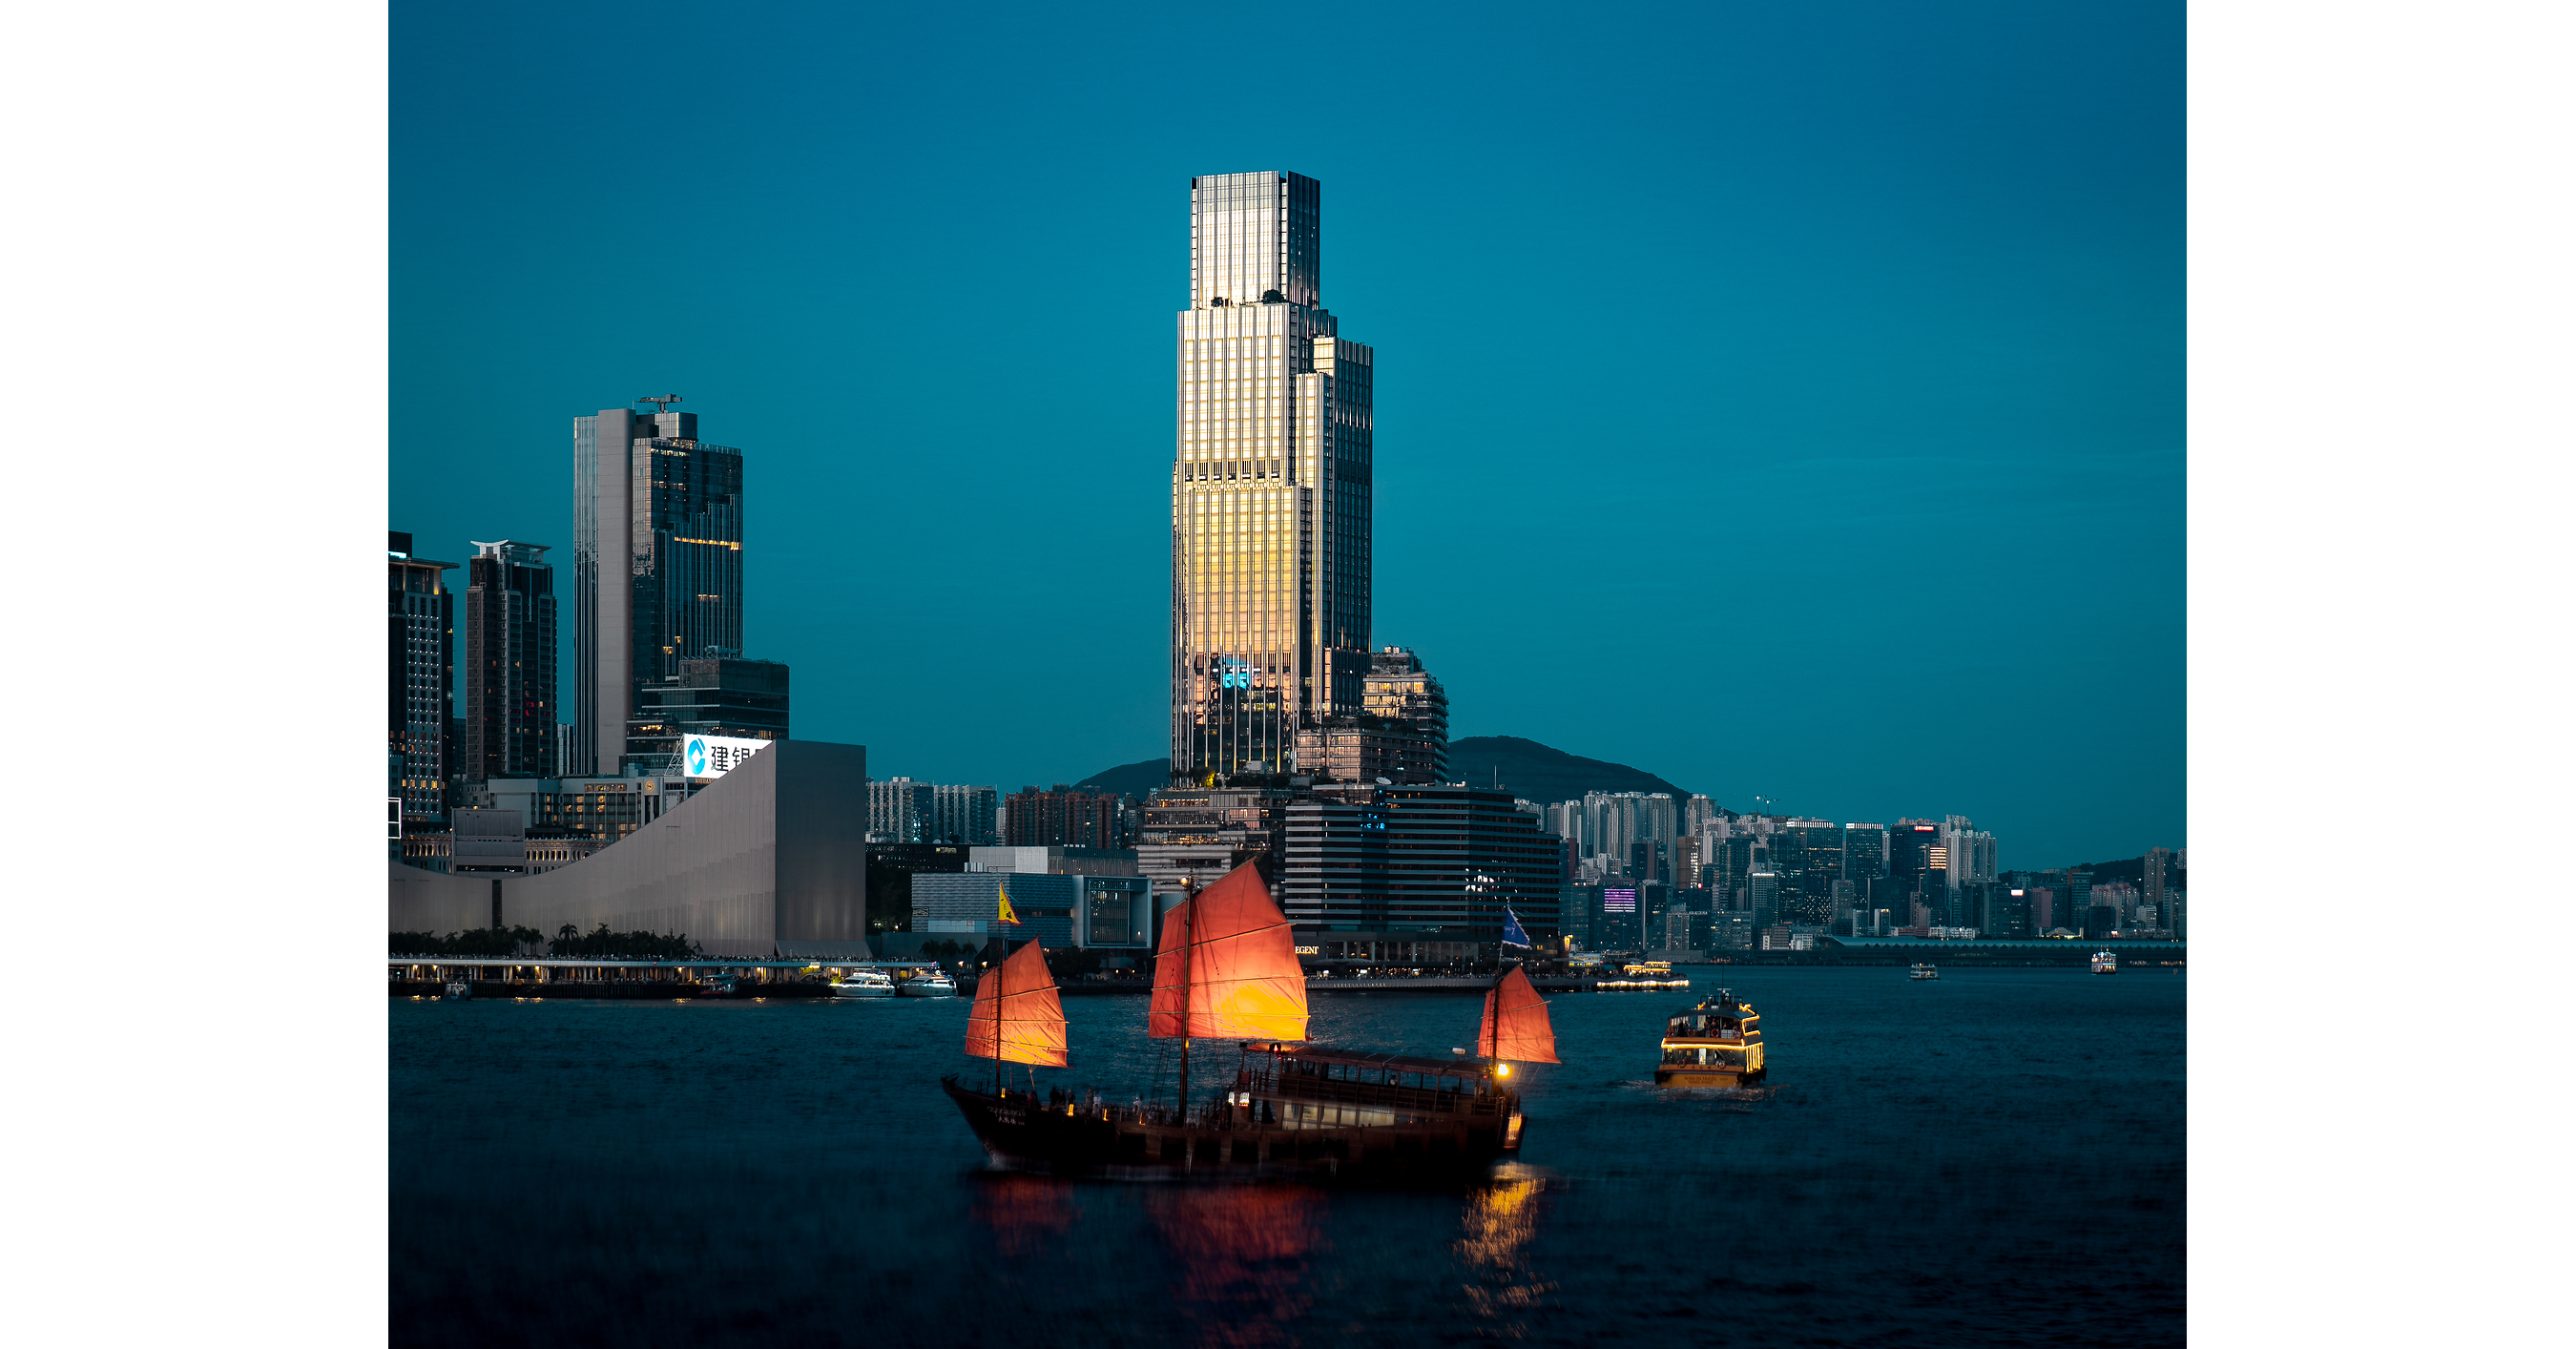
Rosewood Hong Kong was named The World's Best Hotel 2026 for the second consecutive year, ahead of Capella Bangkok (No. 2) and Four Seasons Bangkok at Chao Phraya River (No. 3). Europe led the rankings with 21 of the 50 hotels, while Asia had 18; Rosewood also received Ferrari Trento's Most Admired Hotel Group Award. The travel-industry recognition is positive for the winning hospitality brands but is unlikely to materially affect public markets.
Analysis
This is primarily earned-media validation rather than a measurable earnings catalyst. AXP has modest indirect exposure through premium-card travel engagement and its merchant network, but luxury-hotel awards do not alter billed-business or discount-rate assumptions absent evidence of incremental Fine Hotels + Resorts bookings, retention, or spend per cardmember. The likely near-term read-through is stronger at the private luxury operators and destination markets than at listed U.S. payment networks.
The second-order effect is a continued bifurcation within global lodging: independently branded, experience-led properties can sustain pricing power while standardized upscale inventory faces greater need for loyalty-program discounting. That favors asset-light luxury operators with scarce flagship properties—Marriott (MAR), Hilton (HLT), Hyatt (H)—only where their luxury pipelines are concentrated in supply-constrained gateway markets; it is not a sector-wide demand signal. RACE's award sponsorship creates brand adjacency with ultra-high-net-worth travelers, but the audience is too narrow to move vehicle volumes or consensus estimates.
Over 1-3 months, monitor premium travel indicators rather than the rankings: AXP T&E billed-business growth, luxury RevPAR relative to upper-upscale RevPAR, and international inbound booking trends into Hong Kong, Bangkok, Dubai, and Italy. A consumer slowdown or renewed Asia travel friction would expose the fragility of trophy-hotel rate growth quickly, as fixed-cost luxury properties have high incremental margin downside once occupancy softens. No standalone trade is warranted from this release.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- Maintain no incremental AXP position on this item; create an alert for AXP quarterly T&E billed-business growth falling below total billed-business growth, which would challenge the premium-travel resilience narrative over the next 1-2 quarters.
- Use upcoming MAR, HLT, and H earnings to assess luxury RevPAR versus system-wide RevPAR; consider a tactical long H / short HLT pair only if Hyatt's luxury/international RevPAR premium widens while guidance remains intact. Falsify if H's comparable RevPAR guidance is cut or the spread fails to widen after earnings.
- Do not infer a RACE demand catalyst. Treat luxury-hospitality sponsorship activity as brand-maintenance spend; revisit only if management identifies measurable gains in qualified leads, order intake, or personalization revenue.
- For macro books, watch Hong Kong and Thailand premium-hotel occupancy and ADR over the next 90 days as a high-end discretionary-demand indicator, not as confirmation of broad travel-sector strength.
More News
- Trip.com swings to Q2 loss after $763 million antitrust penalty
- Saudi-led coalition intercepts drone headed for Mecca
- Why Dave & Buster's Stock Tumbled Today
- US data centers could consume more natural gas than Germany and Japan combined by 2035
- Trump’s ‘largest deregulatory action ever’ in the power sector will keep old coal plants online longer to fuel the AI boom
- Malaysia talks to rival airlines as it monitors AirAsia's financial health, sources say