
FOTON présente l'ensemble de sa gamme de produits à Hanovre et propose un nouveau modèle en vue de l'expansion mondiale de la chaîne de valeur des véhicules utilitaires chinois
Source: PR Newswire
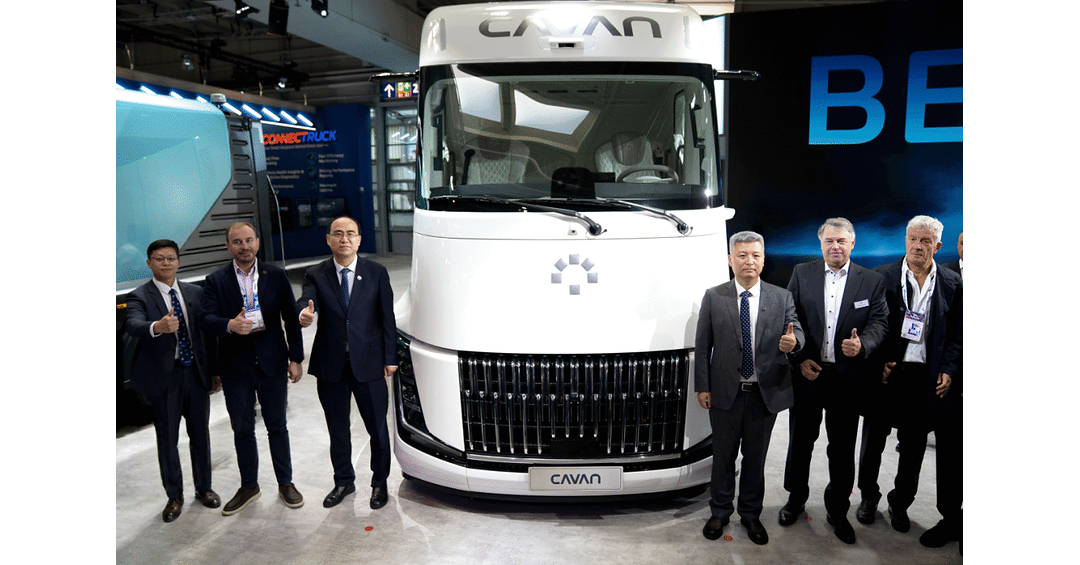
BAIC FOTON unveiled the CAVAN BEACON zero-emission intelligent heavy truck at IAA Transportation 2026, featuring over 600 km battery-electric range, more than 1,000 km hydrogen range, and megawatt charging from 20% to 80% in 18 minutes. The company marked delivery of its 13 millionth vehicle and outlined a European expansion plan spanning nearly 20 markets, more than 300 service points, a German parts hub and local assembly by 2028. FOTON targets new-energy vehicles for 50% of revenue and international sales for 40% by 2030.
Analysis
The investable read-through is competitive rather than a direct equity catalyst: European truck OEMs face a potentially more credible low-cost entrant in battery-electric medium/heavy duty vehicles, where fleet TCO—not brand loyalty—will increasingly determine share. Daimler Truck (DTG.DE), TRATON (8TRA.DE), Volvo (VOLV-B.ST) and Paccar (PCAR) have higher European service-network and residual-value advantages, but localized assembly and parts availability would erode the principal barriers protecting their aftermarket-rich margins. The greatest pressure would likely fall on entry-level and regional-haul configurations before premium long-haul fleets, where uptime history and financing ecosystems remain decisive.
The near-term financial effect is immaterial absent European homologation progress, fleet orders, disclosed pricing and credible local production economics. Over 1-3 months, watch incumbent order books and tender commentary for price concessions in BEV trucks; a shift from pilot deployments to multi-year fleet framework agreements would be the first meaningful signal. Over 6-18 months, a Chinese OEM ecosystem could compress European truck BEV pricing and force incumbents to absorb lower margins or accelerate investment, benefiting component suppliers with platform-agnostic exposure such as ABB (ABBN.SW) and charging specialists only if depot and megawatt-charging build-outs actually convert into orders.
Consensus may overestimate the disruption from headline vehicle specifications. Heavy-truck adoption is constrained less by stated range than by financing, residual values, depot-grid interconnection, service uptime, driver acceptance and hydrogen fuel economics; these are multi-year execution hurdles. Conversely, incumbents should not assume tariffs alone preserve economics: municipal fleets, closed-route logistics and price-sensitive regional operators are the segment where a subsidized Chinese product can establish a beachhead before broad long-haul penetration.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.58
Key Decisions for Investors
- No directional trade on the announcement alone: FOTON is not a listed liquid proxy and the release provides no European pricing, binding orders, capex or unit-sales guidance. Create an alert for homologation approvals, disclosed German assembly investment and fleet contracts above 100 units; these would upgrade competitive-risk relevance.
- Maintain a 6-12 month relative-value watch: long Volvo (VOLV-B.ST) / short Daimler Truck (DTG.DE) only if European BEV truck tender pricing begins to weaken. Volvo's diversified construction and services earnings offer better insulation, while DTG.DE has greater sensitivity to European truck-cycle and pricing disappointment; invalidate if DTG.DE's order intake and adjusted EBIT margin remain above guidance through the next two reporting periods.
- For portfolios already long European truck OEMs, reduce exposure to the lower-end BEV commercialization narrative through a modest hedge in TRATON (8TRA.DE), which has meaningful European commercial-vehicle exposure and faces higher risk if fleet buyers prioritize acquisition cost. Reassess the hedge if TRATON demonstrates stable service revenue growth and no deterioration in BEV gross-margin commentary.
- Watch ABBN.SW rather than chase pure-play charging names: add only after evidence of awarded megawatt/depot charging projects, as equipment suppliers monetize actual grid and charging capex irrespective of vehicle-brand share. The thesis fails if European heavy-duty charging deployment remains delayed by interconnection queues and fleet utilization stays below economic thresholds.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
- MBS and Saudi Arabia Face Crisis With Key Oil Pipeline Shut for Weeks
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Chinese investors rush into US stocks as Beijing opens wider path overseas
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More
- Alternative Data Due Diligence for Institutional Investors