
Cove Capital Investments Adds Another Asset to Its Growing Portfolio of Debt-Free Delaware Statutory Trust Offerings After Acquiring 29,000-Square-Foot Retail Property to Form Its Shreveport Opportunity 120 DST
Source: PR Newswire
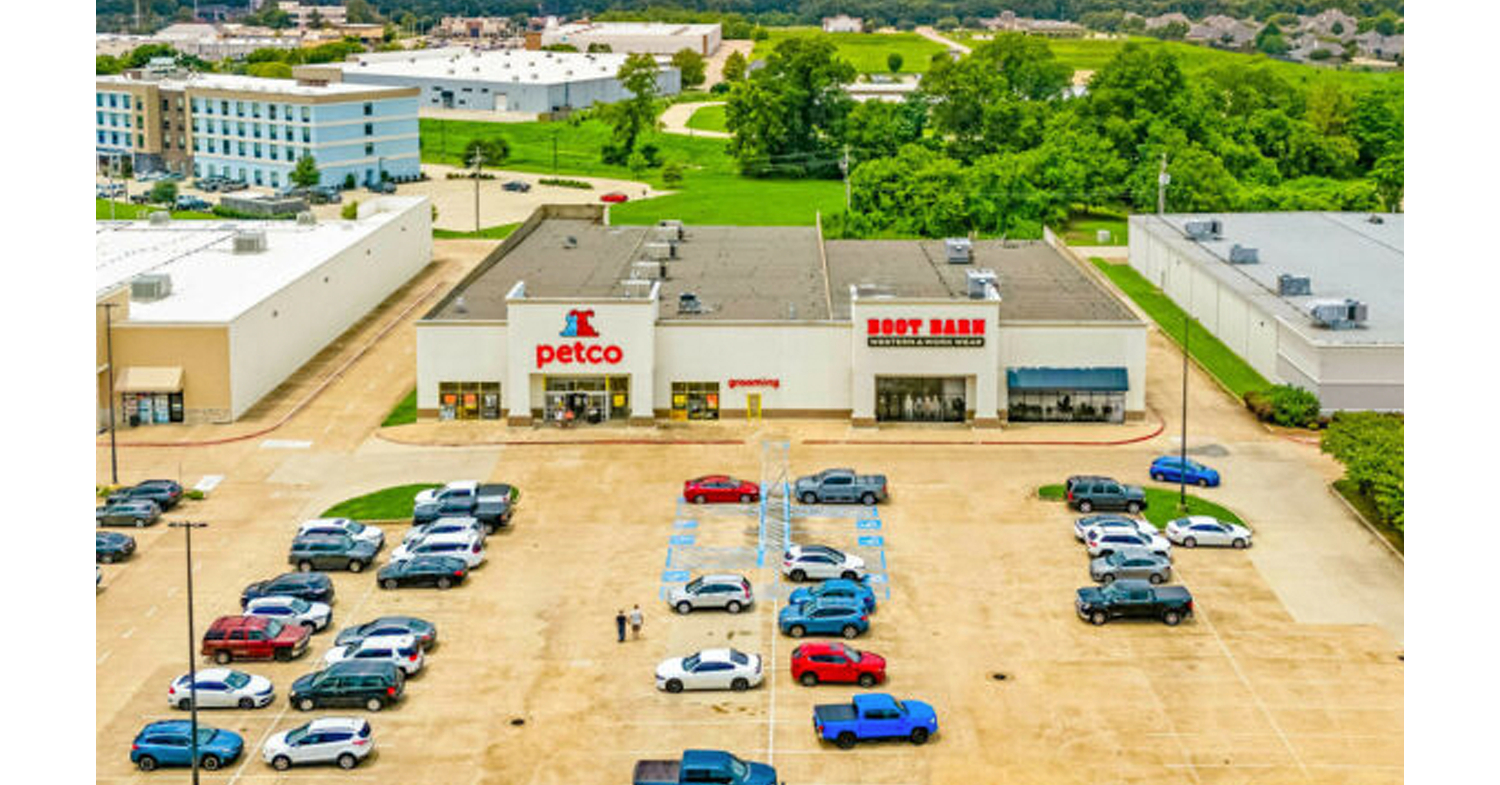
Cove Capital Investments completed a debt-free acquisition of a 29,000-square-foot retail property in Shreveport, LA (Bayou Walk Shopping Center) and plans to raise $7.07M in equity under Reg D Rule 506(c) for its Shreveport Opportunity 120 DST offering. The asset was bought at ~30% below replacement cost, with in-place rents ~29% below the submarket average, creating potential rental upside at lease rollover. Management highlighted fully occupied, nationally backed tenants with lease renewals, with the firm also investing its principals’ capital to reduce investor debt risk.
Analysis
This is not a direct public-equity catalyst; it is mainly a signal that private capital is still willing to buy well-located retail on conservative terms. The real mechanism is cap-rate discipline plus 1031 exchange demand: when sponsors can acquire below replacement cost without leverage, it tends to anchor private-market valuations for similarly situated neighborhood and grocery-anchored centers, but only in low-vacancy submarkets. That is mildly supportive for shopping-center landlords with Sun Belt exposure, while doing essentially nothing for broad retail names unless leasing spreads translate into reported NOI.
The second-order read-through is on local demand durability, not on the quoted tenants. If the surrounding industrial and data-center projects actually drive durable household formation, the benefit accrues to landlords with lease rollover optionality over the next 12-24 months; if it is mostly construction jobs, the uplift is temporary and will not show up in rent rolls. For public markets, the key variable is whether cap rates stay stable while financing costs remain elevated — if cap rates back up another 50-100 bps, any perceived “below replacement cost” cushion shrinks quickly.
Contrarian view: the market often mistakes debt-free acquisition for safety, but the hidden risk is illiquidity and slow mark-to-market realization. Under-rented assets can look attractive in a sponsor memo while still producing mediocre unlevered returns if rollover is lumpy or tenant retention weakens. For listed REITs, this is only actionable if we see a broader improvement in retail lease spreads and same-store NOI; otherwise, it is mostly noise for AMZN and SLB and a watch item for regional retail property owners.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Ticker Sentiment
Key Decisions for Investors
- No immediate trade in AMZN or SLB on this item; treat the cited Shreveport projects as local-color only unless we see follow-through in hiring, permitting, or capex data over the next 1-3 months.
- Watch KIM and REG for 3Q-4Q retail leasing spread confirmation; if Sun Belt strip-center spreads stay positive and cap rates remain stable, add on weakness rather than chase the move.
- Relative-value idea: long quality shopping-center REITs (KIM/REG) vs. higher-leverage retail property exposure if retail cap rates widen; thesis only works if financing stress resurfaces over the next 6-12 months.
- Set an alert on NAREIT retail cap-rate and same-store NOI prints; if cap rates rise >75 bps or occupancy softens, fade the ‘below replacement cost’ narrative in private retail DSTs and public strip-center names.
- If you need a catalyst-driven expression, use a small, patient long in retail landlords only after lease-roll and rent-spread data confirm the under-rented asset story; otherwise stay flat because this is not a tradable headline.
More News
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Turning Treasury Uncertainty Into Double-Digit Cash Flow
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Big Tech is betting $700 billion on AI. Healthcare will decide whether the bet pays off
- Amazon AWS Best Positioned Cloud? Hatem Dhiab's AMZN Compute & Backlog Bull Case
- Coupang vs. MercadoLibre: Which Consumer Stock Is a Better Buy in 2026?