
Seven dozen medical students disperse across the Mid-South for clinical rotations
Source: PR Newswire
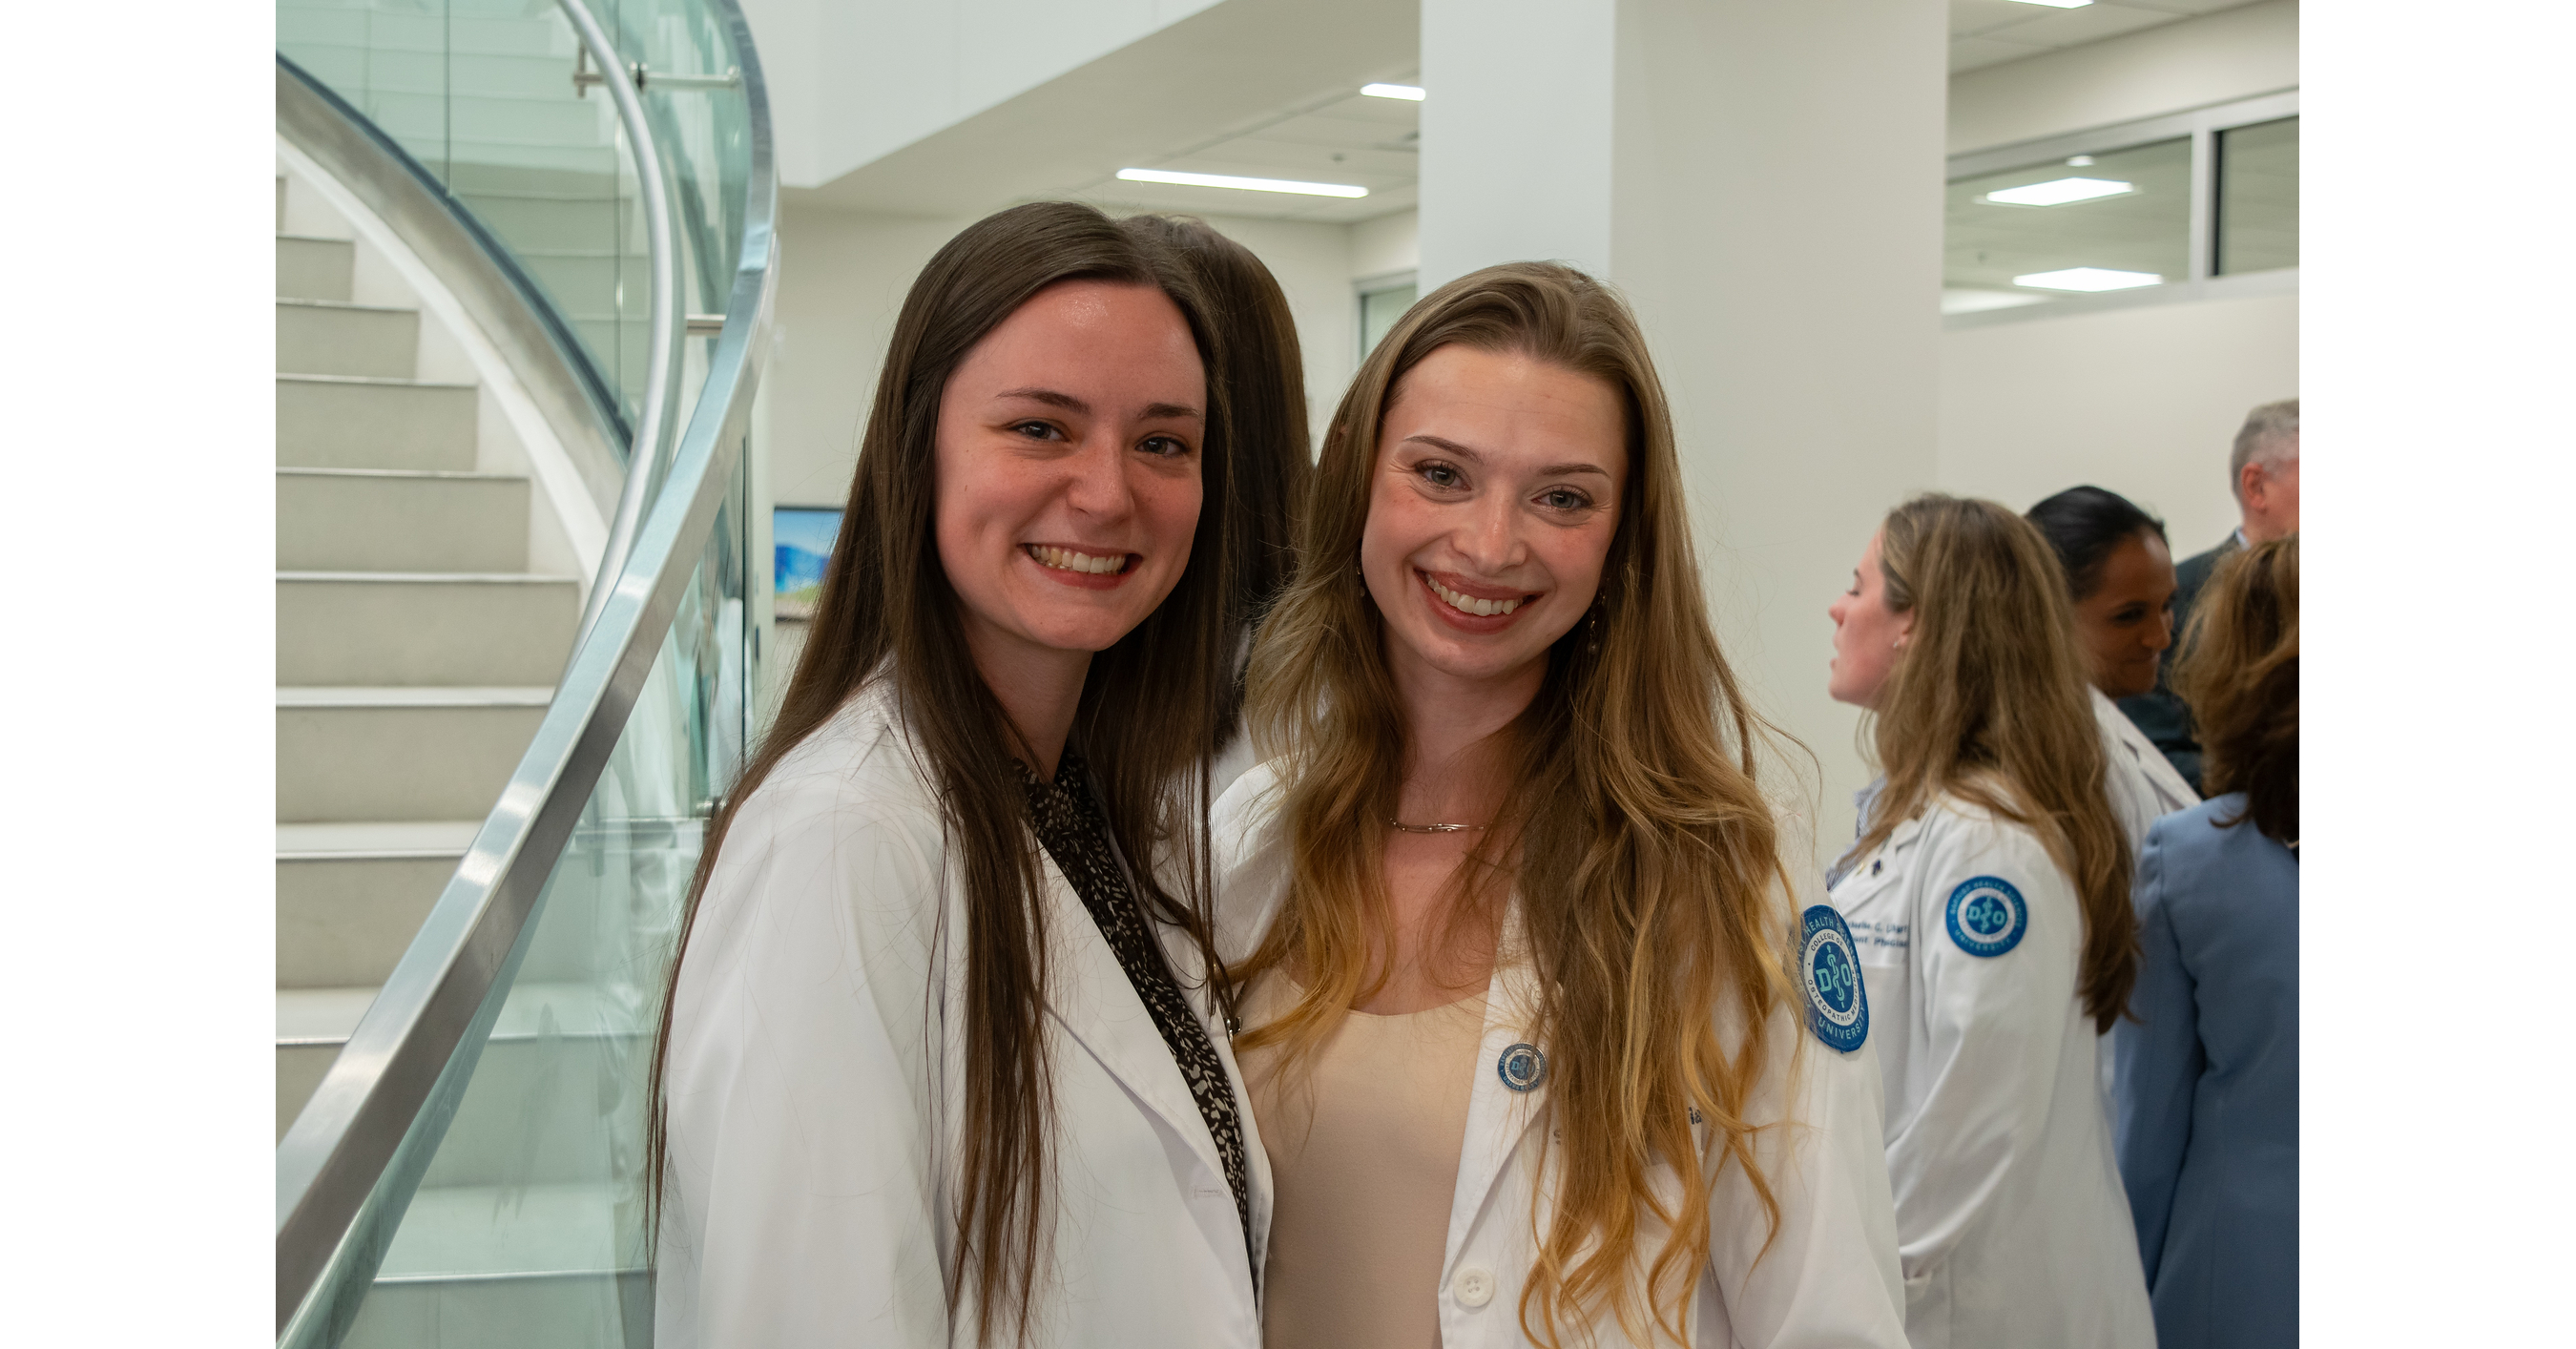
Baptist Health Sciences University College of Osteopathic Medicine began clinical rotations for its first third-year class, placing 74 students across Mid-South hospitals in Arkansas, Mississippi, and Tennessee (e.g., 22 at Baptist Memorial Hospital–Memphis and 19 at Mississippi Baptist Medical Center). The move is framed as an effort to address projected physician shortages of almost 70,000 primary care doctors by 2036 and improve access to high-quality care. No financial figures or market-changing guidance were provided, so expected impact is limited.
Analysis
This is a real-world supply-side story, but the investable impact is mostly years away. The only economically meaningful second-order effect is a deeper physician pipeline for a region that already struggles to recruit; that can lower physician acquisition costs, improve specialist coverage, and reduce patient leakage for the local health system. For public-market comps, that is mildly constructive for large hospital operators with similar Midwest/South footprints such as HCA and UHS, but the magnitude is too small to move valuation on its own.
The more interesting read-through is negative for physician-staffing intermediaries and locums over a 6-18 month horizon if the school’s graduates disproportionately stay local and fill hard-to-cover primary care slots. But that requires retention, residency placement, and eventual practice-location data that we do not yet have. The market’s likely mistake would be to treat enrollment/rotation milestones as near-term earnings catalysts; they are not. The falsifier is simple: if match data or post-residency retention is weak, the structural benefit evaporates and there is no trade. In the next 1-3 months, this should be a non-event for listed healthcare names.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- No immediate position in ADLI/CTRYQ/HESG/MDCE; the signal is too small and too delayed to justify capital deployment now.
- Set a 24-36 month watch on HCA and UHS as potential indirect beneficiaries if the program proves sticky and reduces regional physician recruitment costs; only engage if local staffing metrics tighten.
- Do not short AMN on this headline alone; wait for evidence of residency match and post-training retention before considering a locums/contract-staffing hedge.
- Trigger for a real trade: if >50% of the inaugural class remains in the Mid-South after residency, revisit a long HCA/UHS vs. AMN pair; otherwise the thesis stays non-investable.
More News
- FDA approves Enspryng for thyroid eye disease treatment
- Trump administration advances plan for peptide drugs favored by RFK Jr.
- We're trimming a rallying defensive stock and buying other on a muted earnings move
- Vanguards of Healthcare: Tandem’s Next Wave of Insulin Pump Tech
- People in China are spending nearly as much of their income as Americans on healthcare
- Startup Abby Care raises $82 million to turn family members into paid caregivers
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Tools for Private Equity Due Diligence: A Buyer Workflow
- Weekly Update: In-App Tutorials, Futures Data, and Watchlist Enhancements