
« Éclat du cachemire oriental : L'événement promotionnel Milan Moment » 2026 de Yulin Cashmere s'est déroulé avec succès à Milan
Source: PR Newswire
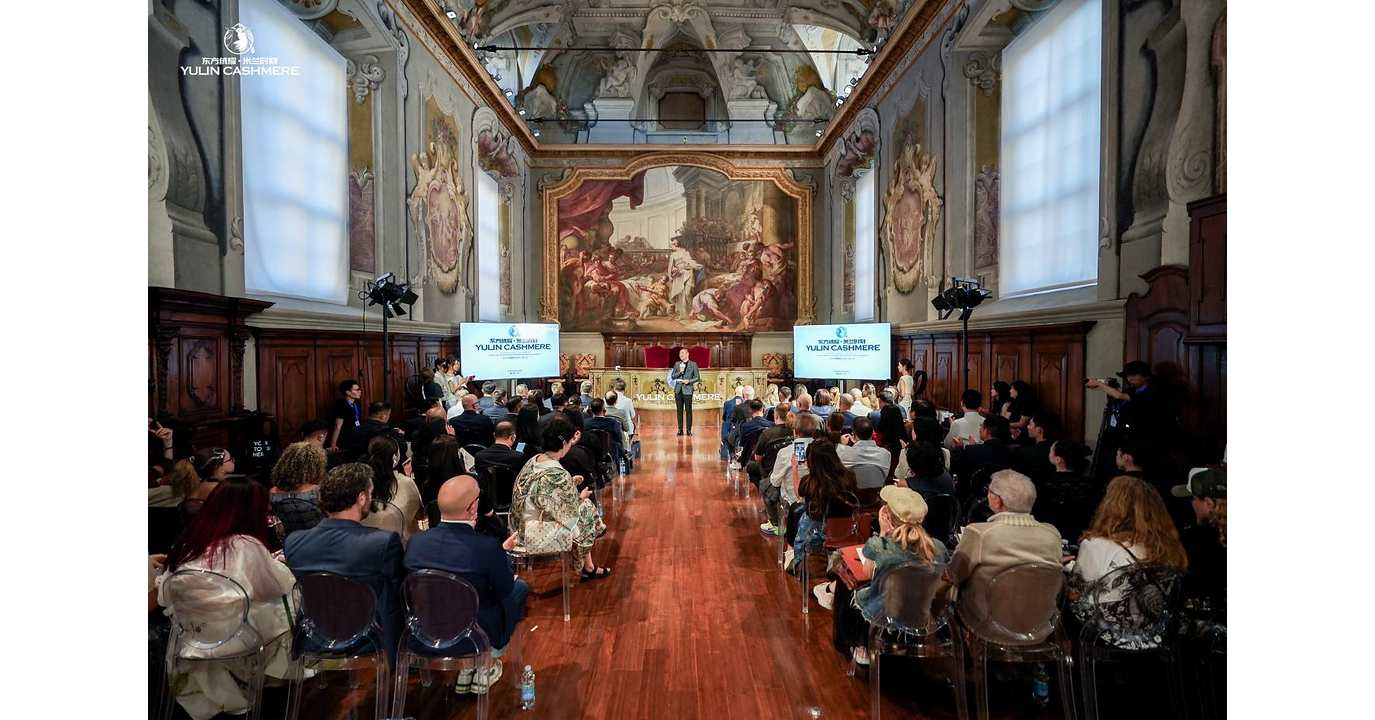
Four Yulin cashmere companies—Yingguo Industry, Shaanxi Tuocheng Cashmere Industry Technology, Yulin Yanglaoda and HBEH—signed market-entry cooperation agreements with Italian buying companies Casile & Casile and IWC at a Milan promotional event. The agreements establish direct links between Yulin’s cashmere brands and European high-end purchasing and retail networks, supporting Yulin’s strategy to shift from raw-material exports toward global branded apparel. The announcement is positive for the participating firms’ international distribution prospects but is unlikely to have broad market impact.
Analysis
This is not independently verifiable demand data; it is supplier-led marketing and should not alter earnings estimates for listed luxury groups absent disclosed purchase volumes, delivery schedules, or retailer sell-through. The more relevant mechanism is gradual disintermediation: direct Chinese sourcing relationships can pressure Italian converters and knitwear manufacturers that historically earn a margin through procurement, quality control, and small-batch production rather than through brand equity.
Near term, the listed luxury complex has limited exposure because cashmere is a relatively small portion of group COGS and procurement contracts are typically set seasons ahead. Over 6-18 months, scaled direct sourcing could modestly improve gross margins for vertically managed brands such as Brunello Cucinelli (BC) and Ermenegildo Zegna (ZGN), but only if fiber traceability, consistency, and European compliance standards are demonstrably met; otherwise the luxury price premium remains insulated by provenance and craftsmanship.
The contrarian read is that lower-cost upstream capacity can be deflationary for accessible luxury rather than accretive for suppliers: brands may retain any input-cost savings while competing more aggressively on price. A stronger euro versus the yuan would amplify the incentive to source directly, while EU forced-labor, origin-labeling, and sustainability due-diligence enforcement is the principal near-term constraint and could halt commercialization before it reaches material scale.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No directional trade on this announcement; wait for disclosed multi-season order values, named European brand customers, and evidence of shipments before revising luxury-sector estimates.
- Set a 6-12 month watch on BC and ZGN: positive only if gross-margin guidance improves without higher inventory or markdown risk, indicating sourcing efficiencies are being retained rather than passed through. Falsifier: rising inventory days or gross-margin compression despite stable full-price sell-through.
- Monitor Italian textile/industrial exposure through SMI.MI and private-label supply-chain commentary for margin pressure from direct sourcing. A tradeable short thesis requires evidence of lost contracts or lower utilization, not promotional agreements.
- Track EU supply-chain due-diligence and textile-origin rules over the next 3-9 months; any enforcement action or traceability failure would invalidate the direct-sourcing margin thesis and favor established European vertically controlled suppliers.
More News
- Oil falls on report Asia will import highest volume of crude since start of Iran war
- America’s Asian allies want a Trump-Xi truce — but not at their expense
- Chinese authorities reportedly in possession of F-35 components in Hong Kong
- Meta announces new lightweight virtual reality glasses to one-up Apple’s Vision Pro
- Trump evalúa prohibir exportaciones de diésel de EE.UU.
- ASPI's Cutler on Trump-Xi Summit, Trade Relations
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Best AI Stock Research Tools for Professional Investors
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More