
Senspa Enters a New Era Under Local Ownership, Bringing the Ammortal Chamber to Northern California
Source: PRWeb
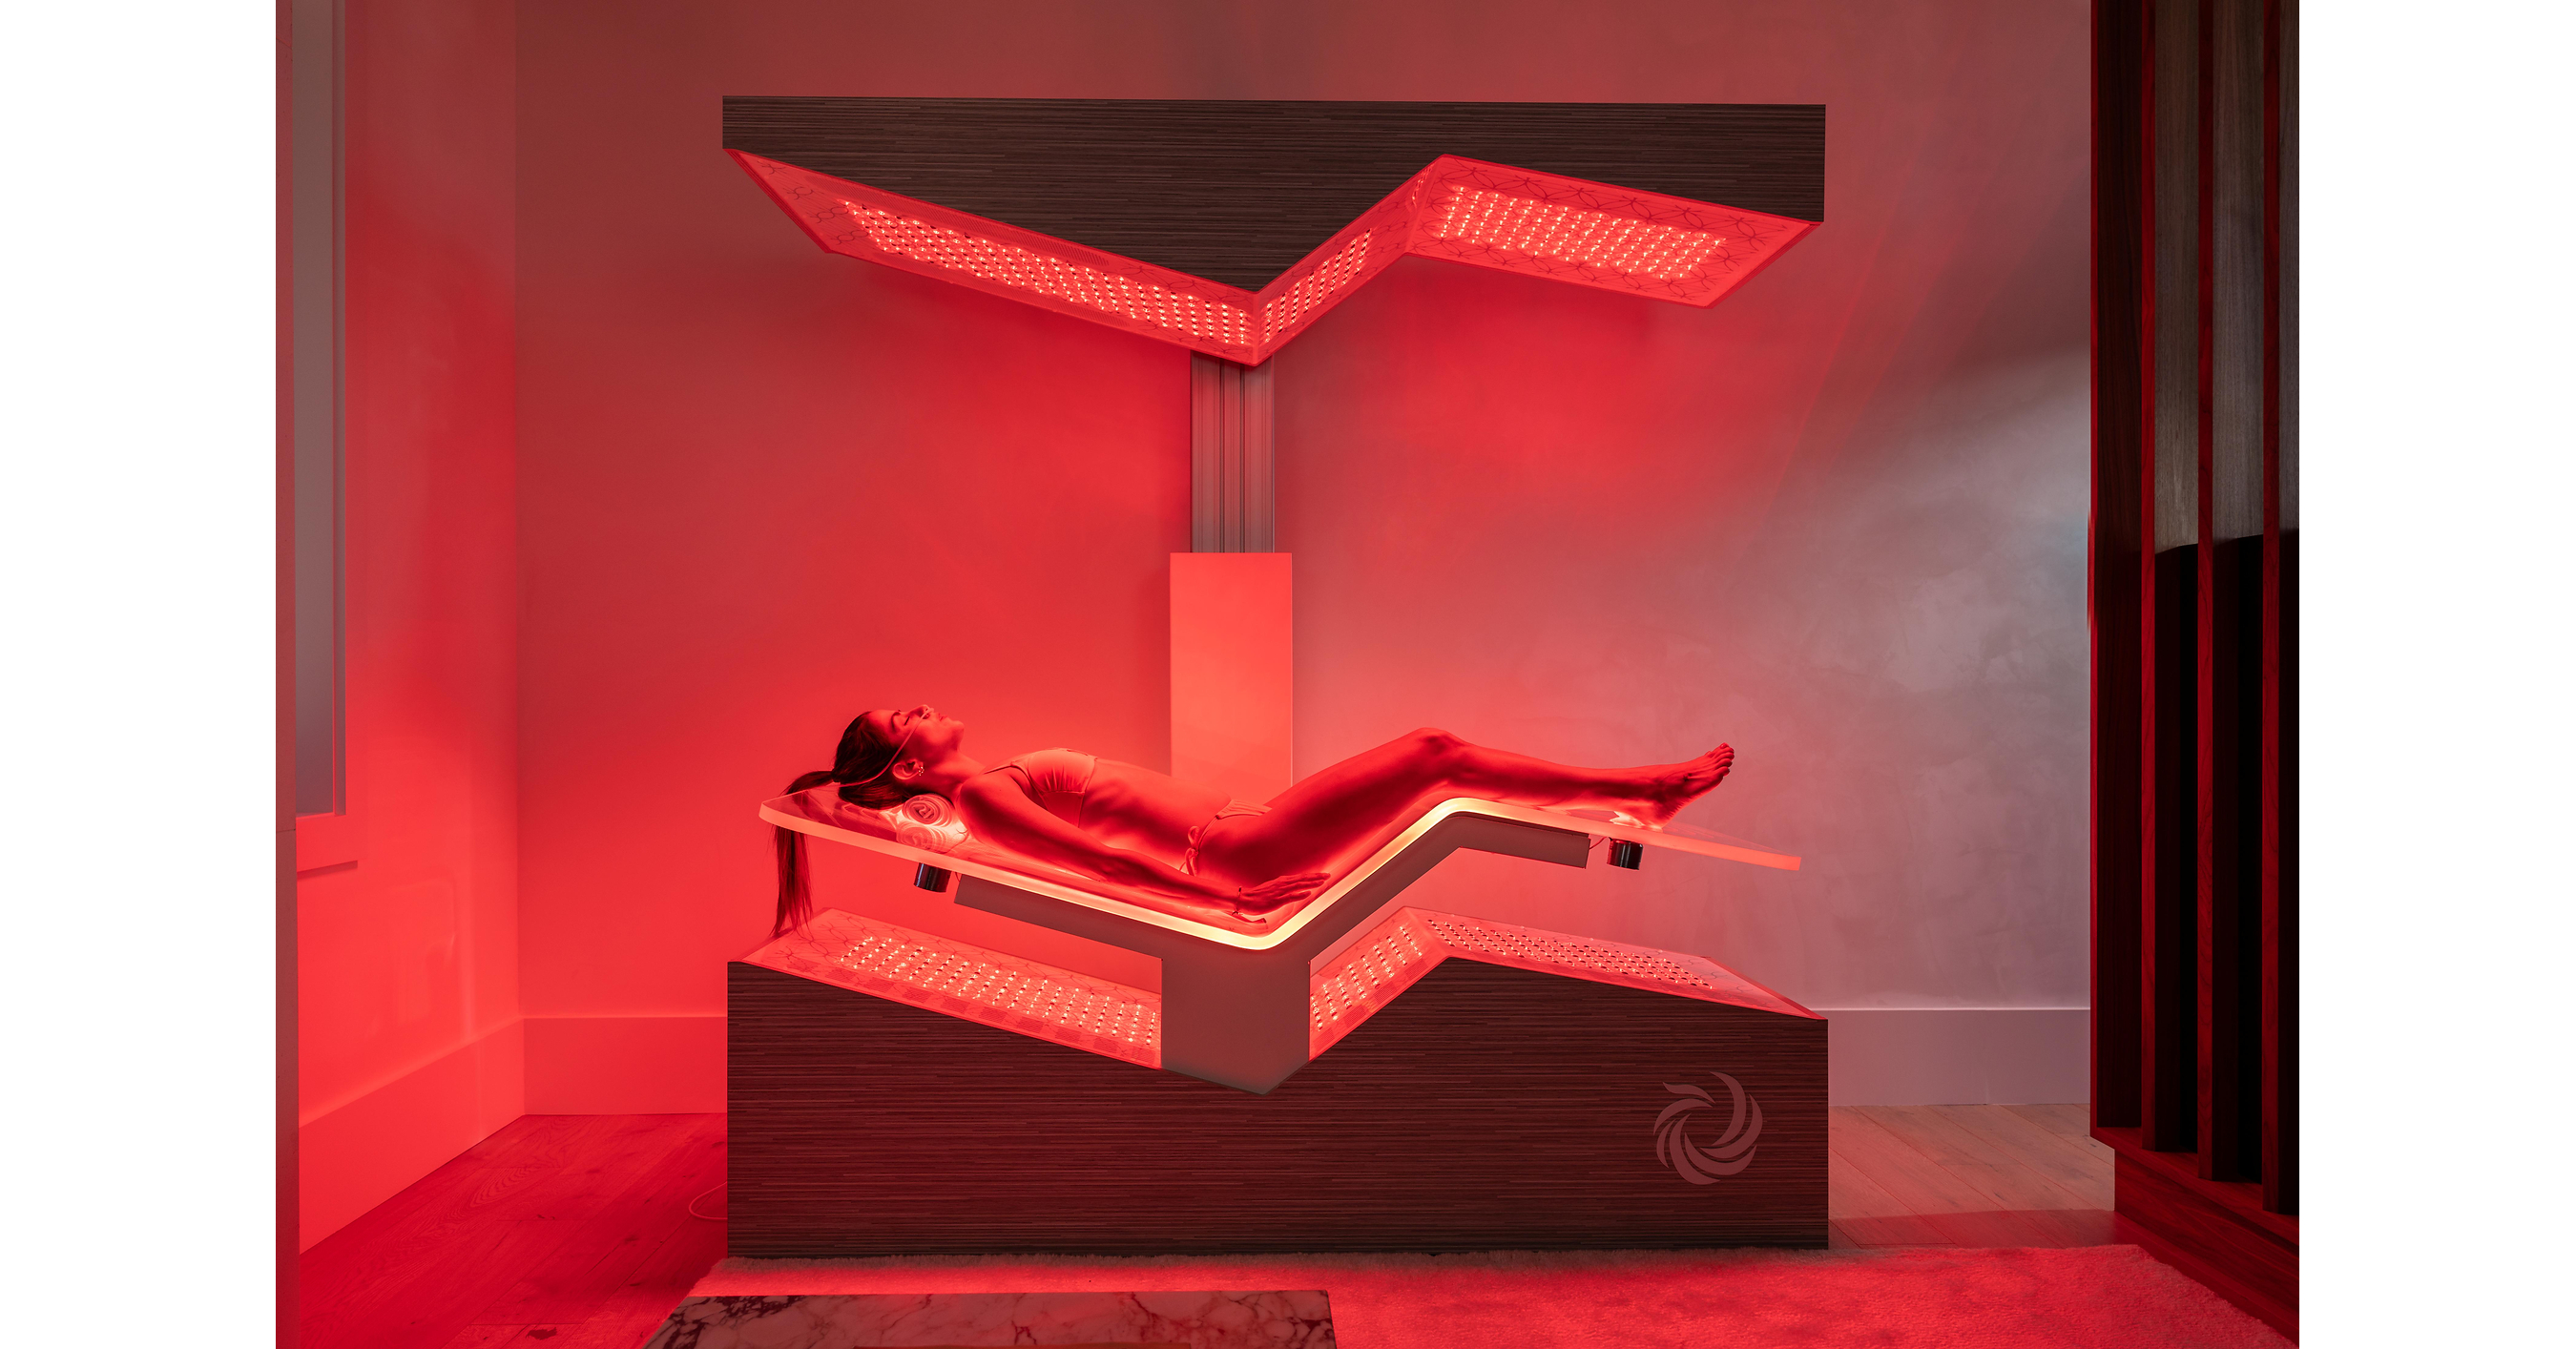
Senspa, a San Francisco Presidio day spa operating for more than 20 years, has launched a refreshed brand and expanded treatment menu under new owners Kyle Withycombe and Stephany Lawrence. The spa introduced Northern California's only Ammortal Chamber, combining more than 10 non-invasive wellness technologies in 25- or 50-minute sessions, and reorganized services around Regulation, Recovery and Longevity pathways. Further treatment additions and an interior refresh are planned for 2027, though the announcement is unlikely to have material public-market impact.
Analysis
No public-equity read-through is sufficiently direct to support a position. This is a small, privately held experiential-wellness deployment, and the claimed differentiation is commercially unverified: utilization, session pricing, repeat frequency, payback on equipment, and any measurable clinical outcomes are absent. The near-term implication is limited to a local test of whether consumers will pay incremental spend for bundled, technology-led recovery services rather than conventional spa treatments.
The more relevant second-order signal is for premium wellness equipment and service providers: if technology-enabled treatments lift revenue per visit without materially increasing labor hours, operators may favor capex-heavy modalities over therapist-intensive services. That could eventually support adjacent public proxies such as Life Time (LTH), Planet Fitness (PLNT), and medical-aesthetics/wellness platforms, but one location cannot establish demand elasticity or scalable unit economics. Consumer discretionary weakness would likely expose these offerings as deferrable spend before it affects core fitness memberships.
Over 6-18 months, watch for replication across Bay Area hospitality, luxury fitness, and med-spa locations; that would matter more for suppliers of red-light, PEMF, and recovery equipment than for broad healthcare equities. A 2027 renovation creates execution risk: temporary capacity loss, construction overruns, and customer disruption can offset any ticket uplift. The contrarian view is that novelty may produce initial bookings but weak retention once promotional demand is exhausted, particularly if wellness claims remain difficult to substantiate.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Key Decisions for Investors
- No trade currently: treat this as a consumer-wellness demand datapoint, not an investable catalyst, given no listed issuer, disclosed economics, or independently verified outcomes.
- Create a 6-12 month watchlist around LTH and PLNT for evidence that premium recovery/technology amenities raise ancillary revenue per member and retention; upgrade only if company disclosures show sustained ancillary-revenue acceleration rather than isolated amenity spending.
- For public med-spa or wellness-equipment exposure, require supplier identification plus installation volume, equipment price, utilization, and financing terms before initiating a position; absent these data, any revenue attribution would be speculative.
- Monitor Bay Area discretionary-spending indicators and luxury-service booking trends through the next two quarters. A deterioration in high-income consumer services would falsify a broad premium-wellness demand thesis before any local expansion can become meaningful.
More News
- Here’s the Tesla Semi… again
- Costco makes progress on a key membership metric. Here's our new price target on the stock
- Tesla poised to scale production of heavy-duty Semi trucks with opening of Nevada factory
- Why we like Starbucks’ latest turnaround move — plus, two more wins for Eli Lilly
- Argentina’s poverty rises to 32 percent under Milei with more pain forecast
- New York sues Polymarket over allegations of illegal gambling operations
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Palantir (PLTR) Q4 2025 Earnings: 70% Revenue Growth, Then an 11% Single-Day Crash
- AlphaSense Pricing: What Public Contract Data Shows in 2026