
As the Skin Tightening Category Gets Louder, Leading Providers Are Choosing EVERESSE™ from Cartessa Aesthetics
Source: PR Newswire
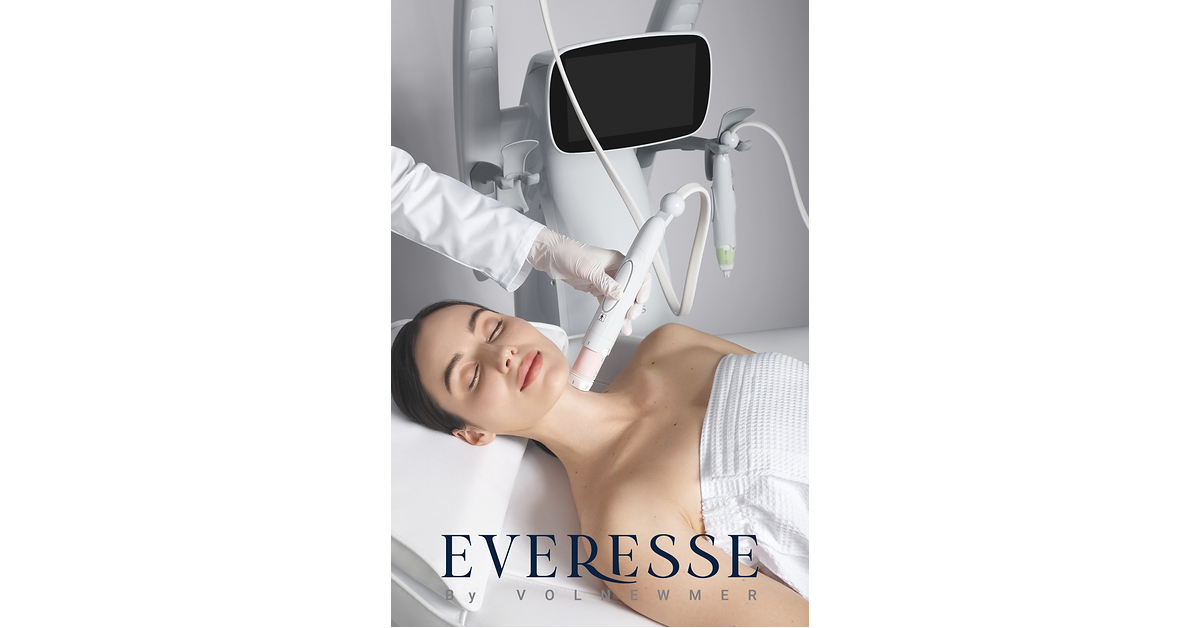
Cartessa Aesthetics reported strong first-half 2026 momentum, led by its exclusive North American commercialization of CLASSYS' EVERESSE monopolar RF platform. EVERESSE has surpassed 4,000 global installations and generated more than 12,000 treatments in the U.S. and Canada, supported by 11 published clinical studies and approximately 430 million organic media impressions. Cartessa also expanded its portfolio with launches of DEKA's ONDA PRO in the U.S. and Canada, PRISMA in Canada, and CLASSYS' QUADESSY in the U.S.
Analysis
This is directionally supportive for CLASSYS (KOSDAQ: 214150) because North American commercialization can extend consumables, service and replacement-device revenue beyond the initial capital-equipment sale. The more consequential signal is whether provider utilization converts into recurring treatment demand: high patient throughput improves practice ROI, supporting follow-on purchases and reducing the discounting risk that typically emerges in crowded energy-based aesthetics categories. The release does not disclose North American unit sales, average selling price, installed-base utilization, or Cartessa inventory, so its financial significance remains unverified.
Competitive pressure should fall most directly on publicly traded InMode (INMD), whose valuation depends on sustaining premium-margin demand for minimally invasive and energy-based platforms amid a weak elective-procedure spending backdrop. A genuinely differentiated comfort/outcome profile could shift purchasing toward RF platforms at the expense of lower-utilization ultrasound and legacy RF equipment, but the near-term effect is likely incremental rather than category-disruptive. Over 6-18 months, an expanded Cartessa distributor footprint could also be favorable for El.En. (BIT: ELN), whose DEKA portfolio gains North American access without building a standalone commercial organization.
The contrarian view is that media impressions and physician endorsements are weak predictors of device-company earnings; clinic financing availability, procedure pricing, and consumer discretionary demand matter more. The thesis is falsified if CLASSYS reports only modest overseas growth despite shipment expansion, if INMD maintains procedure-system sales and gross margin without heavier promotions, or if independent comparative data fail to show a measurable utilization advantage. There is no clean immediate trade from this press release alone; the next investable catalyst is reported quarterly export growth, distributor receivables, and evidence of reorder/service revenue over the next 1-3 months.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.46
Key Decisions for Investors
- Watchlist CLASSYS (KOSDAQ: 214150) for a long entry only after its next results confirm accelerating North American/export revenue and stable gross margin; require evidence that growth is not solely distributor inventory loading. Initial risk framework: exit on a material sequential deceleration in overseas sales or rising receivables/inventory.
- Maintain a relative-value monitor: long CLASSYS versus short INMD only if independent channel checks show meaningful provider conversion from competing RF/ultrasound systems and INMD begins cutting price or misses system-sales guidance. Target a 3-6 month holding period; do not initiate from this release because no unit-share data are provided.
- Track El.En. (BIT: ELN) for DEKA-related North American order commentary in the next two reporting cycles. A confirmed contribution from Cartessa distribution would support a modest long bias; lack of disclosed orders or margin dilution from distributor terms would invalidate the setup.
- Avoid treating consumer-awareness metrics as a catalyst. Require procedure-volume, capital-sales, or recurring-service data before assigning revenue impact to the reported installation and treatment figures.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Fed hikes again - an AI-Picked insurer is still cashing in
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- US official says upcoming spectrum auctions could generate more than $100 billion
- Investors react to Fed hike and market sell-off: Brace for 'higher for longer' rates
- AI Buildout Hits Inflation as Fed Hikes Rates