
Hisense Unveils New C3 Projector Family for Immersive Home Entertainment
Source: PR Newswire
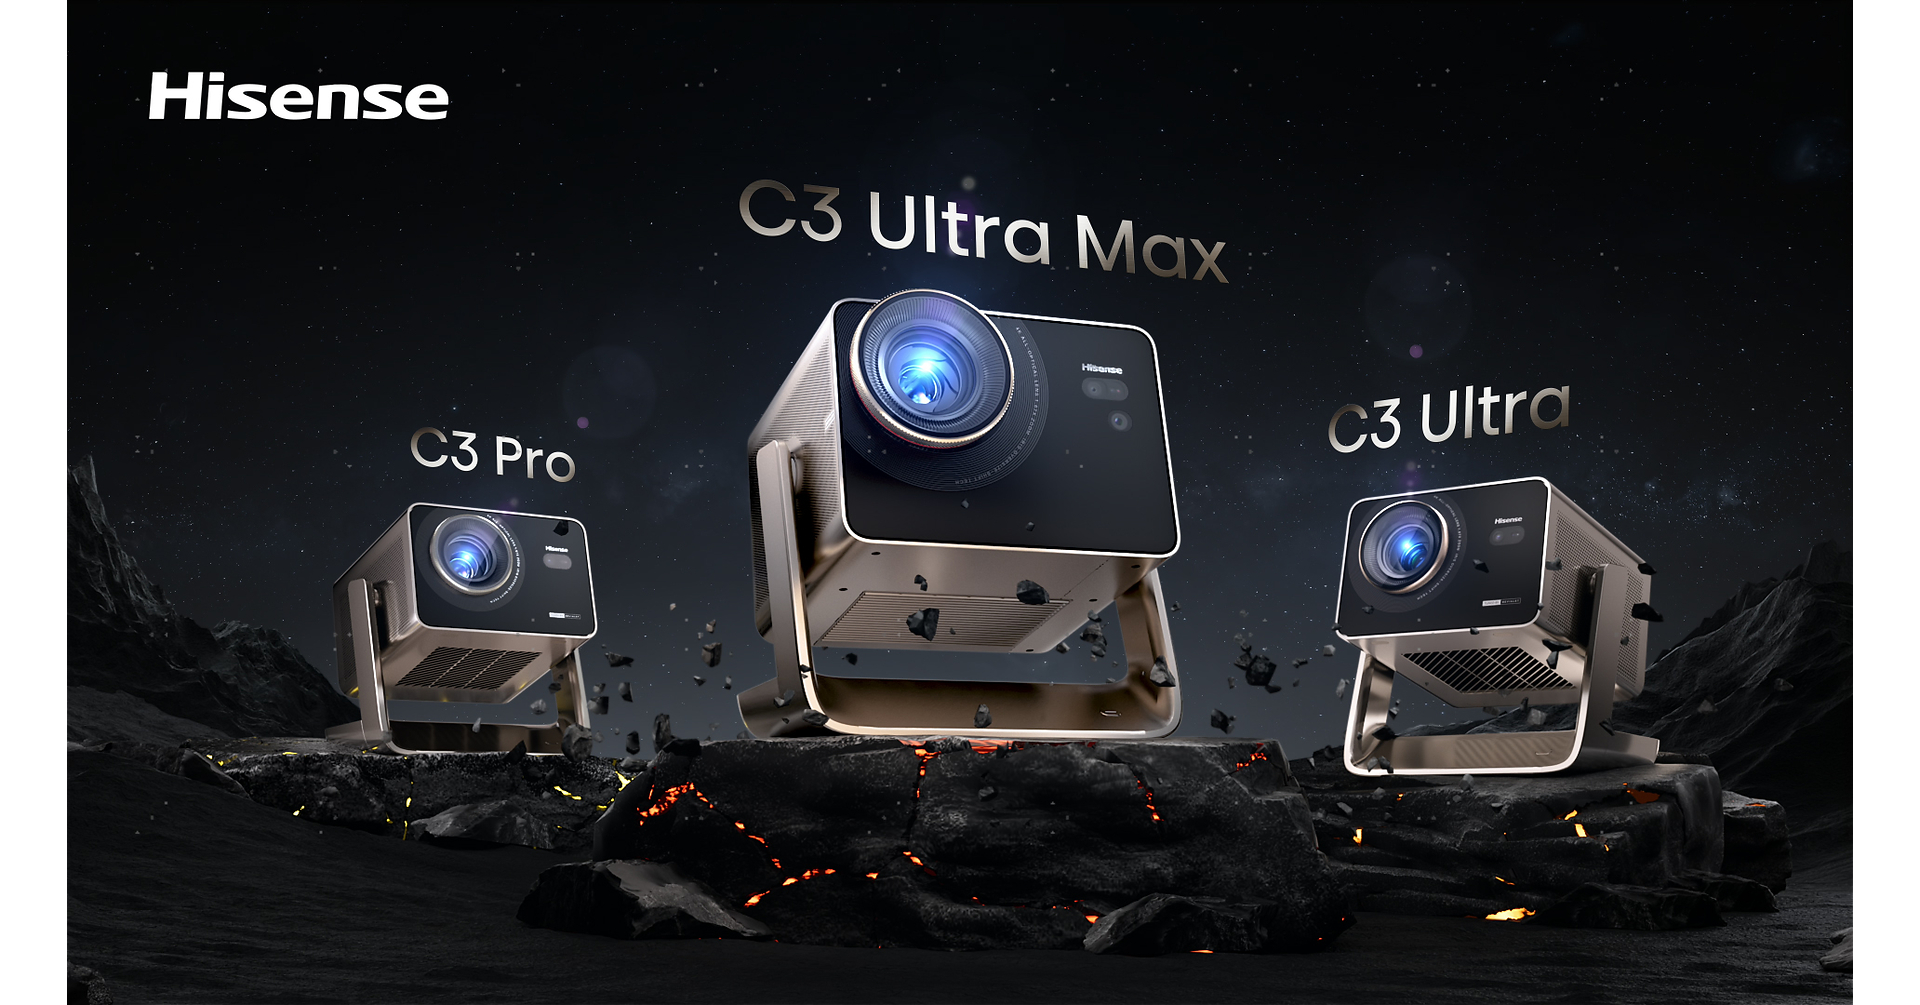
Hisense launched its C3 projector family globally in September, led by the C3 Ultra Max with 5,000 ANSI lumens, 5,000:1 contrast and 1ms latency; the C3 Ultra offers 4,000 lumens, while the C3 Pro offers 3,000 lumens. The lineup targets home cinema, sports and gaming demand with projection sizes up to 300 inches and Devialet-tuned audio. SGS has verified lifecycle and product-carbon-footprint assessments for the C3, supporting Hisense's product-level environmental transparency claims.
Analysis
This is not independently investable on its own: Hisense is privately held and the release omits MSRP, regional allocation, retailer commitments, component sourcing, and unit-volume targets. The meaningful read-through is whether aggressively specified projectors broaden the substitution set for 98-100 inch LCD/MiniLED TVs, where TCL, Sony, LG Electronics and Samsung compete more directly and where retailers depend on high-ticket sell-through to support mix.
Near term, the launch is more likely a promotional-intensity signal than a material demand catalyst. Projectors carry a lower installed-cost barrier at very large screen sizes, but they retain friction around ambient-light performance, setup and replacement-cycle economics; therefore, they are most disruptive to premium large-format TV demand only if retail pricing lands materially below comparable 100-inch displays. A World Cup-driven marketing window could raise category traffic over the next 3-9 months, yet it may also increase display advertising and channel-inventory spending before demand is proven.
The contrarian view is that projector expansion can be complementary rather than cannibalistic: consumers buying a portable or secondary-room projector may still retain a primary TV. The relevant investable signal is not product specifications but November/December sell-through, retailer discounting and 100-inch TV ASPs. Sustained price cuts in that TV category would indicate competition is shifting from premiumization toward margin-destructive screen-size escalation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Key Decisions for Investors
- No standalone position from this release. Create a 3-6 month monitor for Best Buy (BBY) and major European electronics retailers: track projector discounting, attachment rates and 85-inch-plus TV ASPs through holiday sell-through; a sharp ASP decline would be a negative mix signal for premium display vendors.
- Watch Sony Group (SONY) and LG Electronics (066570 KS) earnings commentary for premium-TV margin and channel inventory revisions over the next two reporting cycles. Consider a tactical underweight only if management cites large-screen promotional pressure or lowers display guidance; absent that evidence, the product announcement is insufficient.
- For a broader large-format display demand recovery thesis, use an alert rather than a trade: improving 100-inch-plus sell-through without incremental discounting would support display-component suppliers such as AU Optronics (2409 TT). Falsifier: holiday channel checks showing inventory build and falling panel prices.
- Monitor FIFA 2026-related consumer-electronics marketing spend in 1H-2H 2026. If category advertising rises while retail traffic and premium ASPs fail to follow, favor short BBY versus a defensive retail basket as operating leverage to discretionary big-ticket demand turns negative.
More News
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- AWS says it can't restore service to Bahrain, UAE facilities 6 months after Iran strikes
- Chinese investors rush into US stocks as Beijing opens wider path overseas
- Factbox-How AI leaders and world governments react to ’AI doom’ fears
- Is Amazon Stock a Buy After Its Best Quarter in Years?
- Two camps have emerged in the debate over AI safety and regulation