
CATL kicks off trial production of battery cells in Hungary
Source: PR Newswire
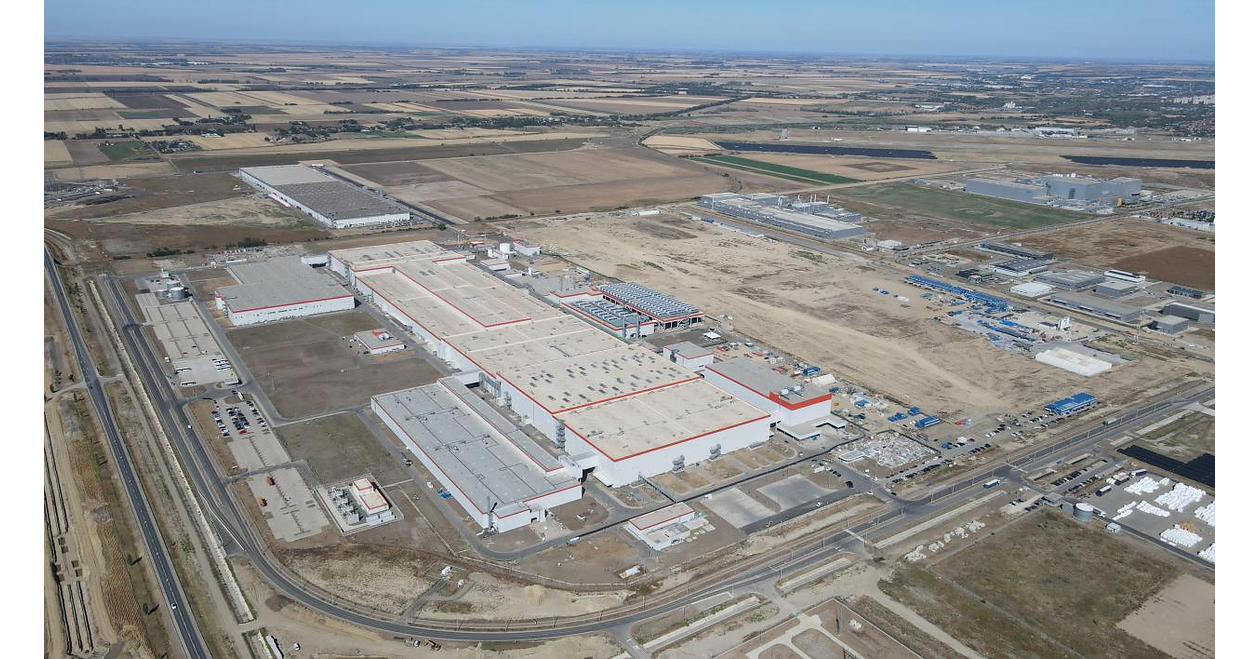
CATL began trial production on the first two battery-cell production lines at its Debrecen, Hungary facility on September 22, 2026, after securing required occupancy, environmental and operating permits. The plant is intended to become CATL's largest manufacturing base outside China, with eventual capacity of 100 GWh, supplying European automakers and strengthening the regional EV battery supply chain. CATL has already produced 537,000 battery modules in Debrecen since module production began in autumn 2024, while authorities confirmed earlier permitting deficiencies had been resolved.
Analysis
The relevant signal is not incremental cell supply alone but a local-cost and regulatory-arbitrage advantage for CATL-linked European EV programs. European production reduces freight, working-capital buffers and transport-related carbon exposure, potentially allowing OEMs to protect vehicle gross margin or price more aggressively against Chinese imports. This is competitively negative for imported Korean/Japanese cell suppliers—LG Energy Solution (373220 KS), Samsung SDI (006400 KS) and Panasonic (6752 JP)—where Europe-bound volumes face weaker logistics economics and greater customer concentration risk.
The near-term investment conclusion should be restrained: trial runs frequently produce delayed yield qualification, scrap costs and customer-validation slippage, so the financial read-through is a 6-18 month issue rather than a next-quarter earnings catalyst. The key datapoints are first customer qualification, stable yields, and whether local supply permits BMW, Mercedes-Benz (MBG GR), Volkswagen (VOW3 GR), Stellantis (STLAM IM), or Renault (RNO FP) to revise battery-cost or EV-margin guidance. A successful ramp would also pressure European aspirant cell manufacturers and subsidy-dependent projects, whose value proposition relies on scarcity of local capacity rather than demonstrated technology or cost leadership.
Consensus may overstate the benefit to all European OEMs: locally manufactured cells improve supply security but do not resolve weak EV demand, charging economics, or OEM fixed-cost absorption. Conversely, the market may underprice CATL's strategic ability to circumvent the practical effects of European supply-chain localization policy; cells made in-region can make Chinese technology structurally harder to exclude even if trade restrictions intensify. The thesis is falsified by a material commissioning delay, adverse environmental enforcement, or OEMs signaling that local cells do not lower pack cost versus alternative supply.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Maintain a 6-12 month relative-value watch: short LG Energy Solution (373220 KS) versus long Volkswagen (VOW3 GR) only after disclosed customer qualification or OEM battery-cost guidance confirms local CATL supply. Target 10-15% relative return; stop if Korean suppliers retain European volume/pricing or CATL ramp slips by more than two quarters.
- For European OEM exposure, favor Volkswagen (VOW3 GR) over Mercedes-Benz (MBG GR) on a 12-18 month horizon if localized cell availability supports lower-cost mass-market EV launches; VW has greater operating leverage to battery-cost reduction, while Mercedes' premium mix provides less volume upside. Do not initiate solely on trial production—wait for named sourcing commitments and 2027 margin guidance.
- Avoid funding European pure-play battery-capacity narratives until ramp yields are independently evidenced. Monitor listed Korean cell suppliers' Europe utilization and pricing commentary over the next two earnings cycles; a utilization downgrade would be the cleaner confirmation of competitive displacement.
- Set an event alert around environmental compliance reports and customer certification milestones over the next 3-9 months. Any enforcement action, production halt, or delayed series-production timeline would create a tactical relief trade in 373220 KS and 006400 KS, while invalidating the European-localization cost thesis.
More News
- Wall Street’s Nasdaq hits all-time high as AI frenzy gathers pace
- Data-Center Bet Makes ESDS One of India’s Best New Listings
- Asia stocks ride tech wave higher, oil stays subdued
- South Korean solar stocks jump as curbs on Chinese sector expected to remain in place
- ‘I have a big decision to make’: Trump had a ‘good meeting’ with Iranian officials warning he may ‘annihilate the Islamic Republic’
- Bank of America says Brent crude oil could top $150 a barrel if Iran war disruptions persist