
Společnost SANY Heavy Truck představuje na veletrhu IAA Transportation 2026 portfolio elektrických nákladních vozidel připravených k sériové výrobě
Source: PR Newswire
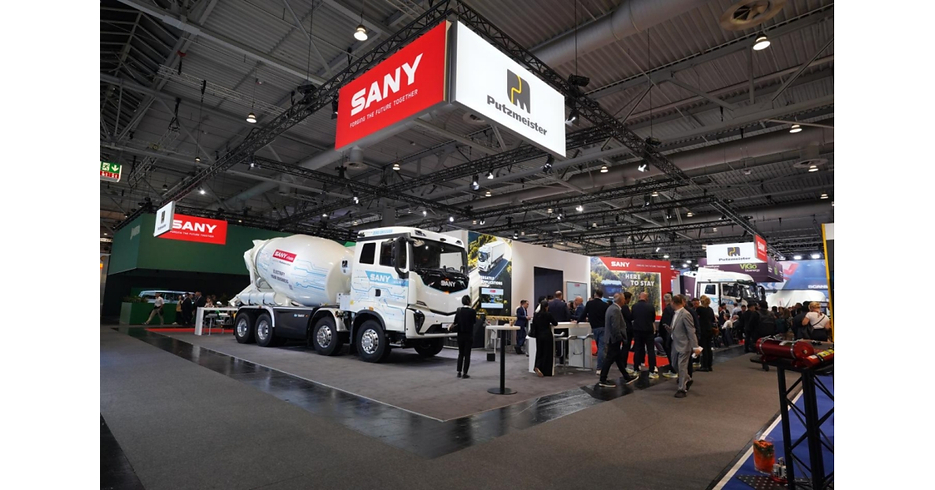
SANY Heavy Truck unveiled its production-ready SE636 battery-electric heavy truck for Europe at IAA Transportation 2026, featuring a 636 kWh battery, up to 500 km of range and EU whole-vehicle type approval. SANY says the model is the first mass-produced battery-electric heavy truck from a Chinese manufacturer to receive EU WVTA, and it is already operating in Germany, Turkey and other European markets. The company has deployed more than 70,000 electric heavy trucks globally, logged over 20 million km in Europe since 2022, and supports customers through roughly 650 European service workshops.
Analysis
This is a competitive-intensity signal rather than a standalone demand catalyst. A credible Chinese entrant in European battery-electric heavy trucks raises the probability of price-led share competition in the standardized regional-haul segment, where incumbents Daimler Truck (DTG.DE), TRATON (8TRA.DE) and Volvo (VOLV-B.ST) are investing heavily before scale has absorbed fixed EV-development costs. The near-term earnings impact should be negligible, but tender pricing and residual-value assumptions could become incremental risks over the next 6-18 months if fleet operators gain a second qualified low-cost source.
The relevant bottleneck is not vehicle availability but financing, charging uptime, parts availability and fleet total cost of ownership. Incumbents retain an advantage through captive finance, dealer coverage, integrated charging offerings and established residual-value data; a service-partner network does not necessarily provide equivalent repair capacity, parts fill rates or warranty-cost control. Watch European fleet tenders over the next 1-3 months for disclosed pricing, warranty terms and delivery commitments: meaningful wins at a 15-20% upfront price discount would pressure the market's assumed EV margin recovery for incumbent OEMs.
Contrarian view: investors may overstate disruption because long-haul battery-electric adoption remains constrained by megawatt-charging buildout and payload economics. The more immediate exposure is likely in vocational applications with predictable depot charging—concrete mixers, municipal fleets and short-haul distribution—rather than broad replacement demand. There is no clean immediate trade from this announcement absent independently verified European order intake, delivered-unit data and financing terms.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.48
Key Decisions for Investors
- Maintain a 6-12 month relative-value watch: long Volvo AB (VOLV-B.ST) versus short TRATON (8TRA.DE) if European electric-truck tender pricing deteriorates. Volvo's service and financing ecosystem should better defend fleet economics; invalidate if TRATON reports superior EV order growth without gross-margin dilution.
- Do not short Daimler Truck (DTG.DE) on this development alone. Establish an alert around quarterly European order intake, truck gross-margin guidance and residual-value provisions; a guidance cut tied to EV pricing or warranty would create a more actionable 1-3 month downside catalyst.
- For China exposure, monitor Sany Heavy Industry (600031.SS) rather than initiating on publicity: require evidence of European deliveries, localized inventory/parts investment and positive export margins before treating Europe as a material earnings driver. The key risk is that aggressive pricing converts volume into low-return export revenue.
- Prefer selective exposure to depot-charging and fleet-electrification infrastructure over truck OEM beta if European commercial-EV adoption accelerates. Reassess names such as ABB (ABBN.SW) and Schneider Electric (SU.PA) after fleet orders demonstrate charging commitments rather than vehicle demonstrations.
More News
- Japan’s corporate leaders sound alarm over weak yen — even dollar-earners are voicing concerns
- Fed hikes again - an AI-Picked insurer is still cashing in
- Berkshire May Boost Japan Trading House Holdings, Itochu Says
- 'Science fiction': Transport companies — the backbone of economy — are sounding alarm on fuel prices
- Oil Extends Slump as Saudi Arabia Moves to Restore Key Pipeline
- US retail sales rebound sharply in August