
Kibar Americas célèbre l'inauguration officielle de l'usine de fabrication d'aluminium de Fairmont
Source: PR Newswire
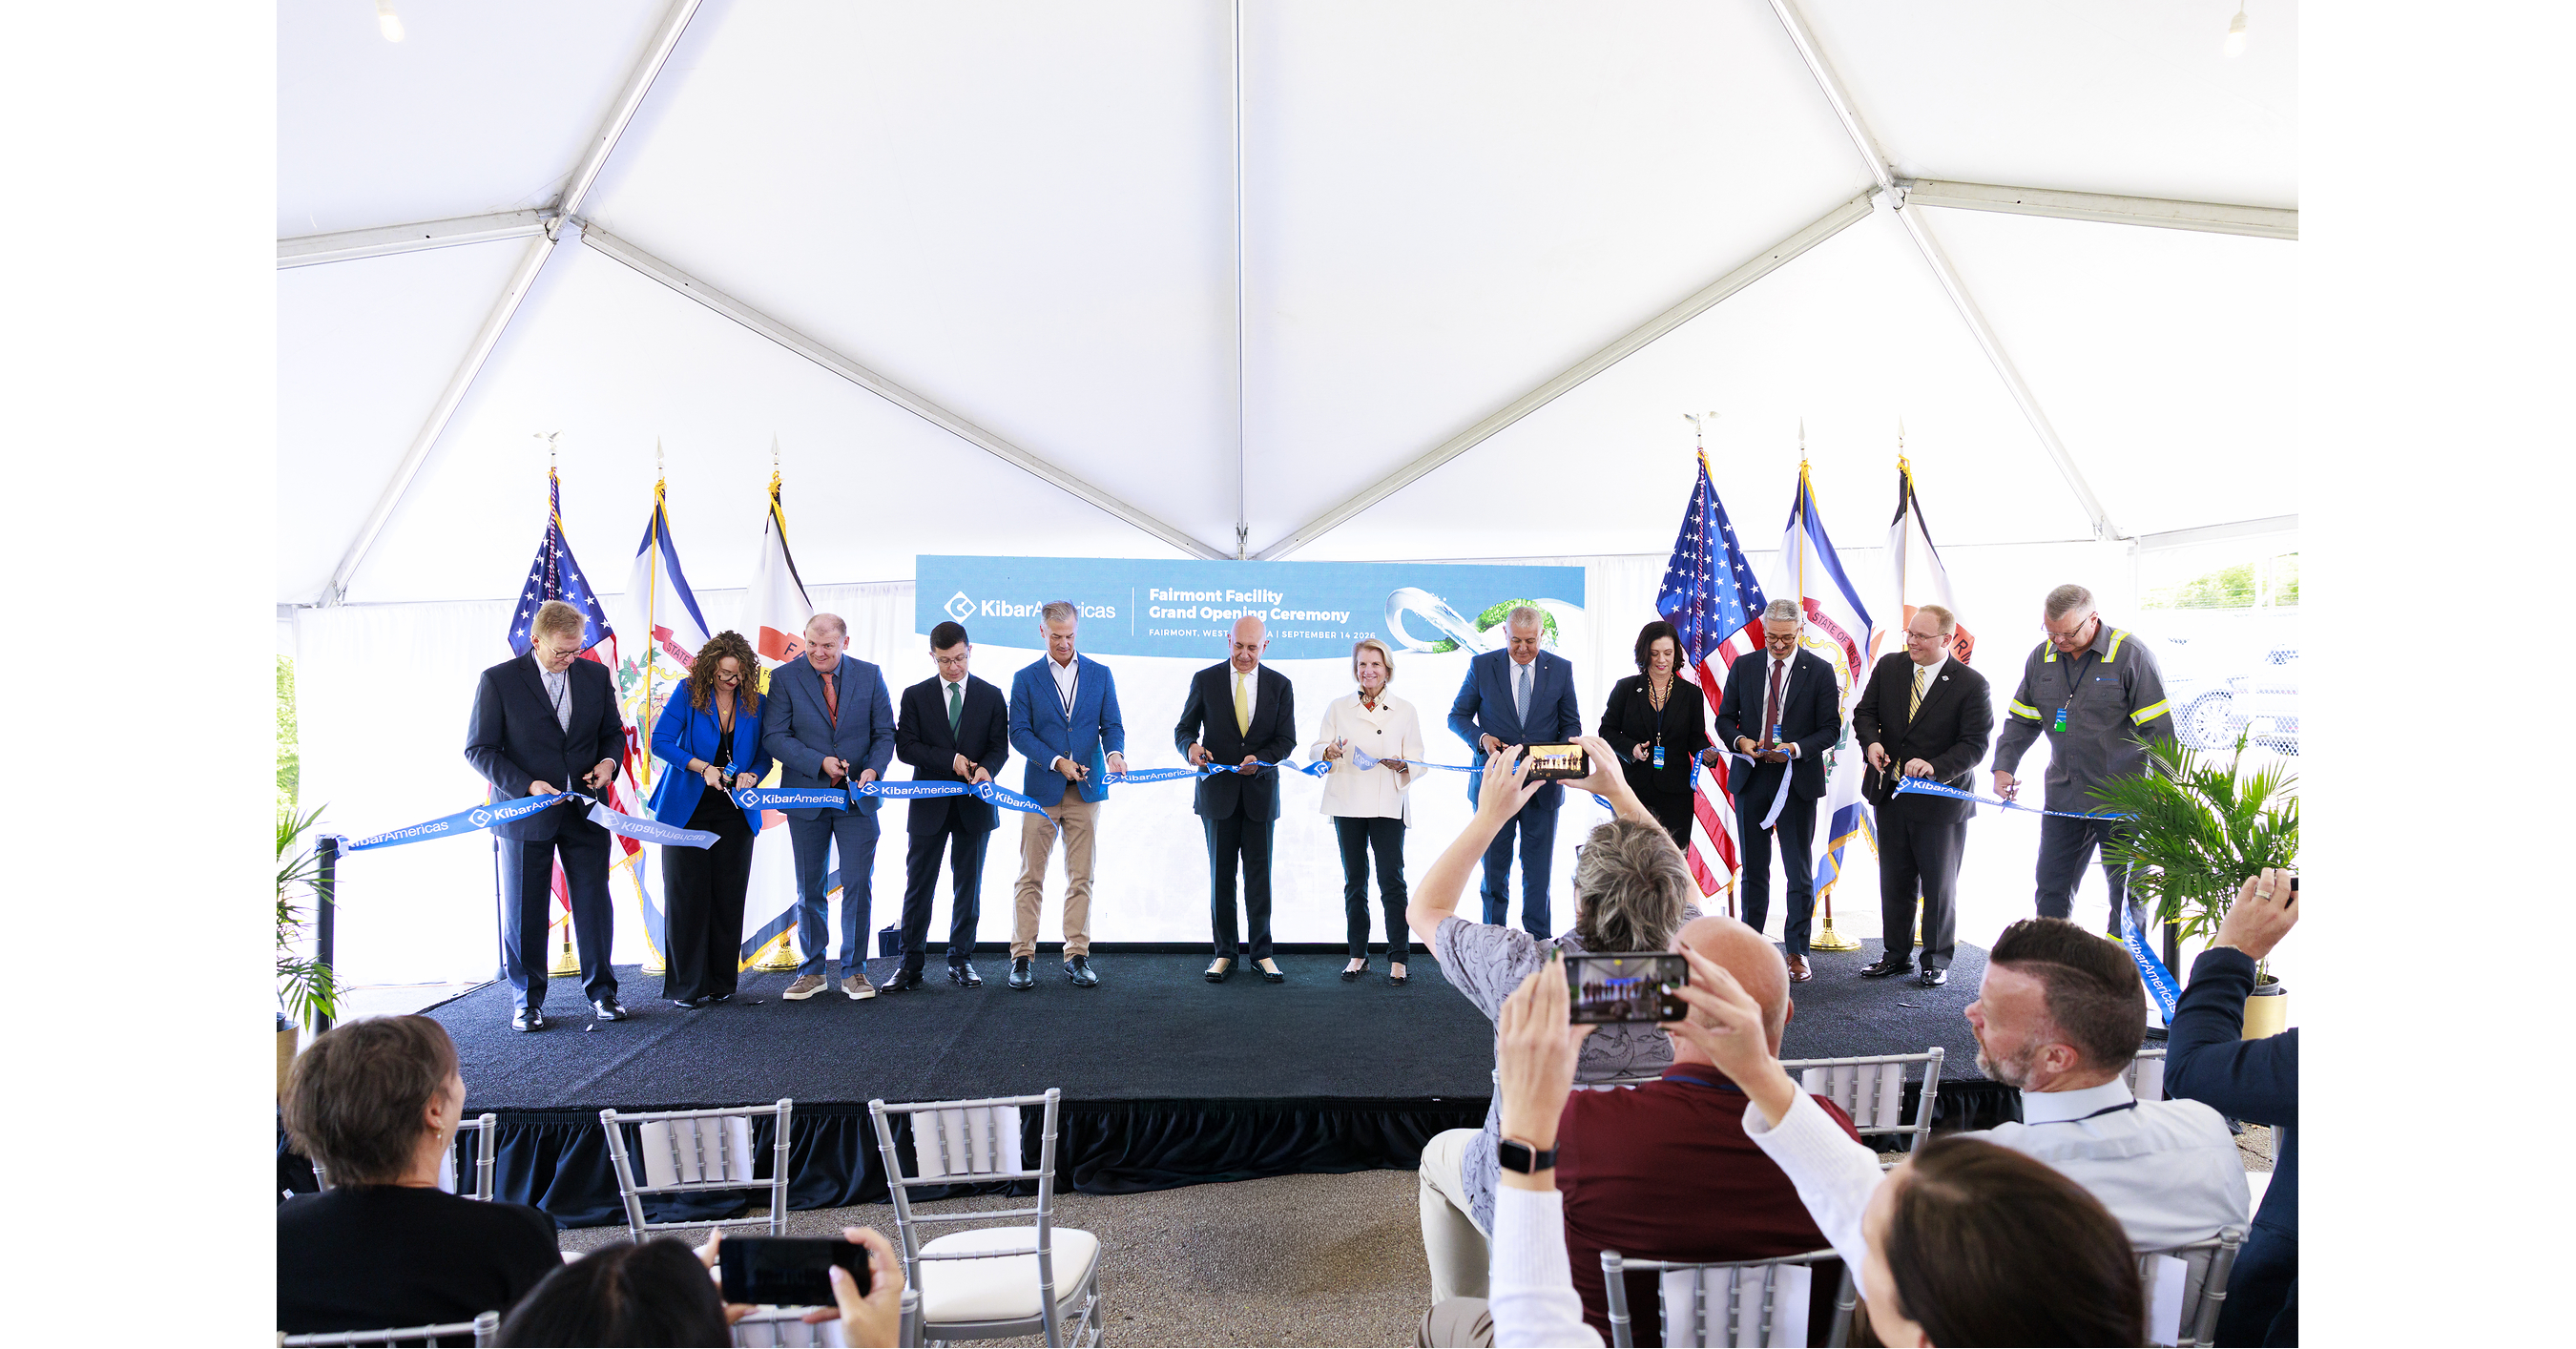
Kibar Americas officially inaugurated and began production at its Fairmont, West Virginia aluminum manufacturing facility, acquired earlier in 2026. The plant will produce aluminum products for HVAC, packaging, automotive and industrial markets, adding local production capacity to the company's established North American commercial and logistics footprint. Management described the site as a cornerstone of its long-term regional growth strategy, with further expansion planned, although no investment amount, capacity or job figures were disclosed.
Analysis
The investable read-through is limited until Fairmont's annual tonnage, product mix, input-metal sourcing and customer commitments are disclosed. A local rolling asset can reduce freight, inventory and tariff friction for Midwest/East Coast buyers, but its financial significance will depend on whether it displaces imported sheet or merely adds capacity into an already competitive regional market. The more exposed public comparator is CSTM, whose rolled-product margins are sensitive to incremental North American supply in automotive and packaging; AA and CENX are less directly affected because their earnings are driven primarily by primary-aluminum pricing and alumina spreads.
Near term, this is not sufficient to alter estimates for public aluminum equities. Over the next 1-3 months, monitor customer qualification announcements, disclosed capacity, and whether Kibar secures long-term can-sheet or HVAC contracts; these would indicate that the asset has pricing power rather than being a low-utilization import-substitution hedge. Automotive qualification is the potentially material 6-18 month catalyst, but it is also the least immediate given OEM validation cycles and high specification requirements.
Contrarian point: domestic manufacturing does not automatically improve economics if the plant relies on imported coil, slab or high-cost U.S. metal. If local supply expands while regional demand from HVAC and packaging softens, the effect could be margin dilution across independent rollers before it benefits customers. The thesis is falsified positively by rapid contracted utilization and stable conversion premiums; negatively by discounting, weak utilization, or evidence that input costs erase the logistics advantage.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.42
Key Decisions for Investors
- No standalone trade on this announcement; set an event-driven alert for capacity, utilization and named customer/offtake disclosures before assigning earnings impact to CSTM, AA or CENX.
- Watch CSTM relative to AA over the next 3-6 months: consider a short CSTM / long AA hedge only if new capacity is disclosed at a scale meaningful to regional rolled-sheet supply and CSTM's conversion-premium guidance weakens. Exit if CSTM maintains pricing and utilization through the next earnings cycle.
- For packaging exposure, monitor BALL and CCK procurement commentary rather than buying them on the news. A sustained reduction in regional aluminum conversion premiums could modestly support can-maker margins, but the benefit is unlikely to be visible without contract renewals or lower material-cost guidance.
- Track Midwest aluminum premium, U.S. sheet import volumes and HVAC demand indicators monthly. Falling premiums alongside rising imports or weaker CARR/TT residential-commercial HVAC commentary would increase the probability that incremental rolling capacity becomes a sector-margin headwind rather than a demand-driven expansion.
More News
- Grab aims for 'next level' in financial services with purchase of buy-now pay-later platform Atome
- China's AI leaders keep quiet despite U.S. 'publicity' on tech risks
- Attacks on Saudi oil expose Iraqi PM’s struggle to control armed factions
- Oil prices dip as U.S. inventory build offsets M.East supply jitters
- Iran war has cost Pentagon $38 billion and depleted missile stockpiles, CBO says
- Exclusive-Malaysia talks to rival airlines as it monitors AirAsia’s financial health, sources say
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense vs Hebbia vs AllMind: Choose by Workflow
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace