
Airbus: 1,000 Orders, But Deliveries Flash A Warning
Source: seekingalpha.com
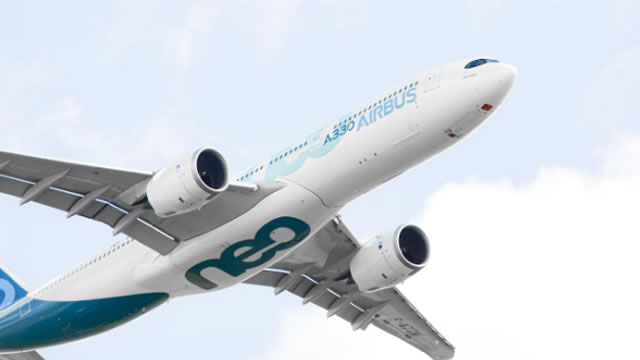
Airbus reported 1,000+ net orders year-to-date and a strong EADSF book-to-bill of 2.6x, indicating ongoing demand strength. July deliveries were flat at 67 units YoY, though A330 deliveries were briefly paused due to a foreign object issue that has been resolved. Net order momentum offsets the production delivery friction, supporting a moderately positive read-through for the commercial aerospace cycle.
Analysis
The market should treat this as a quality-vs-execution story, not a pure demand story. A large order backlog is supportive for valuation, but near-term earnings are governed by delivery cadence, inventory build, and working-capital drag; that means the stock can lag the headline if monthly deliveries stay flat. In other words, the signal is more about 6-18 month revenue visibility than about next quarter EPS.
Competitively, sustained order intake reinforces Airbus’ share lead and makes it harder for Boeing to regain pricing leverage with airlines and lessors. The second-order beneficiary is the supply chain around narrowbody and cabin content, but only if Airbus can keep rates moving without quality interruptions; any further production hiccup would shift the narrative from scarcity to operational fragility and compress the multiple. The A330 pause is a reminder that wide-body execution can still bite margins even when backlog looks bulletproof.
Risk is asymmetry around delivery normalization: if Airbus proves it can convert orders into higher shipments over the next 1-3 months, the stock can rerate on confidence in FCF conversion. If not, the market may start discounting the order book as deferred revenue rather than immediate monetization. The contrarian view is that the market is overpaying for order growth and underpricing the fact that backlog quality deteriorates when customers book far ahead of supply.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.10
Ticker Sentiment
Key Decisions for Investors
- Prefer a 3-6 month long EADSY / short BA pair: Airbus has cleaner demand visibility and better share momentum, while Boeing still carries execution and credibility risk. Enter on weakness rather than chasing a post-headline pop; risk is Boeing stabilizes faster than expected.
- If already long EADSY, use next monthly delivery print as the trigger to add only if shipments re-accelerate; without that, treat order strength as non-catalytic. Falsifier: two consecutive months of flat or lower deliveries.
- For new exposure, consider a 6-12 month call spread on EADSY rather than outright stock if you want to express backlog monetization without paying full multiple. Best risk/reward is when the market underestimates rate expansion, not when the headline is already embedded.
- Watch for guidance around production rates and working capital in the next earnings cycle; if inventory or supplier issues persist, trim longs because free-cash-flow conversion is the real bottleneck. Falsifier: margin guidance down or cash conversion weaker despite stable orders.
- Maintain a tactical watch on Boeing (BA) as the hedge leg; if BA fixes output faster than expected, the relative trade loses edge even if Airbus remains fundamentally sound.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Indonesia Said to Meet Monday With MSCI Over Shock Index Threat
- Ukraine launches over 1,000 drones at Russia, setting oil facilities ablaze
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Australia’s Cleanaway agrees to $6.5 bln EQT buyout bid; shares surge
- India’s Finance Minister blames easy exits and excess liquidity for equity market's underperformance
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market
- Investment Research Software Costs: A 2026 Budget Framework