
Best City to Live in for Expats 2026: Hong Kong Versus Singapore
Source: Bloomberg
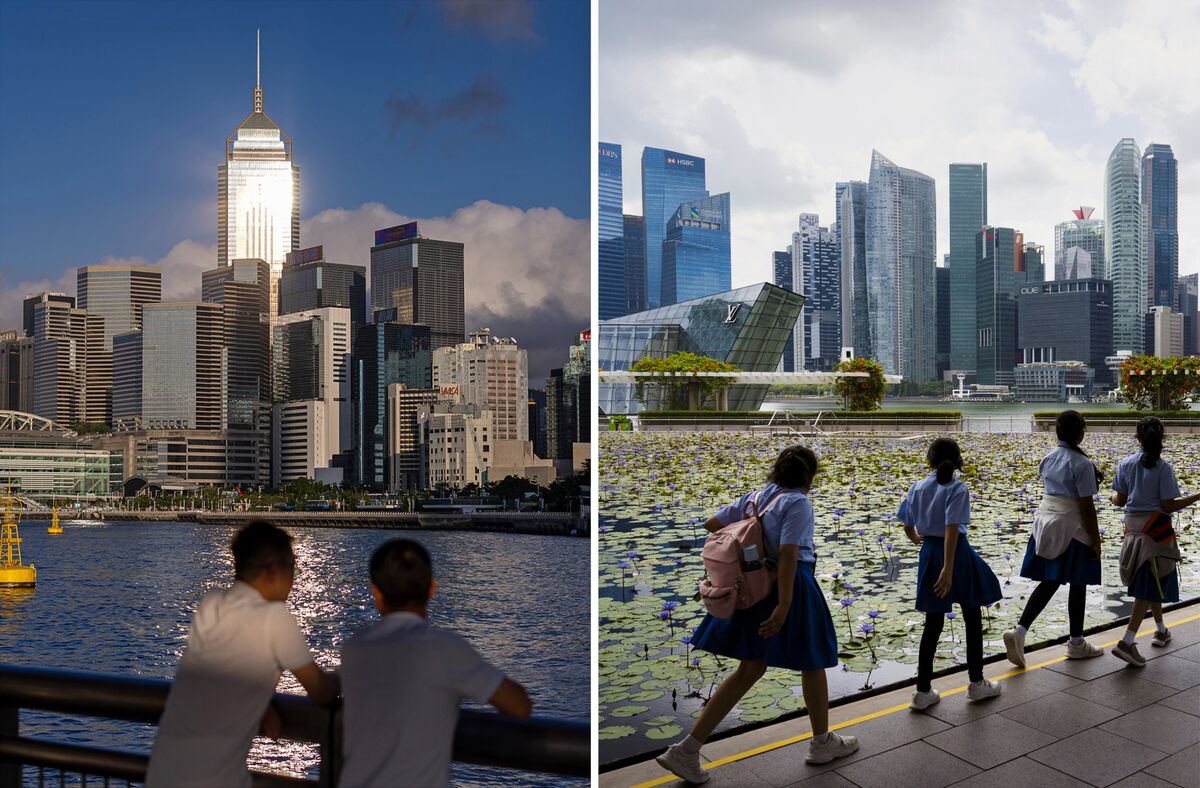
Hong Kong and Singapore are intensifying competition for global financial talent, with both considering tax breaks for fund managers. Expats are returning to Hong Kong while Singapore is becoming more selective, reversing some of the relative dynamics since Bloomberg's 2022 comparison. The developments are relevant to the regional finance-sector labor market but are not yet tied to announced policy details or quantified economic effects.
Analysis
This is a low-immediacy signal for listed equities, but it matters at the margin for the regional asset-management ecosystem. Hong Kong’s relative normalization can improve hiring depth, capital-markets activity and private-wealth inflows, benefiting Hong Kong Exchanges & Clearing (0388 HK) through higher cash-equity, derivatives and IPO turnover. Singapore’s greater selectivity may protect its high-value financial-services tax base, but could redirect incremental mobile talent and family-office formation toward Hong Kong, Dubai and Tokyo rather than create a zero-sum shift.
The investable transmission is primarily through fee pools and market liquidity over 6-18 months, not near-term earnings. A durable pickup in Hong Kong-based fund launches, southbound trading, IPO pipelines and office absorption would be more meaningful for 0388 HK, AIA (1299 HK), and local banks such as HSBC (HSBA LN) and Standard Chartered (STAN LN) than expatriate surveys. Conversely, Singapore’s listed banks—DBS (D05 SI), OCBC (O39 SI), UOB (U11 SI)—remain more sensitive to regional credit quality and rates than to marginal talent-policy changes.
Contrarian view: competition through tax concessions can be value-destructive if it becomes a subsidy race, especially where incremental managers bring limited deployable AUM or generate low local spending. The key falsifier for a constructive Hong Kong liquidity thesis is not relocation announcements: it is a failure of average daily turnover, IPO fundraising and northbound/southbound flows to improve over the next two reporting quarters. No standalone trade is warranted on this item absent evidence that policy changes alter actual AUM, trading or issuance activity.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- Maintain 0388 HK on an event-driven watchlist rather than initiate on talent-policy headlines; consider a 3-6 month long only if Hong Kong cash-market turnover and IPO backlog show sustained sequential improvement. Thesis fails if turnover remains flat despite policy implementation.
- Use a 6-12 month relative-value framework: long 0388 HK versus a basket of Singapore banks (D05 SI, O39 SI, U11 SI) only after confirming Hong Kong liquidity acceleration, since this isolates capital-markets upside from Singapore banks' materially different credit and rate exposures.
- Monitor HSBC and Standard Chartered for private-wealth/AUM commentary and Hong Kong loan-growth trends at the next results cycle; positive hiring rhetoric without disclosed AUM inflows or fee-income growth is not a catalyst.
- Avoid treating a potential tax-break cycle as structurally bullish for either hub until program cost, eligibility, and minimum local-investment requirements are disclosed; aggressive concessions without measurable AUM capture would be negative for fiscal quality and unlikely to re-rate financial-sector multiples.
More News
- Are global oil reserves sufficient to withstand renewed US-Iran war?
- France is flashing euro crisis signals. This time, the fault lines are different
- OpenAI Trims Target Value & Volvo Cars Cuts 2,500 Jobs
- ‘They are trying to intimidate us’: Indonesia’s Prabowo remains defiant in the face of an MSCI double downgrade
- Volvo Cars shares plunge 25% amid China sales slump and fresh job cuts
- US tech stocks tumble as investors fret over AI spending