
Four Seasons Resort Los Cabos at Costa Palmas Unveils Casa Encantada, A Hidden Hacidenta Designed For Celebrations Without Limits
Source: PRWeb
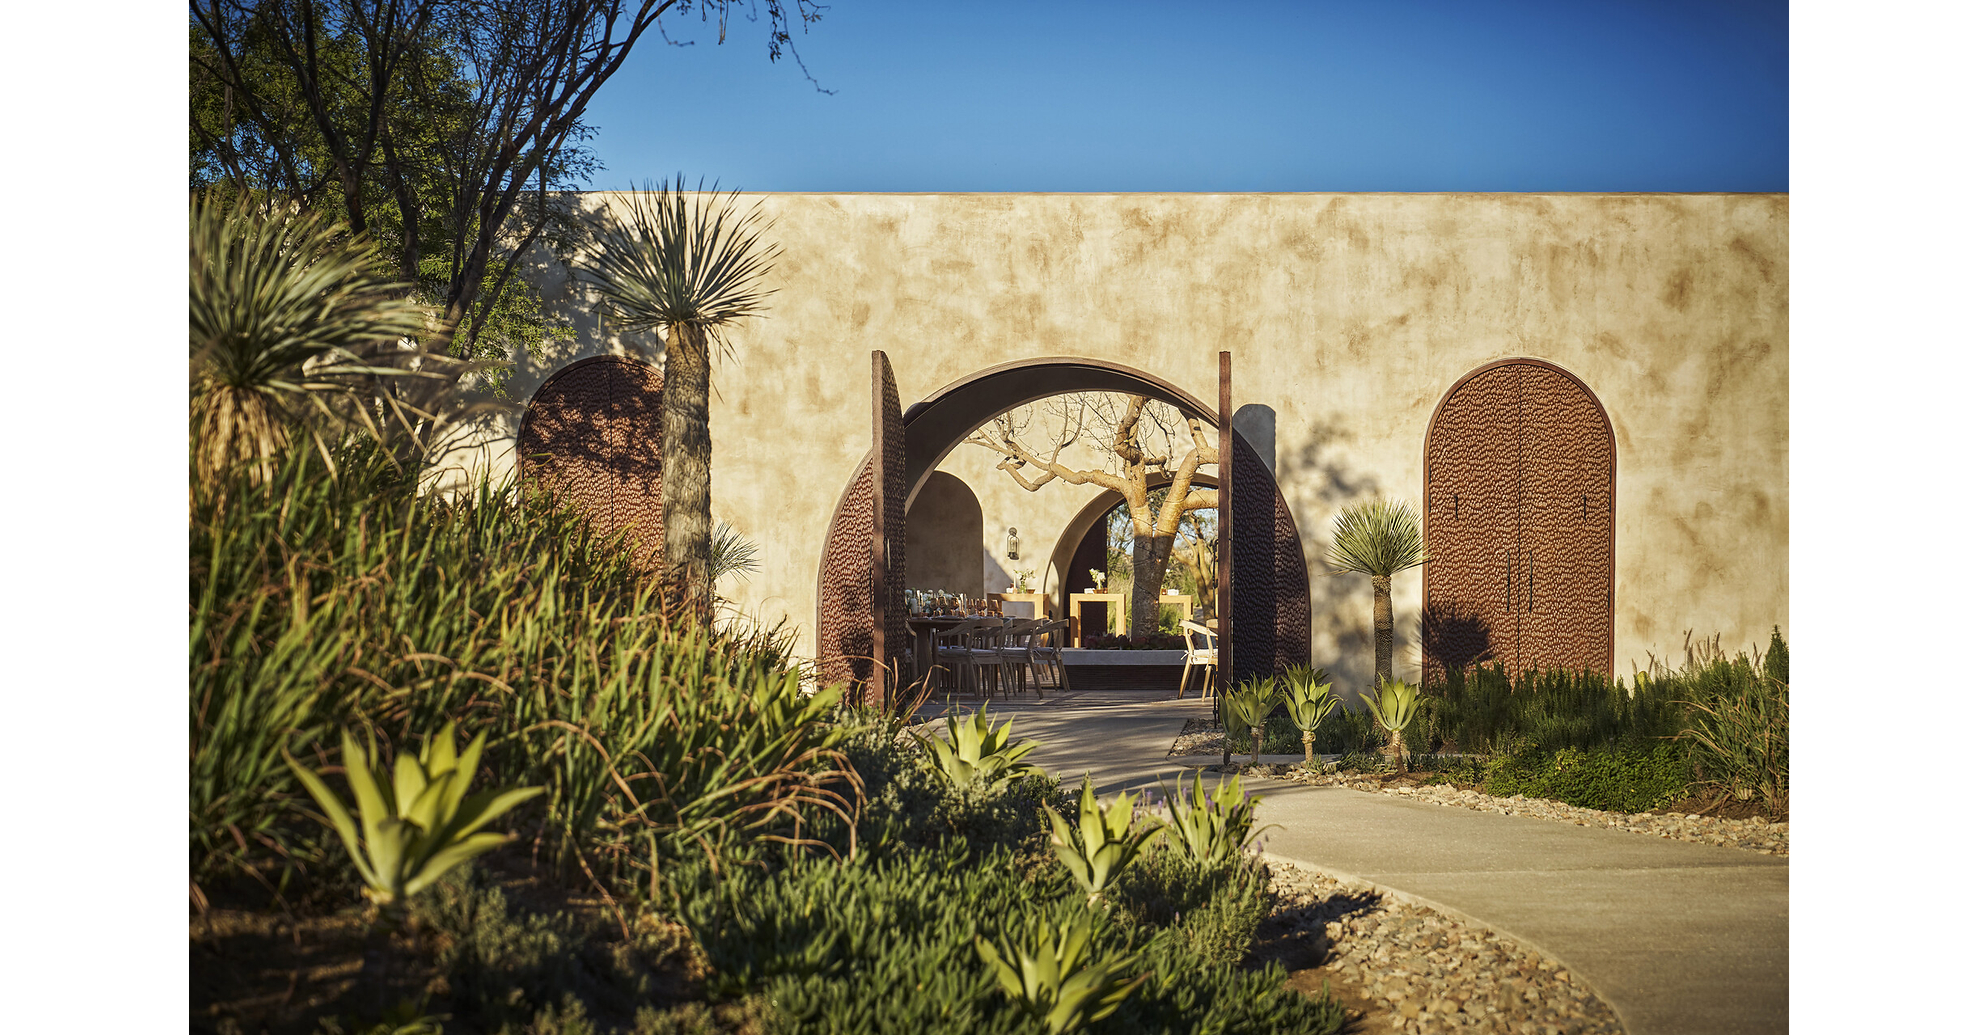
Four Seasons Resort and Residences Los Cabos at Costa Palmas announced the debut of Casa Encantada, the East Cape’s largest dedicated luxury event venue, sized at 2,109 m² (22,710 sq. ft.) with capacity for up to 400 guests. The venue is positioned as a differentiator versus typical Los Cabos event constraints, explicitly offering no curfew or noise restrictions and enabling multi-day setups. The announcement is focused on experiential/tourism offerings rather than financial results, implying limited direct market impact but a positive signal for destination-event demand.
Analysis
This reads less like a standalone earnings catalyst and more like a signal that ultra-luxury resorts are leaning harder into monetizing fixed assets through high-margin event, F&B, and wellness spend. The economic value is not the venue itself; it is the ability to turn otherwise soft shoulder-season inventory into multi-day, premium-priced group buyouts with better ancillary capture than standard leisure stays. If that pattern is real, the best public beneficiaries are the branded full-service luxury operators with pricing power and distribution leverage, not the property-level sponsor named here.
The second-order implication is competitive: destination weddings and brand events tend to migrate toward properties that can solve logistics, privacy, and production friction in one package. That favors curated resort brands versus fragmented villa/rental inventory, and it should support rate integrity in the Cabo luxury comp set if planners view East Cape as a higher-functioning alternative to more crowded corridors. The near-term catalyst is booking commentary, not the announcement itself; we would need evidence of deposit flow, group ADR uplift, or higher spa/F&B penetration to treat this as economically meaningful.
Contrarian view: the market may underappreciate how much incremental profit comes from "experience infrastructure" at the top end of leisure, where a single buyout can move annualized margins more than several transient room nights. But the headline is still mostly marketing until management shows utilization data. The thesis breaks if affluent event demand rolls over, cancellation rates rise, or luxury travel guides soften over the next 1-3 quarters; structurally, a consumer pullback would hit discretionary event spend first and fastest.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Ticker Sentiment
Key Decisions for Investors
- No direct trade in SCPAF off this release alone; treat it as a watch item until management discloses event booking pace, ADR uplift, or ancillary margin contribution. Falsifier: no measurable pickup in group revenue within 1-2 quarters.
- Relative-value long HLT or MAR vs short ABNB over 1-3 months: branded luxury hotels are better positioned to capture high-touch destination event spend than fragmented rentals. Keep size small; reverse if luxury RevPAR guidance slows or ABNB nights growth re-accelerates.
- If wanting cleaner event-leisure exposure, buy HLT on weakness rather than chase the headline. Risk/reward is better on a pullback to prior support than on the news spike; stop if management cuts full-year RevPAR or group booking commentary turns weaker.
- Set an alert on Cabo / luxury resort occupancy and group booking commentary this earnings season. If comp-set ADR or occupancy shows no uplift, assume this venue launch is non-material and fade any event-driven multiple expansion in travel names.
More News
- Christine Lagarde: IMFC Statement
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Apple’s $1,999 iPhone Duo puts the company's status-symbol power to the test
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- 2026 Global Markets Outlook: Asset Allocation After the Great Disconnect
- Fintool Alternatives After the Microsoft Acquisition