
Gemtek und Dixon bauen ihre strategische Zusammenarbeit aus, um das Geschäft mit optischen Verbindungen in Indien auszubauen
Source: PR Newswire
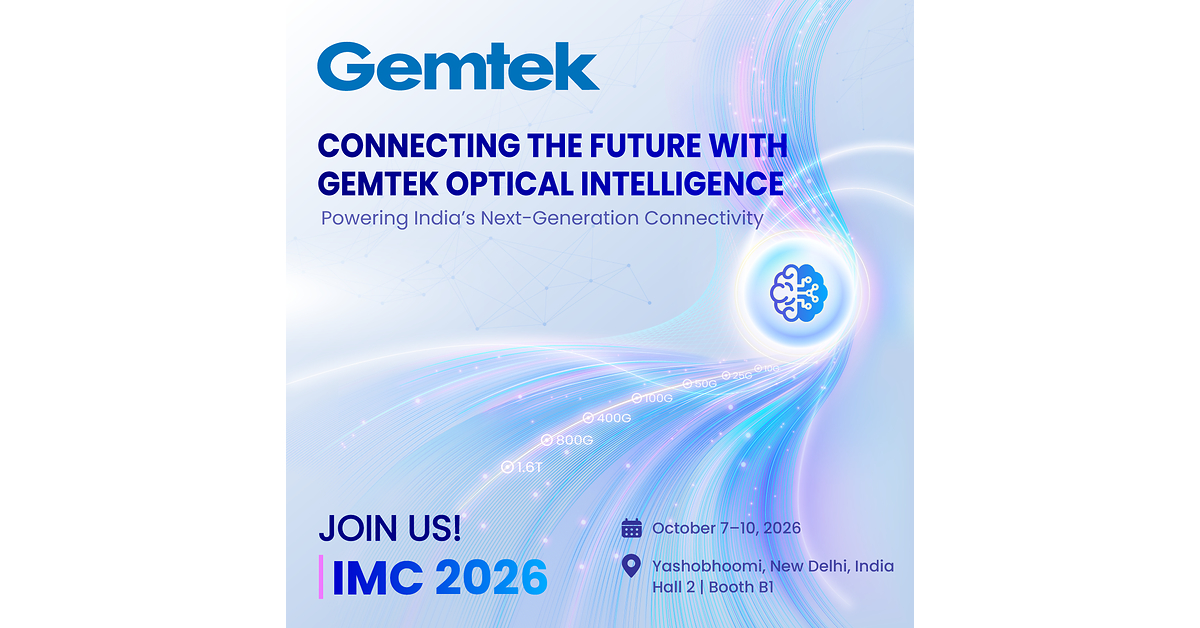
Gemtek und Dixon erweitern ihre strategische Zusammenarbeit in Indien über ihr Joint Venture, um die Fertigung und Marktchancen für optische Transceiver, BOSA und weitere Hochgeschwindigkeits-Optiklösungen auszubauen. Das Portfolio soll von Produkten im Bereich 1G bis 1,6T um Roadmap-Schritte Richtung 800G und 1,6T sowie weiterentwickelte photonische Integrationstechnologien erweitert werden, getrieben durch Nachfrage aus KI-, Cloud- und Rechenzentrumsinfrastruktur. Der Fokus auf lokalisierte Produktion und Lieferketten-Resilienz in Indien erhöht die Skalierbarkeit für Breitband-, Telekom- und Cloud-Anwendungen.
Analysis
The market should treat this less as an immediate earnings event and more as an option on India’s localization push in high-speed optics. The first-order upside accrues to Dixon because it can monetize assembly, testing, and supply-chain orchestration before the technology itself becomes meaningfully commoditized; the bigger second-order winner is the broader India telecom/data-center ecosystem if local content rules or procurement preferences start favoring domestic modules. That said, optical transceivers are a qualification business: without named hyperscale or carrier wins, the near-term revenue contribution is likely immaterial versus the narrative value.
The main competitive implication is that localization pressure could compress margins for imported-module incumbents while shifting bargaining power toward EMS platforms with scale and policy access. If this broadens beyond a single JV, it could pressure smaller regional assemblers and channel demand toward a few qualified manufacturers, creating a winner-take-most dynamic in India. For global peers, the read-through is not a direct demand boom; it is a signal that the 800G/1.6T supply chain is becoming more geographically diversified, which may lengthen lead times for some customers but improve resilience for buyers.
The consensus risk is overestimating timing: design wins in optics can take 6-18 months to convert into meaningful volume, and pricing can be brutally competitive once capacity appears. The thesis is falsified if Dixon fails to announce customer qualifications or order-backed production by the next 2-3 quarters, or if management commentary shows this is still pilot-scale. Conversely, confirmation would be a step-up in India datacenter capex or any government-linked procurement language that embeds local sourcing.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.15
Key Decisions for Investors
- Watchlist, not a size trade yet: initiate only if Dixon Technologies (NSE: DIXON) confirms customer qualification or order visibility; otherwise the risk/reward is mostly narrative-driven and can fade within weeks.
- Tactical long DIXON on any pullback after the press-release pop, but size small and use a 2-quarter thesis window; upside is multiple support from localization optionality, while downside is thesis decay if volumes remain non-committal.
- Pair-trade idea: long DIXON / short a higher-multiple India electronics assembler with less optics exposure if the market starts pricing a broad India capex windfall; exit if Dixon announces no revenue-bearing traction by the next earnings cycle.
- For the broader chain, maintain an alert on Coherent (COHR), Lumentum (LITE), and Applied Optoelectronics (AAOI) only if India localization starts appearing in customer win commentary; otherwise there is no clean immediate read-through.
- Set a falsifier: if management does not convert the partnership into disclosed backlog or volume guidance within 1-2 quarters, fade any valuation premium tied to this announcement.
More News
- One Singapore ship was sunk, but here's why others are still transiting the Strait of Hormuz
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt
- Taiwan to curb AI chip sales to China for more U.S. alignment- Bloomberg
- FDA approves Enspryng for thyroid eye disease treatment
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind's Data Standardization Methodology: Our Approach to Fundamentals
- What Makes Financial Data Ready for AI Research?