
Bitmine Immersion Technologies anuncia que sus tenencias de ETH llegan a 6,02 millones de tokens
Source: PR Newswire
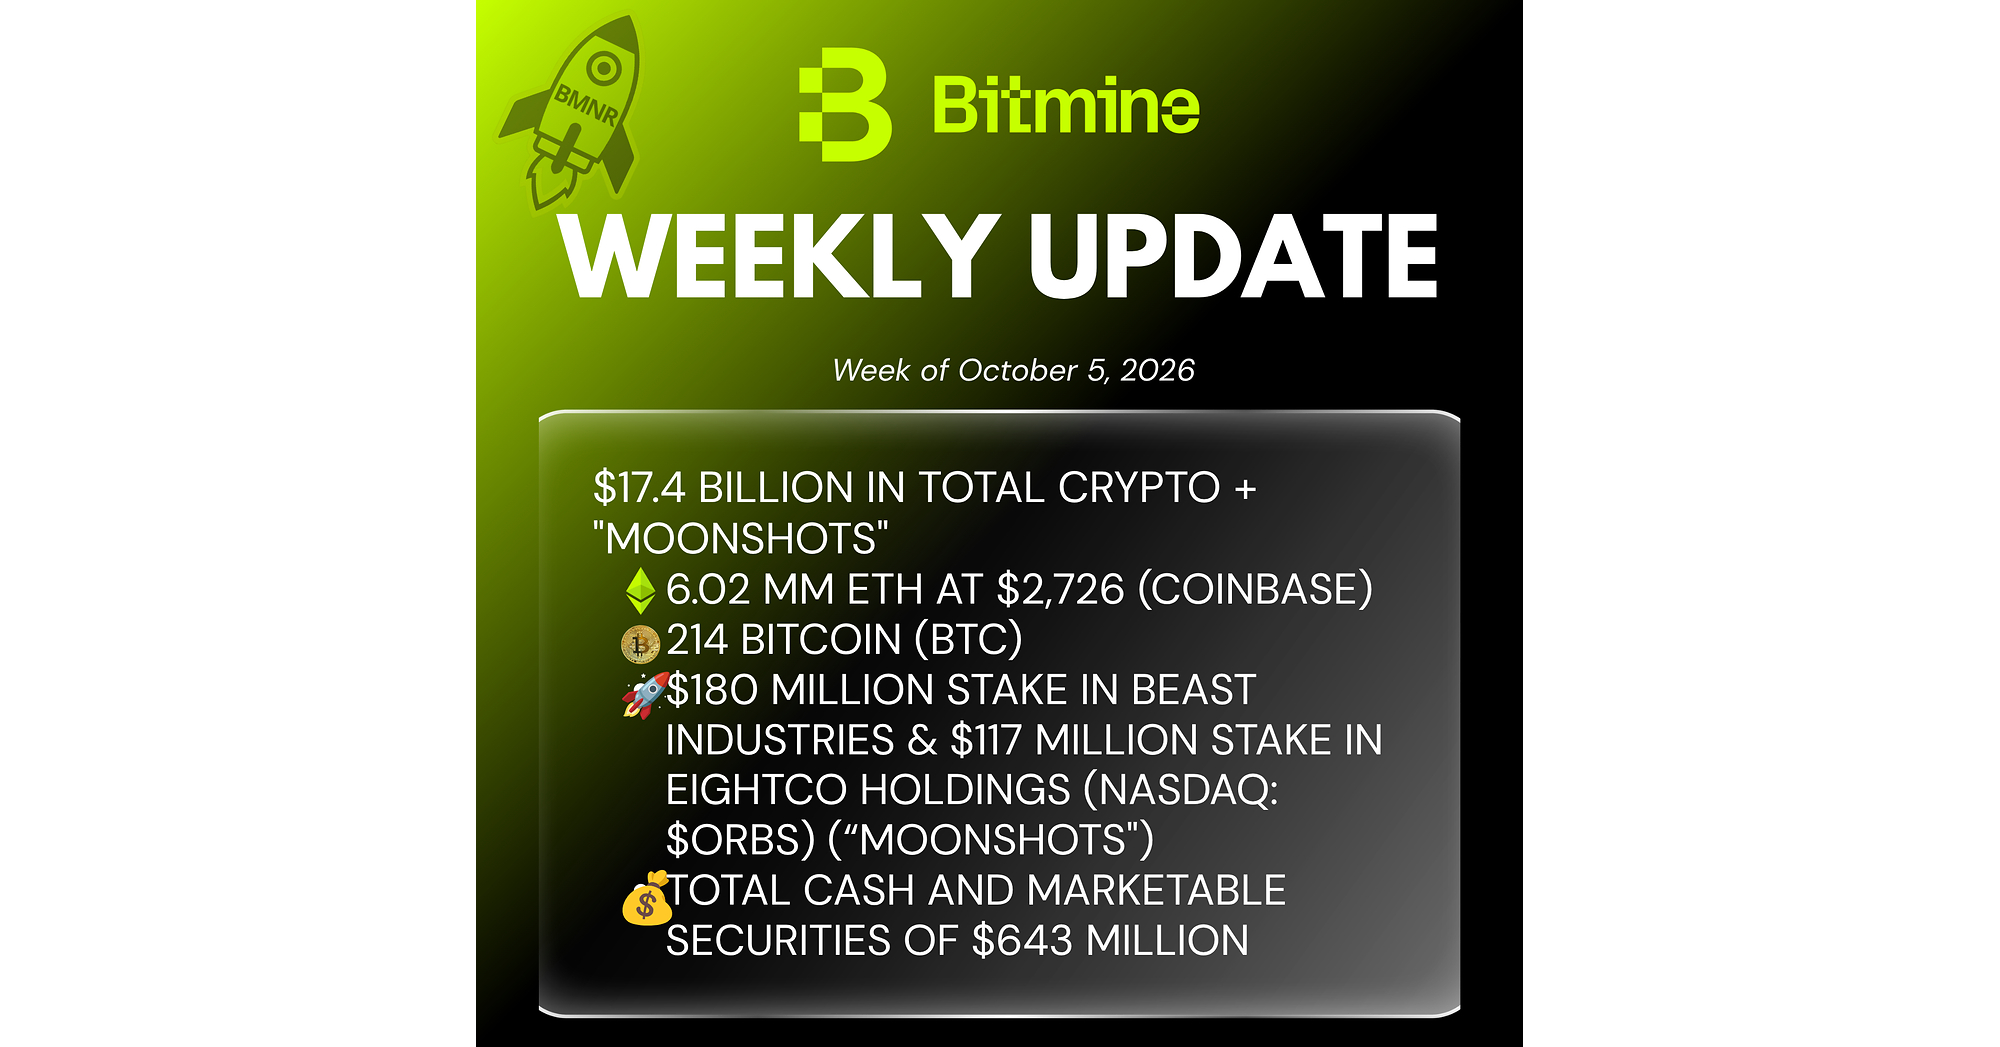
Bitmine reported $17.4 billion in combined crypto, cash, marketable securities and high-risk investments as of October 4, including 6,016,414 ETH valued at $2,726 per token—4.9% of ETH supply. It said 5,067,309 ETH, or 84% of its holdings, was staked, with current annualized staking revenue projected at $363 million and potential rewards of $431 million at scale. Chairman Tom Lee also said Bitmine acquired 17,112 ETH in the past week and bought back 21 million shares in 2026; these figures and projections are company-reported, and the release highlights digital-asset and staking risks.
Analysis
BMNR is best viewed as an ETH treasury vehicle with an added staking-operator option—not as a clean proxy for ETH. Staking can add recurring revenue, but the headline run-rate is not earnings: validate realized rewards, operating costs, custody/validator concentration, and any slashing or withdrawal constraints. With most of the ETH already staked, a sharp drawdown could coincide with reduced liquidity and a widening equity discount to asset value. Conversely, an ETH rally could amplify BMNR if its equity trades at a premium, but that premium is also vulnerable to dilution, capital-structure claims, and a reversal in crypto sentiment.
The main second-order risk is concentration: a very large treasury and staking footprint increases sensitivity to Ethereum-specific protocol, regulatory, and operational events, while potentially intensifying scrutiny of validator concentration. MSTR is not a direct hedge: its treasury exposure is Bitcoin, so a BMNR/MSTR pair is a relative crypto-duration trade rather than a neutral hedge. ORBS exposure is a separate, high-risk mark-to-market position, not a dependable offset.
Near term, verify the source before trading: the release is dated October 6, 2026, one day after the stated current date of October 5. Over 1–3 months, watch ETH, BMNR’s premium/discount to independently calculated NAV, net share issuance versus repurchases, and realized staking income. Over 6–18 months, MAVAN’s third-party customer traction matters more than management’s projected run-rate. The bullish treasury narrative is not independently verified performance; claimed buybacks and staking economics require filing-level confirmation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.35
Ticker Sentiment
Key Decisions for Investors
- No immediate trade until the future-dated release and its figures are verified against SEC filings and the company’s underlying disclosures.
- After verification, consider a conditional BMNR-versus-ETH relative-value position only after calculating NAV per share using current ETH, cash, other assets, liabilities, preferred claims, and fully diluted shares. Avoid a price target without those inputs.
- Watch for a BMNR premium to NAV expanding materially faster than ETH; that would favor trimming or a defined-risk short against ETH exposure. Falsify the bearish relative-value view if verified buybacks reduce share count and realized staking earnings rise while the premium remains supported.
- Monitor ETH drawdowns, realized staking yield, validator concentration or slashing events, and regulatory action on staking. A deterioration in any of these would challenge the incremental value attributed to MAVAN and could widen BMNR’s NAV discount.
More News
- Cramer is closely watching Nvidia's massive buyback. Here's what he wants to see
- How Hyperliquid defied crypto’s DAT death spiral—and built the industry’s only flourishing digital asset treasury
- Why is Bristol-Myers Squibb stock sliding today?
- Bitmine reports $17.4 billion in crypto and cash holdings
- Security researcher claims to they found KVM guest-host escape flaw
- CH Robinson to Buy RXO for $5.8B in Bet on AI Model