
Odyssey Energy Solutions Raises $74 Million to Accelerate Distributed Renewable Energy Financing in Emerging Markets
Source: PR Newswire
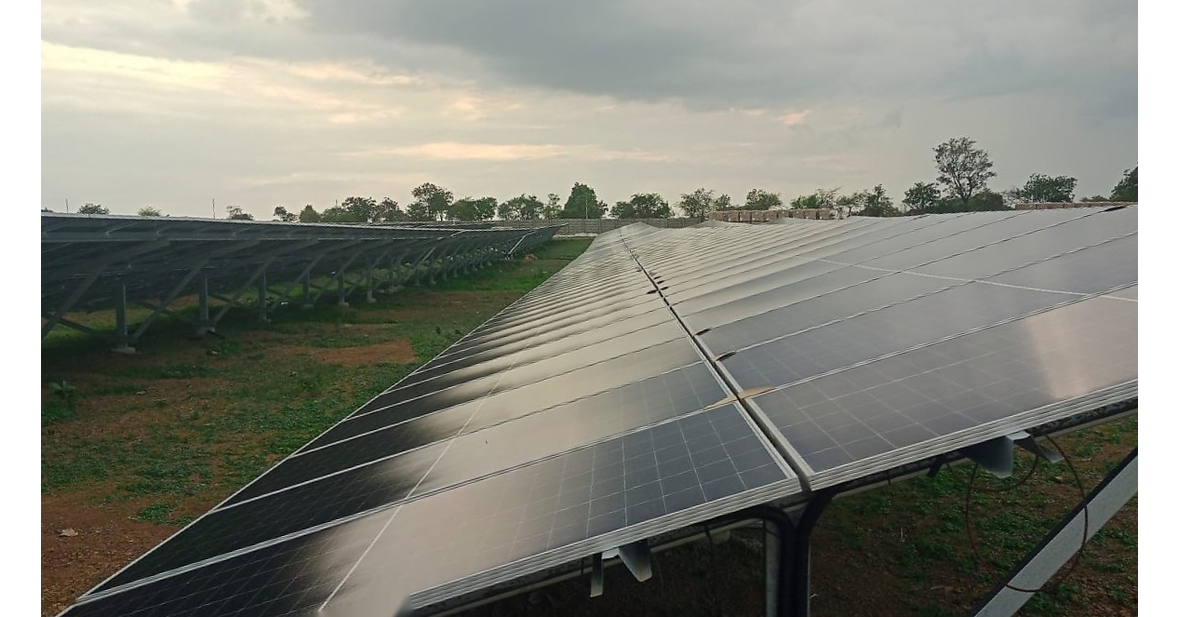
Odyssey Energy Solutions raised $74M ($27M equity, $47M debt) to expand distributed renewable energy financing across Asia, Africa, and Latin America. The platform connects 6,000+ installers/EPCs and has unlocked 1.5 GW of projects, enabling access to $3.6B in capital for distributed energy. Management cites tightening unit economics (falling solar/battery costs) and rising backup/fossil costs (e.g., diesel up 93% in Nigeria) plus policy/supply-chain shifts in India, positioning the company to accelerate deployment.
Analysis
The economically relevant winner is the financing/working-capital layer, not the project developer. In capital-constrained emerging markets, that tends to shift value from commoditized hardware toward whoever controls receivables, procurement terms, and installer access; over time it can consolidate the channel and force smaller EPCs into lower-margin, higher-turnover behavior. That is constructive for scaled, standardized solar ecosystems and negative for fragmented local distributors that cannot self-fund inventory.
Near term, this is more of a sentiment confirmation than a direct earnings catalyst for public equities. The actionable catalyst path is 1-3 months: sustained diesel/backup-power stress, India order growth, and evidence that procurement-credit availability is actually converting backlog into installs. If fuel prices ease, EM FX weakens, or working-capital delinquencies rise, the thesis weakens quickly because the affordability edge is mostly a spread trade versus local fossil backup.
Contrarian view: the market may be underestimating underwriting risk and overestimating the durability of the demand boost. Platforms like this can become throughput machines until credit losses or supplier bottlenecks force tighter standards, which would slow growth before it becomes broadly visible in public comps. The more durable long-term beneficiary is not “solar” broadly, but companies with financing, distribution, and inventory discipline; the weakest link remains small installers and diesel-reliant backup ecosystems.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
strongly positive
Sentiment Score
0.55
Ticker Sentiment
Key Decisions for Investors
- No immediate broad beta trade: hold off on chasing TAN/ICLN here; use this as confirmation only if subsequent India/Africa demand data stays strong over the next 1-3 months.
- Relative-value idea: long FSLR or ENPH vs short CMI on a 3-6 month horizon to express distributed-solar adoption against diesel backup-power exposure; thesis breaks if diesel prices fall sharply or EM credit conditions tighten.
- Watch item, not trade yet: monitor India solar order growth, EMFX, and any evidence of platform credit losses/receivables stretch; those are the fastest falsifiers of the financing thesis.
- If the sector re-rates, prefer the largest balance-sheeted solar suppliers over small-cap installers; the procurement-credit layer should compress margins at the bottom of the chain before it expands them.
More News
- Which stocks will benefit from AI power demand going nuclear?
- Indonesia stocks suffer biggest daily slump since 1998 as MSCI weighs downgrade
- One Singapore ship was sunk, but here's why others are still transiting the Strait of Hormuz
- Order to limit Starshield for Ukraine came from inside White House: Reuters reports
- The IPO drought is driving private equity-owned companies to the debt market to pay investors
- CoreWeave credit default swaps hit distress levels as investors sour on AI debt