
Presidential Heating & Air Conditioning Acquires Shipley, Expanding Plumbing and Whole-Home Services Across Montgomery County
Source: PR Newswire
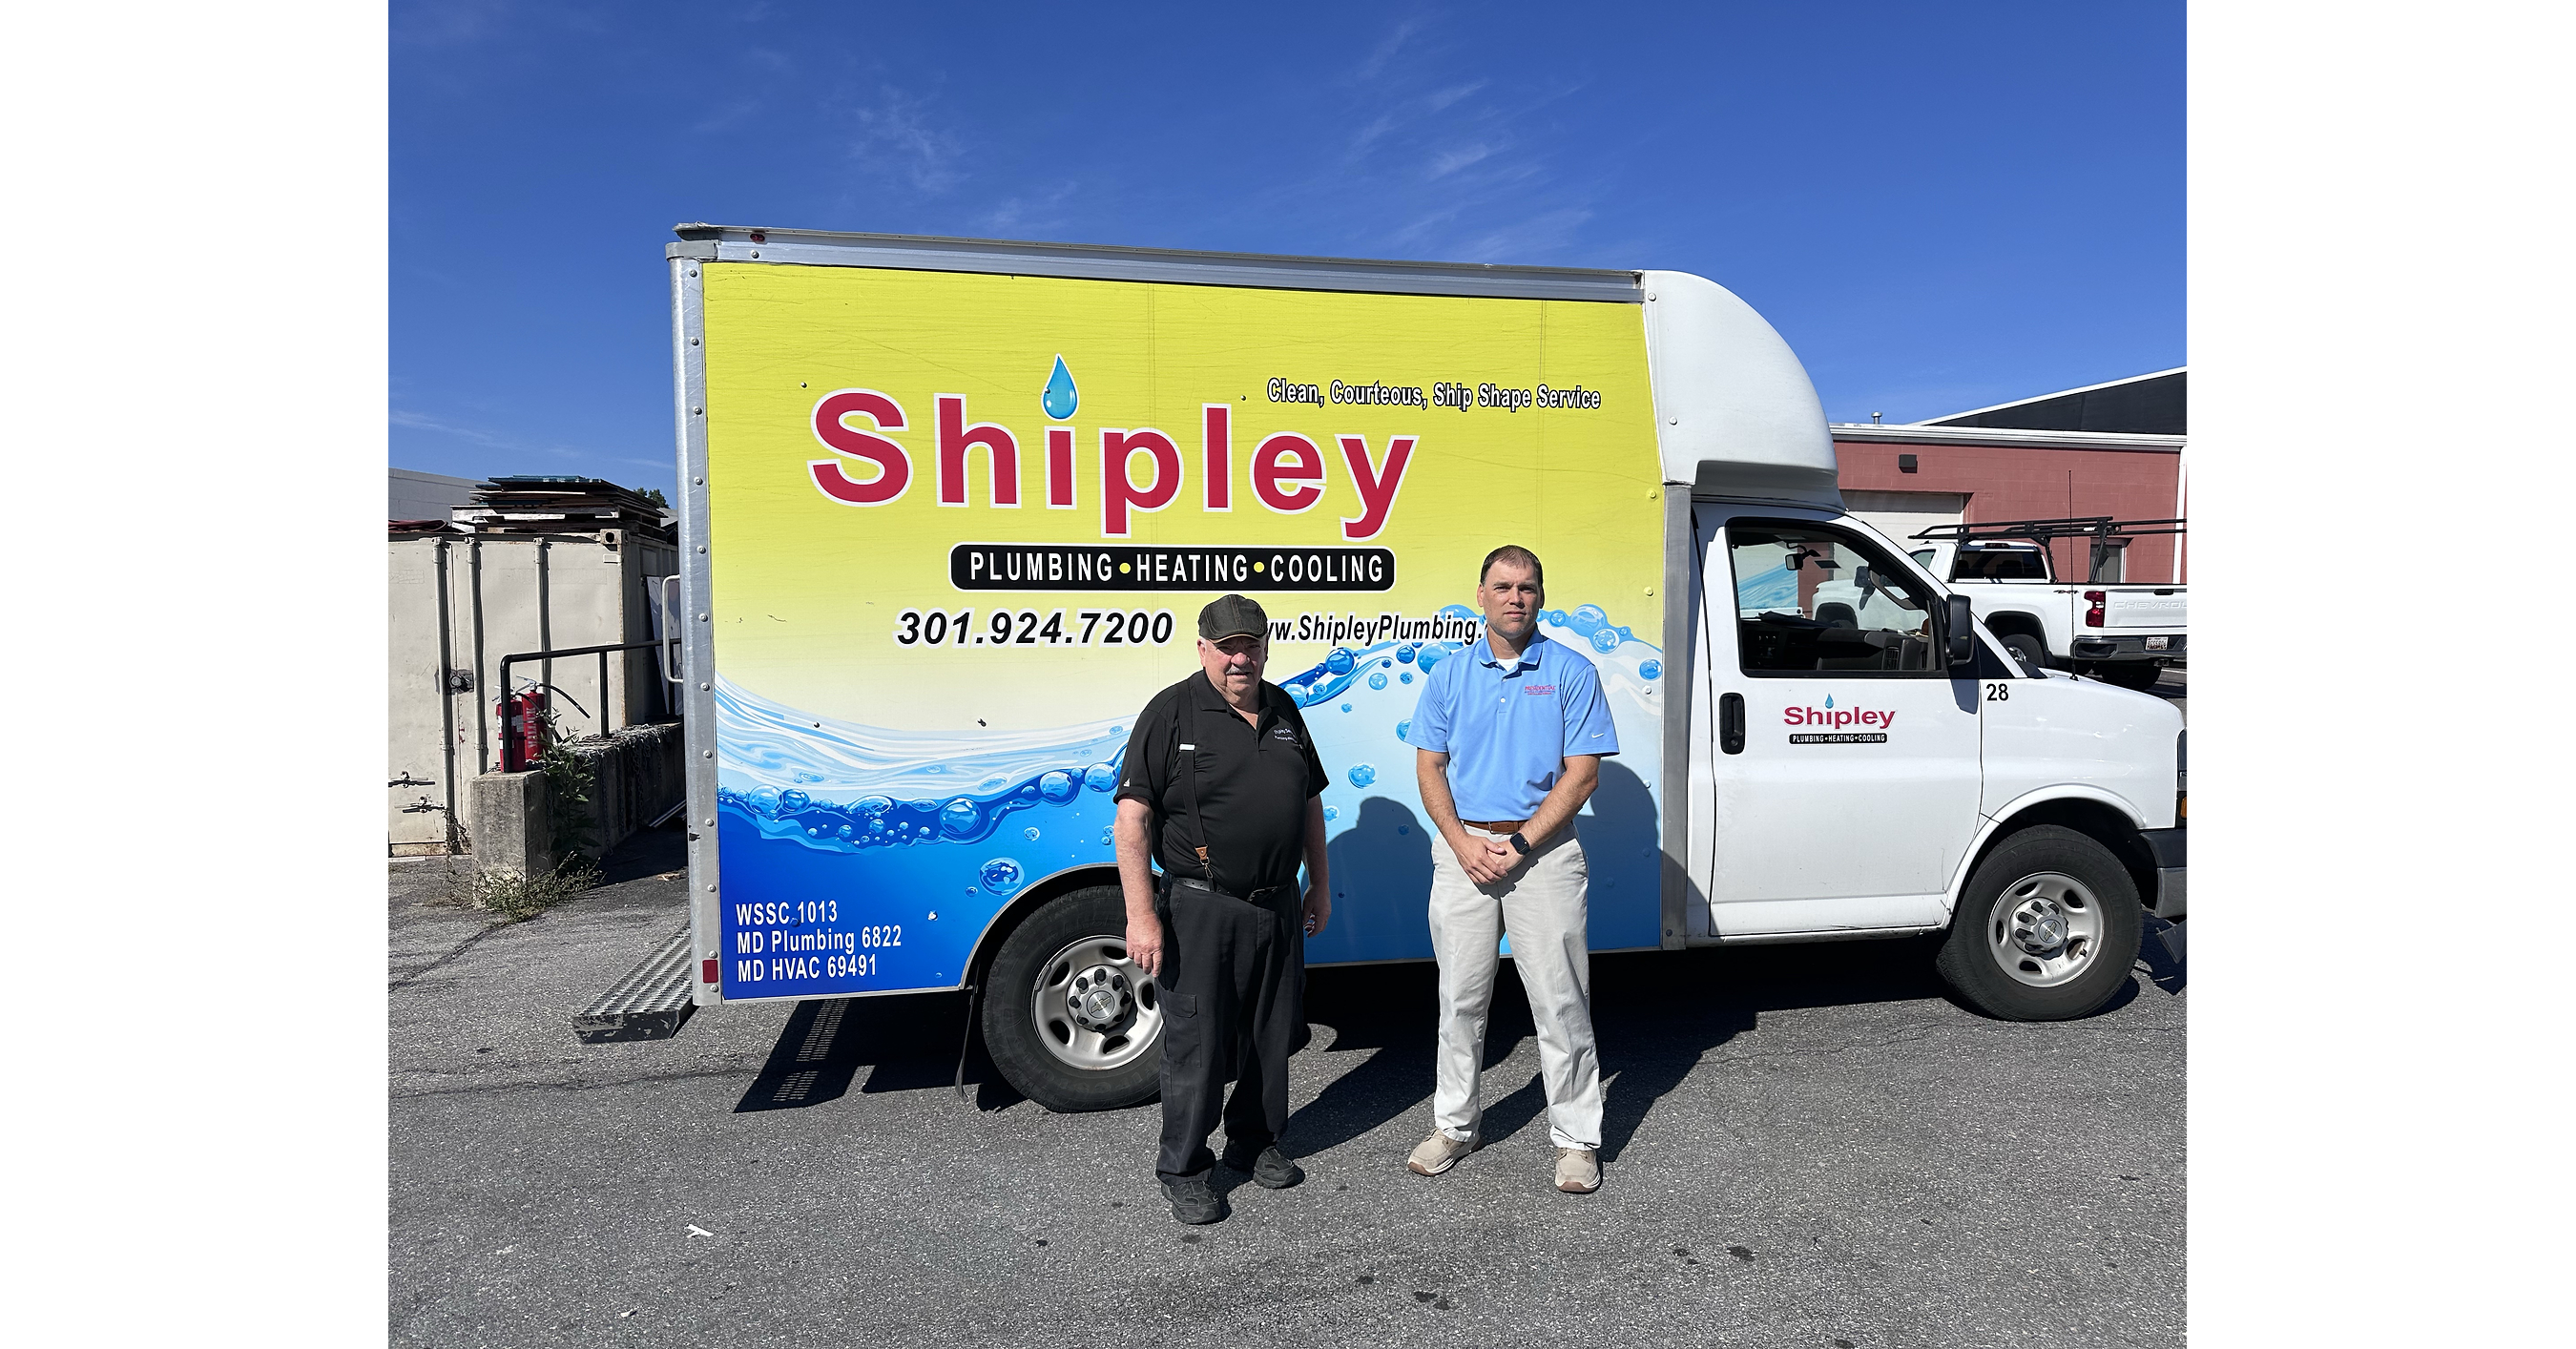
Presidential Heating & Air Conditioning (part of Southern Home Services) announced it acquired Shipley Plumbing, Heating & Air Conditioning effective Aug. 24, 2026, with Shipley customers transitioning under the Presidential name. The deal expands Presidential’s home-comfort offering to plumbing, drain clearing, water heater maintenance, repair/replacement, and fixture installation, while aiming to preserve Shipley’s local service model. The acquisition supports Southern Home Services’ strategy to strengthen its Centers through complementary local partnerships, with customers continuing to request service via familiar channels.
Analysis
This is economically a route-density and cross-sell story, not a headline revenue story. The value creation sits in higher average ticket, better technician utilization, and lower customer-acquisition cost once plumbing is sold into an existing HVAC base; that tends to lift EBITDA margins more than top-line growth over 6-18 months. The second-order benefit is reduced seasonality: plumbing repair/replacement and drain work can offset weather-driven HVAC swings, which supports a higher private-market multiple if retention holds.
For public comps, the cleanest read-through is to suppliers and distributors that benefit from more frequent repair/replacement cycles, especially FERG and WSO, but the impact from one tuck-in is immaterial. The loser set is fragmented local independents that lack a bundled service offering; over time, those operators face pressure on pricing and call-center efficiency, especially if Southern Home Services proves it can replicate this model across other Centers. Any benefit to SO or SCI is too indirect to underwrite as a trade.
The contrarian view is that investors often overpay for “platform synergy” before proving technician retention and same-store cross-sell. Most residential-services roll-ups look good in the first quarter and then leak value through turnover, integration friction, and higher warranty callbacks; the real test is not the acquisition announcement but whether revenue per truck and margin per branch improve over the next 2-4 quarters. If the next filings do not show those metrics inflecting, this should be treated as financial engineering rather than durable compounding.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.12
Ticker Sentiment
Key Decisions for Investors
- No trade in SO or SCI on this announcement; the linkage is too weak and the transaction is too small to justify risk.
- Set a 90-day watch on FERG and WSO for any measurable uptick in professional-channel demand from residential repair/replacement; only add exposure if multiple roll-ups signal a broader attach-rate inflection.
- If Southern Home Services continues serial acquisitions, consider a relative-value long on scaled distributors/suppliers (FERG, WSO) versus a home-improvement beta basket, but wait for evidence of real cross-sell before entering.
- Falsify the bullish private-market thesis if retention or margin metrics fail to improve in the next 1-2 quarters: revenue per truck, EBITDA margin, or customer churn would be the key alert points.
More News
- Why is T-Mobile stock tumbling today?
- Why is Verizon stock sliding today?
- SpaceX wants to become a 'major mobile carrier' with low-band spectrum acquisition
- OpenAI projected to bring in $20bn less in revenue than expected
- Soitec climbs 7% as BofA turns bullish on silicon photonics demand
- Schott Pharma drops after Deutsche Bank downgrades on demanding valuation