
Equisoft appoints Bob Thrall as Chief Sales Officer
Source: PR Newswire
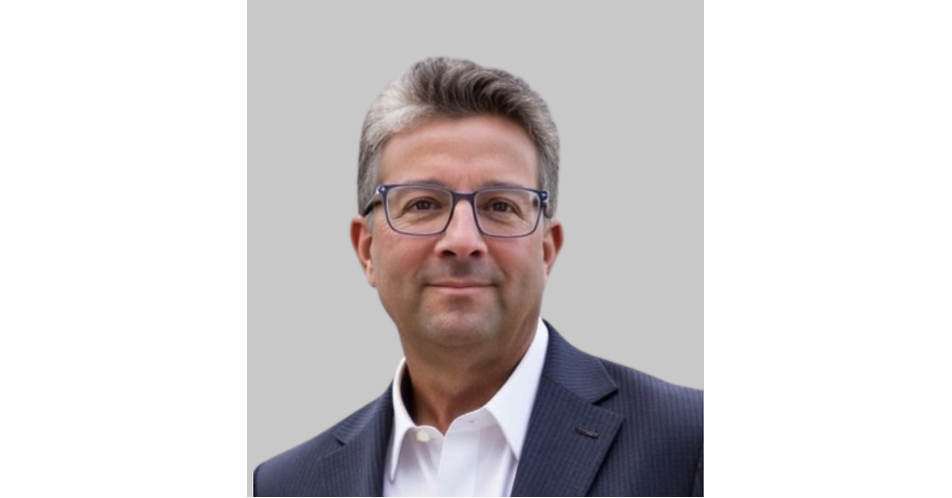
Equisoft appointed Bob Thrall as Chief Sales Officer, tasking him with scaling global sales and pre-sales across insurers, distributors, and financial institutions. The company links the hire to accelerating growth and supporting its AI-focused innovation, emphasizing helping life insurers modernize legacy systems and reduce operating costs. No financial figures or guidance changes were provided, so the near-term impact is likely limited.
Analysis
This reads less like a catalyst for public-market pricing and more like a go-to-market check on whether a private insurance software vendor can actually convert AI/modernization demand into bookings. The economic effect, if real, would show up first in pipeline velocity and partner-led implementation revenue, not in immediate margin expansion; that makes it a 1-3 quarter story at best. For listed equities, the more relevant implication is budget reallocation inside life insurance IT: more spend toward modernization/implementation partners and less toward maintaining legacy admin stacks.
The second-order winners are not the insurers themselves, but the vendors and integrators that sit closest to data migration, workflow automation, and core conversion. That tends to favor large-scale services/platform names with sticky enterprise footprints, while smaller point-solution vendors risk being squeezed if buyers standardize on fewer platforms. The loser set is usually legacy outsourcers and niche middleware providers whose value proposition disappears once carriers decide to consolidate vendors rather than add another layer.
The contrarian issue is that insurance buying cycles are slow and political; a sales hire does not shorten procurement, integration risk, or regulatory review. In that sense, the market may be overestimating near-term AI-driven uplift in this vertical: the real constraint is not selling the vision, it is migrating policy/admin data without operational disruption. If we do not see booking acceleration or disclosed carrier wins within 1-2 quarters, this should fade as a signal rather than a tradeable trend.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No direct trade in FISI/GAP/GDSI; there is no identifiable economic linkage, so the right decision is to avoid forcing exposure.
- Watchlist: SSNC and ACN for any insurance-modernization commentary over the next 1-2 earnings cycles; only take a long if management cites measurable pipeline or backlog acceleration in insurance IT.
- If you want to express the theme, prefer a long SSNC / short lower-quality IT-services basket on any pullback, but only after confirmation from bookings data; without that, the signal is too weak to size.
- Set a falsifier: if insurer IT budgets do not reaccelerate in Q1-Q2 updates or if carrier deal cycles remain flat, treat the AI/modernization thesis as promotional and exit any thematic longs.
More News
- Christine Lagarde: IMFC Statement
- Palantir patient data tech rejected by many NHS trusts in England
- Why did CoreWeave stock get crushed this week? Look to this corner of the debt market for clues
- Diageo's Toxic Spill Hits Pristine River in Scottish Whisky Country
- AI stock sell-off ramps up over debt-fueled data center spending fears: ‘Full-blown crisis of confidence'
- Wall Street Anxiety Spreads as AI Rout Meets $110 Oil Shock
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AI Vendor Landscape for Institutional Investment Teams
- AllMind Fixed Income Compass for October 2025: Navigating Policy Divergence and Political Risk