
The NHP Foundation Closes Financing on The Bella, Expanding Affordable Housing in Frisco, Colorado
Source: PR Newswire
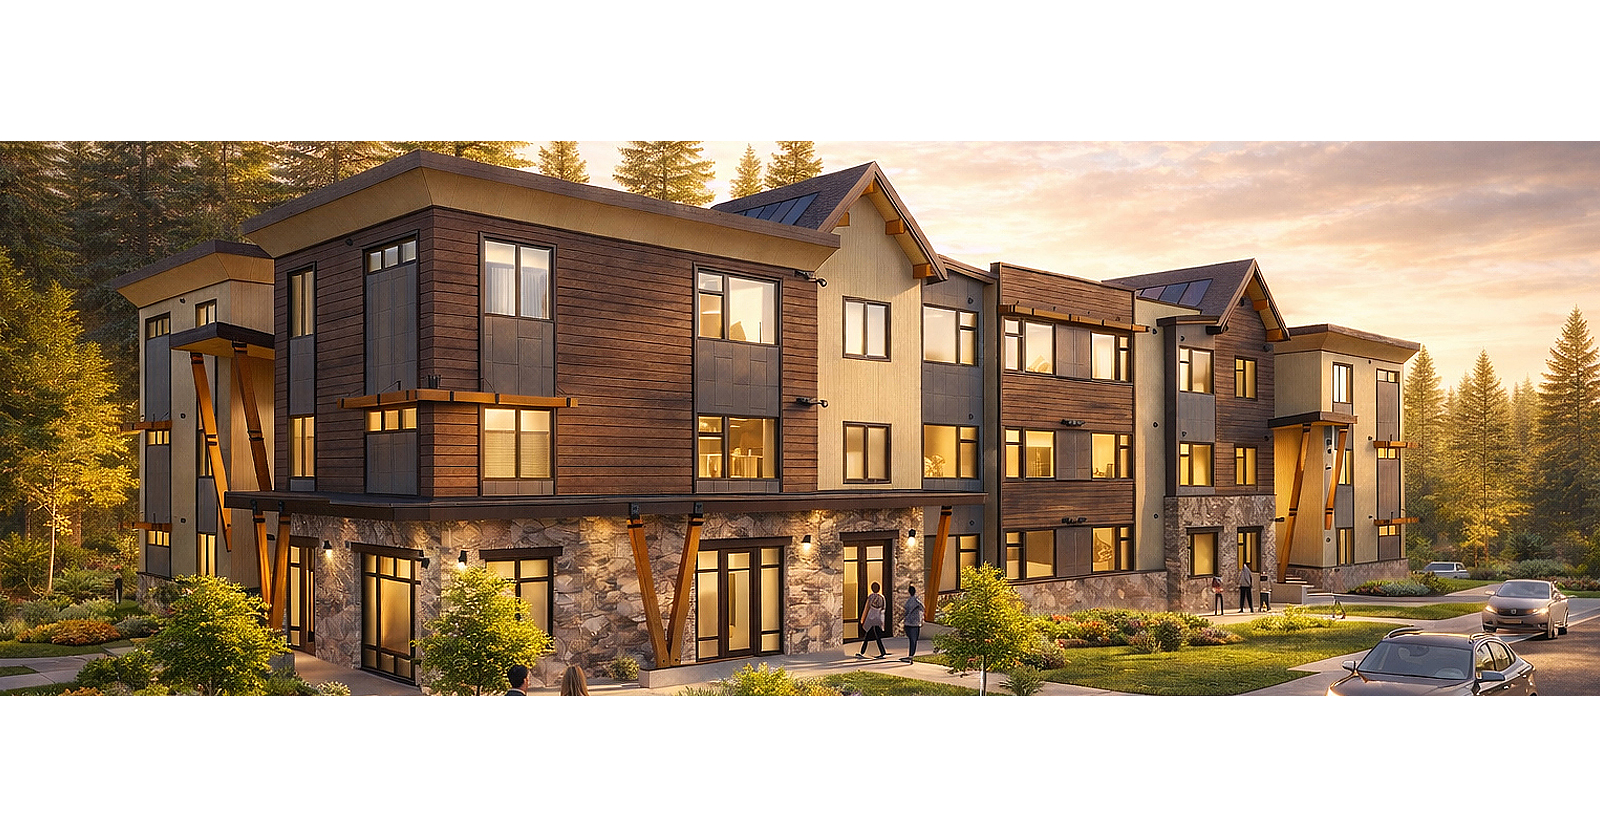
NHP Foundation (NHPF) closed financing for The Bella, a 52-unit affordable housing development in Frisco, Colorado—its first Low-Income Housing Tax Credit (LIHTC) project in the state. The deal uses 9% federal LIHTCs plus Colorado state LIHTCs and includes U.S. Bank construction financing, Cedar Rapids Bank & Trust permanent financing, and state grants (including Proposition 123 land banking and infrastructure grants), with completion expected in November 2027. Frisco’s Town contributed about $4.9 million in soft financing and secured a property tax abatement, supporting an estimated average affordability of ~60% AMI across units.
Analysis
This is a signal about capital availability, not about near-term housing economics. The real winners are the banks and intermediaries that can warehouse tax-credit risk and earn fee income from layered public finance structures; those businesses get incremental pipeline when state grants, land banking, and tax abatement close the financing gap that high rates otherwise would have broken. The loser set is local market-rate landlords and landowners in tight resort towns: every subsidized unit is small in isolation, but over time these projects create a political template that can restrain rent growth expectations and reduce the scarcity premium on workforce housing.
The important second-order effect is that Colorado is effectively de-risking LIHTC execution with public capital, which should keep deal flow alive even if construction debt stays expensive. That is constructive for banks with affordable-housing syndication franchises and for contractors with public-sector backlog, but it is not a revenue event for the named tickers here; the project is too small to move earnings or valuation for FISI, STT, or the others. The completion timing also matters: the economic impact is back-half 2027, so the market should treat this as a pipeline indicator, not an immediate catalyst.
Contrarian view: consensus tends to over-interpret these closings as evidence of broad housing relief. The actual bottleneck is still zoning, land, and execution risk; if rates stay elevated or tax credit pricing softens, a lot of headline affordable supply never reaches completion. What would falsify the constructive read is a sustained drop in LIHTC spreads, a pullback in Colorado state housing funding, or repeated project delays/overruns that make the public-private stack less replicable.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No immediate trade in FISI, GAP, SCPAF, or STT on this headline alone; the unit economics are too small to change earnings expectations, so treat it as a confirmation of policy support rather than a catalyst.
- If expressing the theme, monitor and potentially add to bank exposure with meaningful LIHTC/muni-finance franchises (e.g., USB, PNC, FITB) on pullbacks; the setup is modestly positive over 3-12 months as fee income and construction lending remain supported.
- Set an alert on LIHTC pricing and Colorado housing-fund allocations over the next 1-3 months; a weak tax-credit market or budget pullback would be the clearest falsifier for the pipeline thesis.
- Avoid shorting market-rate apartment REITs or homebuilders on this news; the supply impact is too localized and delayed to justify a macro housing short.
More News
- Gap chief legal officer Julie Gruber sells $648,679 in stock
- Musk says Terrafab chip factory could outperform rivals despite challenges
- CBO chief warns it’s ‘probably not plausible’ that a strong economy alone can steady U.S. debt as 5%-6% growth is needed—more than Bessent’s 3% view
- Nvidia GPUs are everywhere. Here are the ways companies are accessing them
- Will Warner Bros. kill Skydance — or will David Ellison kill Warner Bros?
- Last-Minute Lawsuit Upends Cable One’s $480 Million Mega Broadband Deal
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AlphaSense Pricing: What Public Contract Data Shows in 2026
- Eli Lilly Q4 2025 Earnings: Revenue Surges 43% as Mounjaro and Zepbound Dominate the GLP-1 Market