
Next Africa: Gold Keeps Flowing From Countries With None
Source: Bloomberg
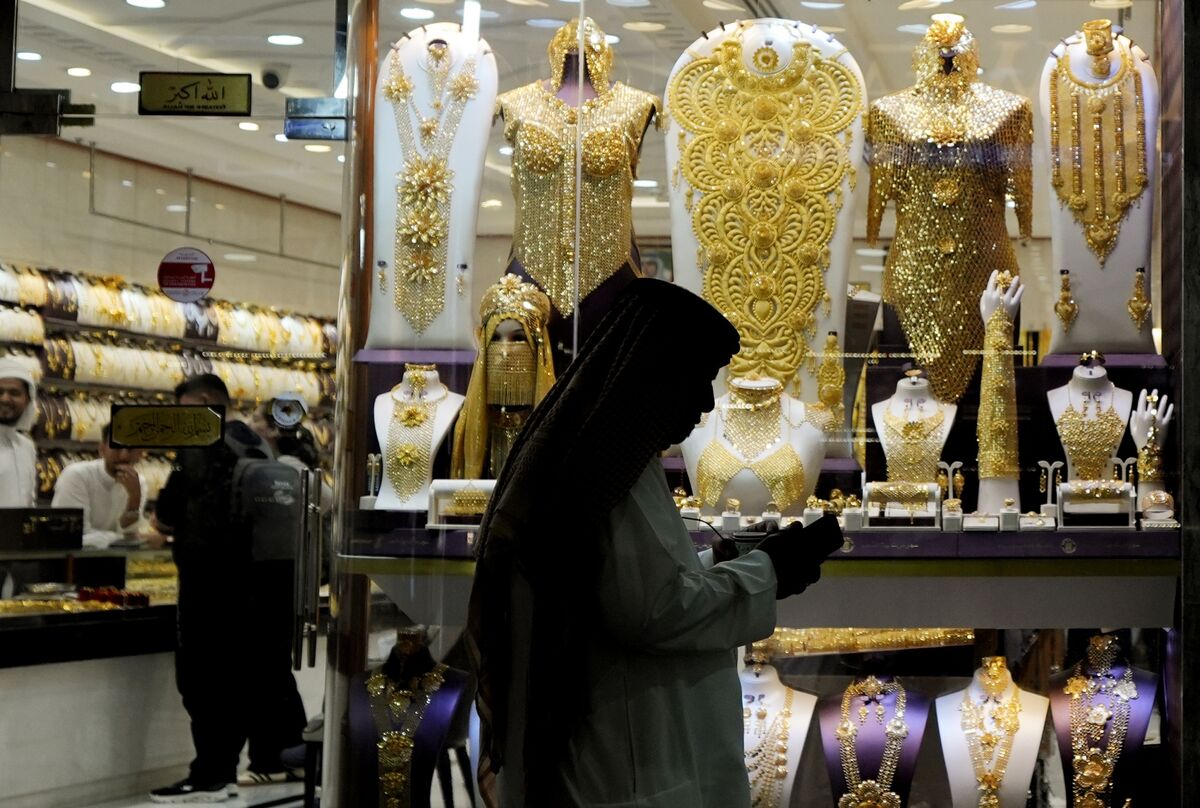
Bullion exports reached record levels in several African countries that do not mine gold, as investors drove gold prices to all-time highs. The price surge prompted Africans to sell gold holdings, increasing cross-border bullion flows and export activity.
Analysis
The investable implication is less about incremental global mine supply than about where high prices are pulling metal out of informal inventories and into export channels. That supply is likely recycled jewelry, artisanal output routed through intermediaries, or trade-finance arbitrage; it should not be modeled as a durable production increase for listed miners. For GOLD, AU, GFI, HMY and AEM, the near-term effect is neutral-to-modestly negative only if elevated local liquidation narrows regional doré premiums or reduces refinery feedstock competition, but the global bullion market is too deep for these flows alone to alter realized pricing materially.
The more consequential second-order risk is regulatory. Rapidly rising bullion exports from jurisdictions without a corresponding mining base are a classic trigger for enhanced AML/KYC scrutiny, customs audits, sanctions enforcement and tighter bank financing. Over 1-3 months, any enforcement action could disrupt working capital for regional traders and temporarily divert physical flows toward Dubai and Switzerland; over 6-18 months, formalization could raise traceability costs and favor large, certified producers such as AU, GOLD and GFI relative to artisanal supply chains.
Consensus may incorrectly read export records as evidence that Africa is adding meaningful new bullion supply just as investment demand is strong. Instead, high prices are incentivizing inventory monetization and cross-border routing, a price-sensitive source that can reverse quickly if bullion falls or local currency conditions change. The relevant macro signal is whether this coincides with broad ETF inflows, central-bank purchases and declining above-ground inventories; without that confirmation, there is no basis to extrapolate a tighter or looser global gold balance from the trade data alone.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.25
Key Decisions for Investors
- No directional trade solely on the export-flow story; treat it as a due-diligence alert rather than a supply forecast. Monitor LBMA/Swiss import data, UAE-Africa trade statistics and regional physical premiums over the next 1-3 months for evidence that flows are large enough to affect refined-market balances.
- Maintain preference for large, traceable producers AU and GOLD over higher-jurisdiction-risk African gold exposure if bullion remains elevated for 6-18 months. Formalization and compliance costs would disproportionately pressure informal supply, while certified producers can gain buyer access and potentially stronger realized-price differentials.
- For existing GLD or GDX longs, use a sustained fall in physical premiums alongside rising scrap/recycled supply as a trim signal; that combination would indicate price-induced inventory liquidation is offsetting investment demand. Conversely, continued ETF inflows and firm premiums would falsify the bearish supply interpretation.
- Watch for named customs, AML, or sanctions actions involving regional bullion hubs. A confirmed enforcement event would support a short-term long AU/GOLD versus HMY or a broad African-risk proxy, but the trade requires confirmation because the affected counterparties and financing exposure are not identified in the available data.
More News
- Trump says Iran war could end after U.S. elections as Hormuz tensions persist
- EM Assets Find Relief as US Jobs Data Eases Rate Fears
- The next weak link in Europe’s bond market? UBS has a new short position
- G7 Leaders’ Statement on global energy security and market stability
- Trump vs Europe as US presses for release of emergency diesel stocks
- EU Faces Trump Pressure to Release Fuel Reserves as Diesel Price Rises