
Miral Invests AED 12 billion to Shape the Next Phase of Yas Island's Growth
Source: PR Newswire
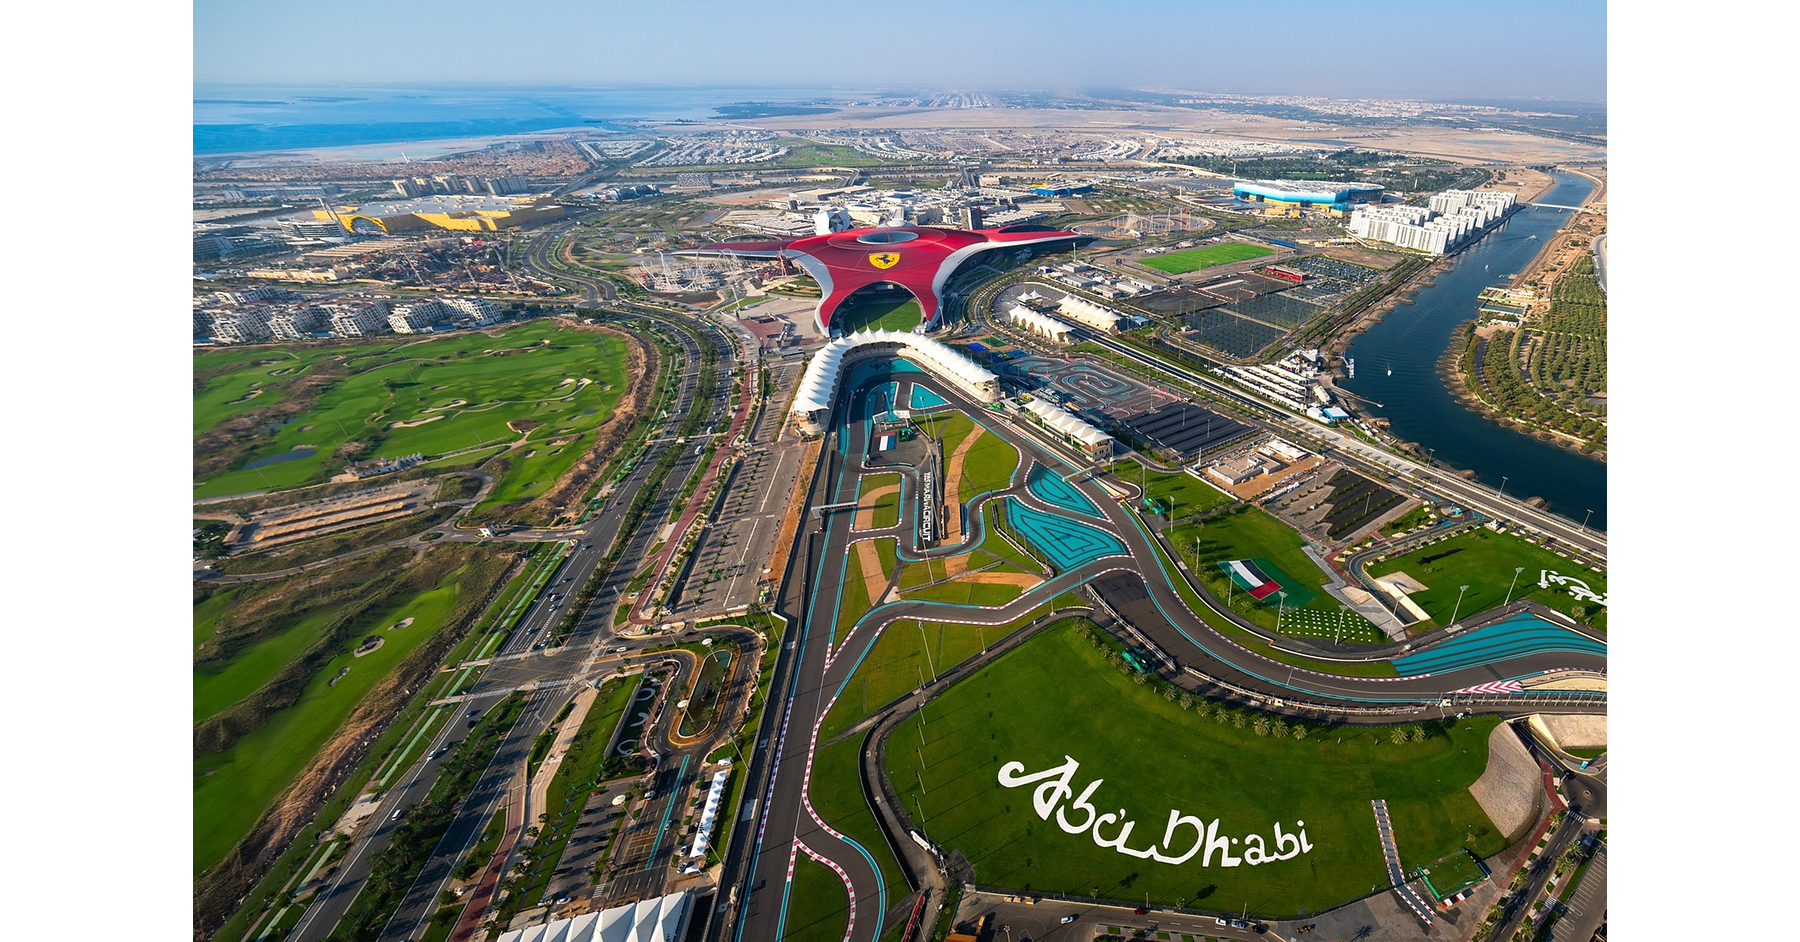
Miral will invest more than AED 12 billion in Yas Island over the next five years, separately from its previously announced Disney project. The program will expand theme-park attractions and immersive experiences, add hotel capacity, and support tourism-sector job creation and skills development. The investment advances Abu Dhabi's Tourism Strategy 2030 and its broader economic diversification agenda, strengthening Yas Island's leisure and entertainment offering.
Analysis
The investable read-through for DIS is modest near term: a destination expansion can deepen franchise visibility and licensing economics, but the disclosed spend is not DIS capital and its construction timetable is unlikely to affect consolidated earnings within the next 12-24 months. The more material implication is strategic: a Gulf destination partner reduces DIS's capital intensity while extending IP monetization into a high-income, aviation-connected catchment area. This model is incrementally favorable versus fully owned park development because royalty/management economics carry little balance-sheet risk, though the eventual revenue share remains undisclosed.
Second-order beneficiaries are likely global ride-system, themed-attraction and hospitality procurement vendors rather than listed U.S. media peers. For DIS, the key competitive issue is whether international park/licensing growth offsets a maturing domestic parks profit pool; it does not solve near-term pressure from U.S. consumer affordability, attendance mix, or streaming execution. A larger regional attractions cluster may also divert some affluent GCC leisure spending from European destinations, a marginal headwind to travel operators with disproportionate Dubai/European exposure, but the evidence is presently too weak for a directional trade.
Consensus may over-credit this as an immediate DIS catalyst. A press-release commitment without project-level phasing, IP economics, attendance assumptions, or procurement awards is principally an option-value signal. The thesis turns constructive only if DIS discloses minimum guarantees, recurring royalty rates, or management-fee arrangements that make the incremental earnings stream measurable; absent that, this should not change FY27 estimates or valuation.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No standalone DIS trade on this announcement. Maintain existing exposure only; reassess after contract disclosures or DIS earnings commentary identifies royalty, licensing, or management-fee economics. A quantified recurring revenue stream sufficient to move Parks/Experiences growth expectations would be the catalyst.
- Set a 1-3 month event alert for project procurement awards and named operating partners. If a listed attractions supplier or hotel operator is awarded a material contract, evaluate a long only after backlog value, margin structure, bonding requirements, and working-capital burden are disclosed.
- For a 6-18 month DIS thesis, prefer long DIS versus a broad media proxy only if international Experiences/licensing visibility improves while domestic Parks guidance remains intact. Falsification: a Parks/Experiences guidance cut driven by attendance or per-capita spending would dominate any future Gulf licensing benefit.
More News
- In pro sports, even the superrich are being priced out of owning a team
- Budget 2026 speech
- Wendy's shares jump 15% as Nelson Peltz's Trian offers $1.4 billion to buy burger chain
- The UK cuts energy bills, taxes banks and boosts defense in high-stakes budget
- Federal Reserve issues FOMC statement
- RBC Capital cuts Sprouts Farmers Market stock rating on margin concerns