
Alice L. Walton Foundation and Mercy Break Ground on AWSOM Whole Health Campus, Marking a New Era for Whole-Person Health in the Heartland
Source: PR Newswire
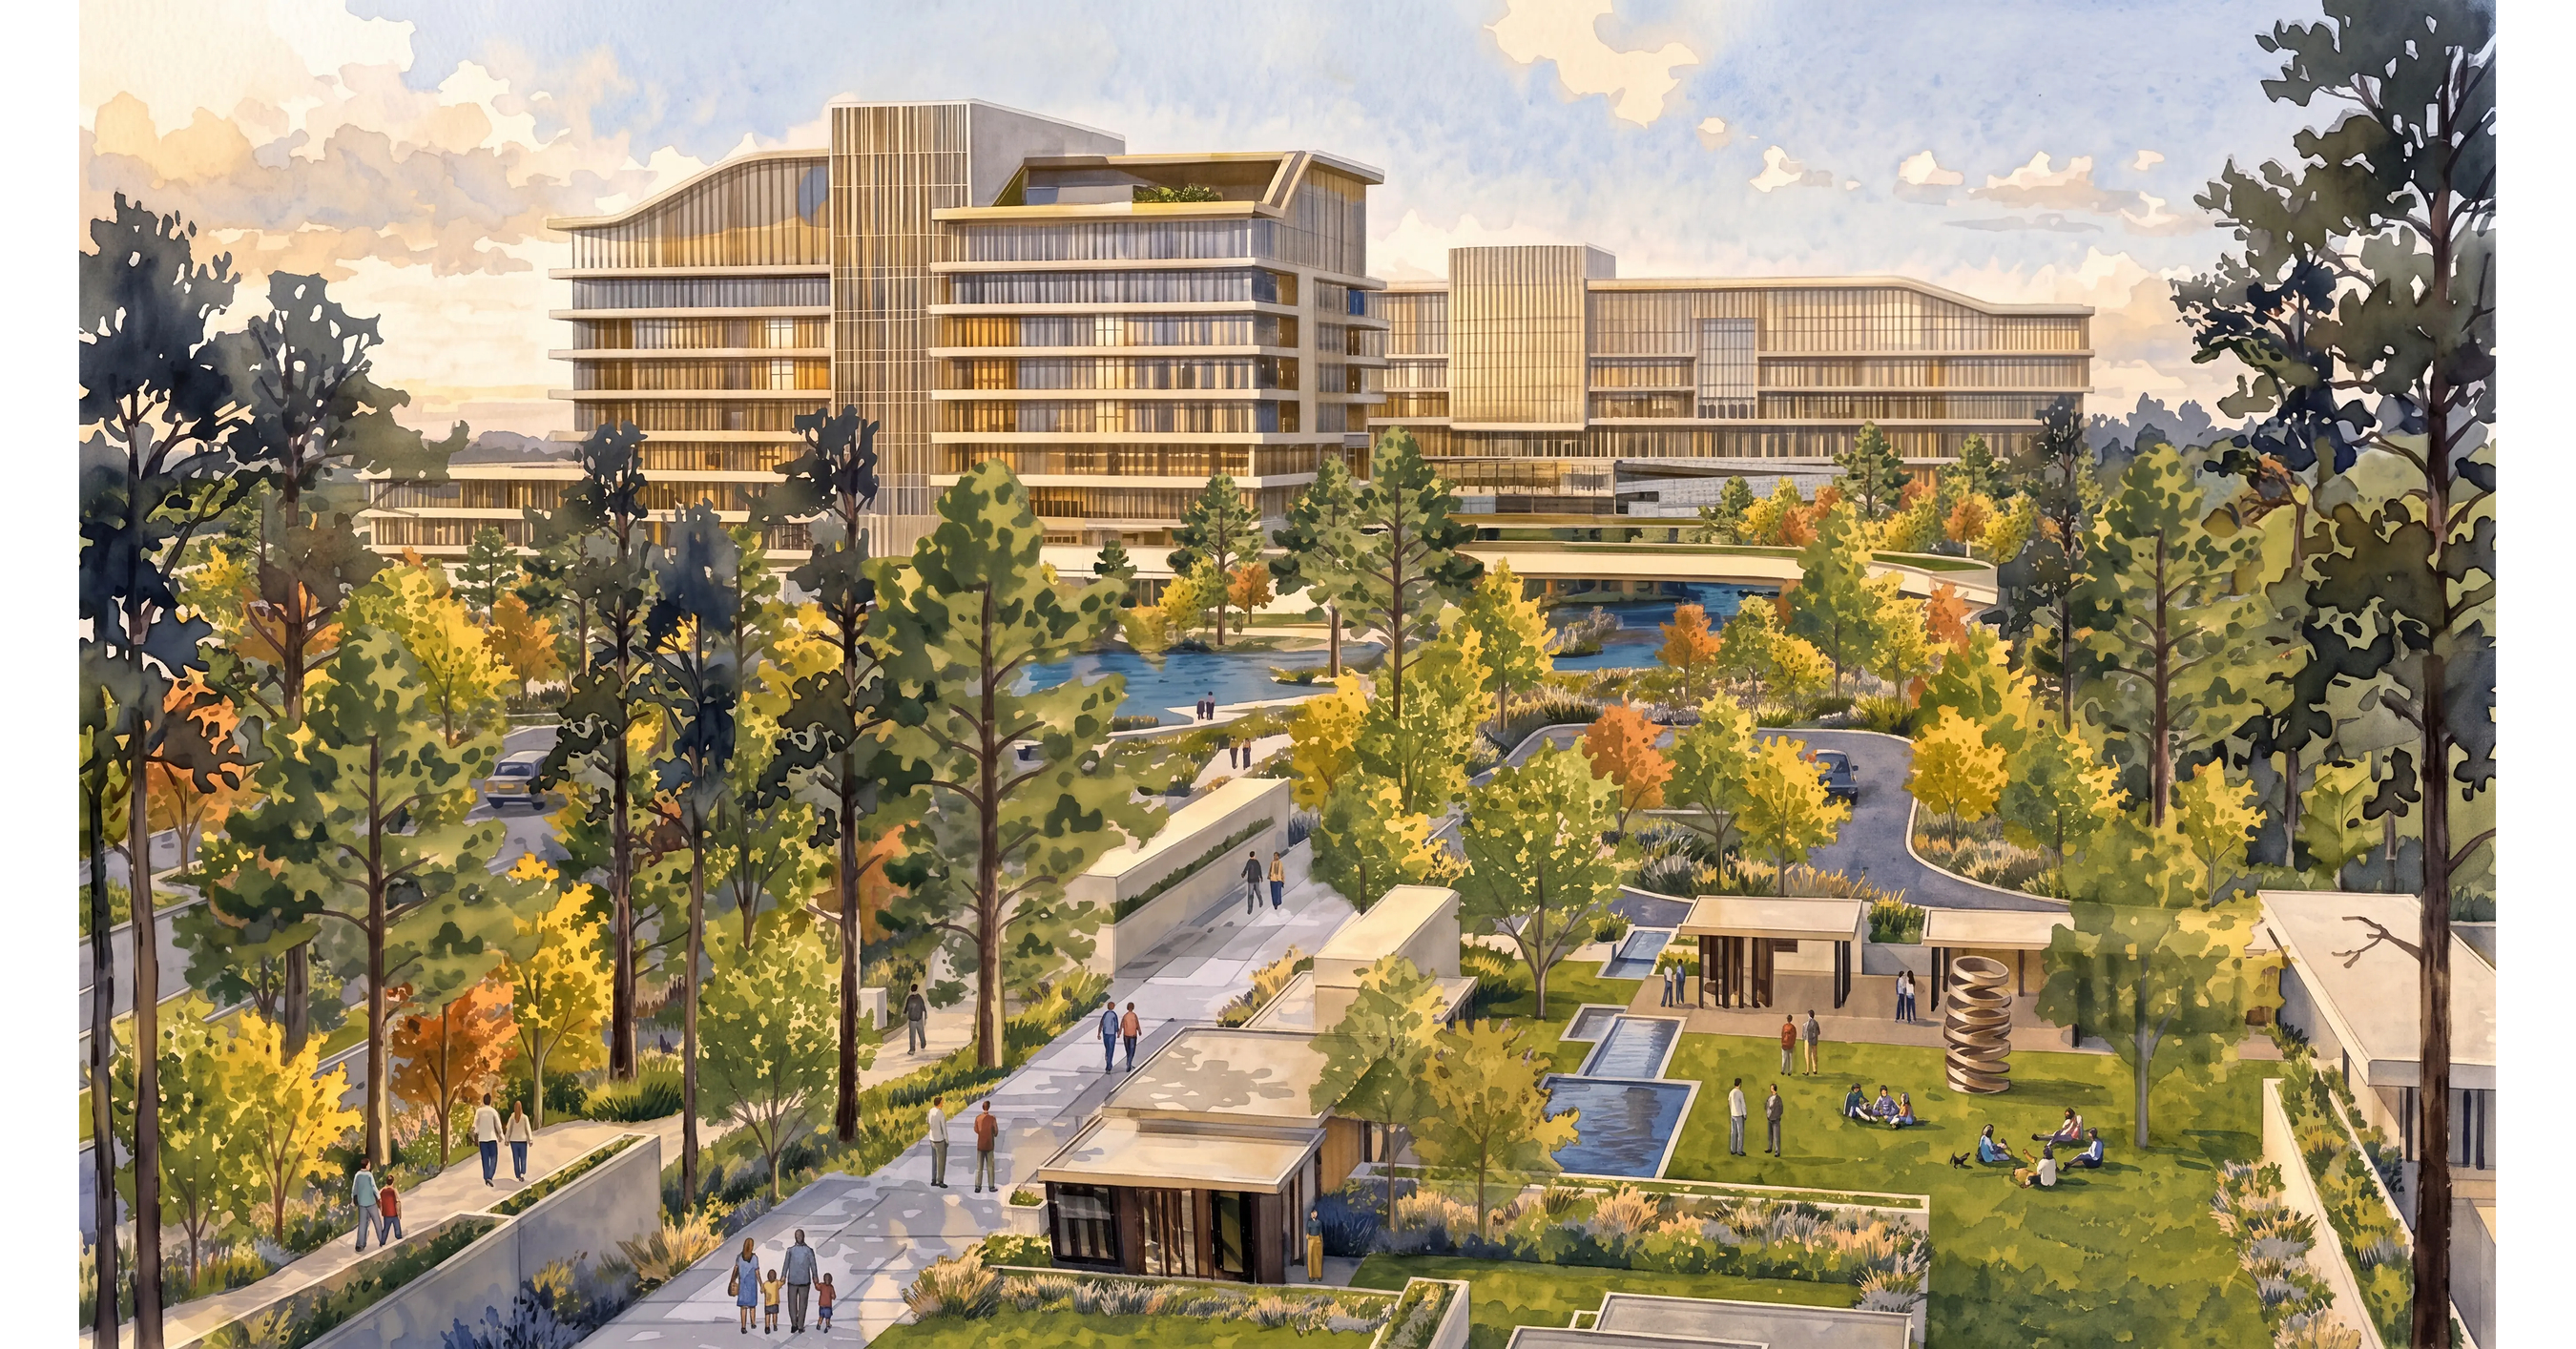
The Alice L. Walton Foundation and Mercy broke ground on the 120+-acre AWSOM Whole Health Campus in Bentonville, Arkansas, beginning a nearly 3 million-square-foot specialty-care development. Its first 709,000-square-foot cardiac-focused Center for Advanced Specialty Care, affiliated with Cleveland Clinic, is planned to open in 2029; subsequent plans include a 1.1 million-square-foot cancer center and a 1 million-square-foot hospital with more than 250 beds and 40 operating rooms. Tyson Family Foundation and Tyson Foods pledged a combined $50 million to support the project, which aims to expand specialty and virtual care access across the Heartland.
Analysis
The only directly listed exposure, TSN, has no meaningful earnings sensitivity: the contribution is immaterial against its operating cash flow and does not alter protein-cycle, pricing, or leverage assumptions. The more relevant second-order benefit is regional labor-force retention and employer healthcare access, but this accrues gradually and is unlikely to move TSN's multiple absent evidence of lower medical-cost trend or improved Northwest Arkansas recruiting. Treat any near-term TSN strength attributed to this announcement as non-fundamental.
The project creates a multi-year private construction and healthcare-capacity pipeline, but the public-market read-through is weak because the principal operators, builder, architect, and funder are not listed. NRC has no identifiable contractual economics from its reference in the release; investors should not infer revenue exposure without confirmation of a patient-experience measurement engagement. The principal risk to the development thesis is not demand but execution: specialty staffing, reimbursement rates, and capital-cost inflation could defer returns well beyond the construction schedule; a large regional capacity addition could also pressure incumbent providers' elective-procedure economics once operational.
Consensus may overvalue the branding value of a high-profile clinical affiliation while underweighting the difficulty of recruiting specialists to a new regional hub. The commercially material signals over the next 12-24 months are disclosed capital commitments, physician hiring velocity, payer contracts, and whether the operator can secure sufficient referral capture from surrounding rural systems. Until those data emerge, this is a regional private-market development story rather than a tradable public-equity catalyst.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.62
Ticker Sentiment
Key Decisions for Investors
- No directional TSN trade on this development; maintain existing thesis based on chicken margins, beef exposure, and leverage. Reassess only if management quantifies a recurring employer-health-cost benefit or incremental regional operating commitment; absent that, any donation-driven move is a fade candidate.
- Do not initiate NRC exposure from this news. Set an alert for a disclosed Mercy or campus contract, renewal, or quantified recurring revenue contribution; without that evidence, the apparent linkage is reputational rather than economic.
- Monitor publicly traded hospital operators with material Arkansas/Missouri/Oklahoma referral exposure for 2028-29 capacity and recruitment disclosures, rather than positioning now. A credible short or relative-value trade requires local service-line volume data, payer-rate visibility, and evidence that new specialty capacity is funded and staffed.
- For construction/infrastructure books, treat this as a watch item for private contractors rather than a catalyst for broad infrastructure ETFs: the multi-year spend is too geographically concentrated and the funding profile remains undisclosed. Escalate only if announced project financing or subcontract awards identify listed suppliers.
More News
- Italy to deploy warships to protect shipping through Bab al-Mandeb
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- After being sidelined, Boeing's Starliner to get starring role in NASA's spaceflight plans
- Generac shares surge on big Amazon deal. Wall Street thinks the generator stock has more to go
- Crusoe raises $3.9B to build massive data centers and small modular “AI factories”
- Warsh spooks investors, OpenAI's 'concerning' incidents, Boeing's production problems and more in Morning Squawk