
How Bankrupt Wine Distributor RNDC Preserved 6,000 Jobs
Source: Bloomberg
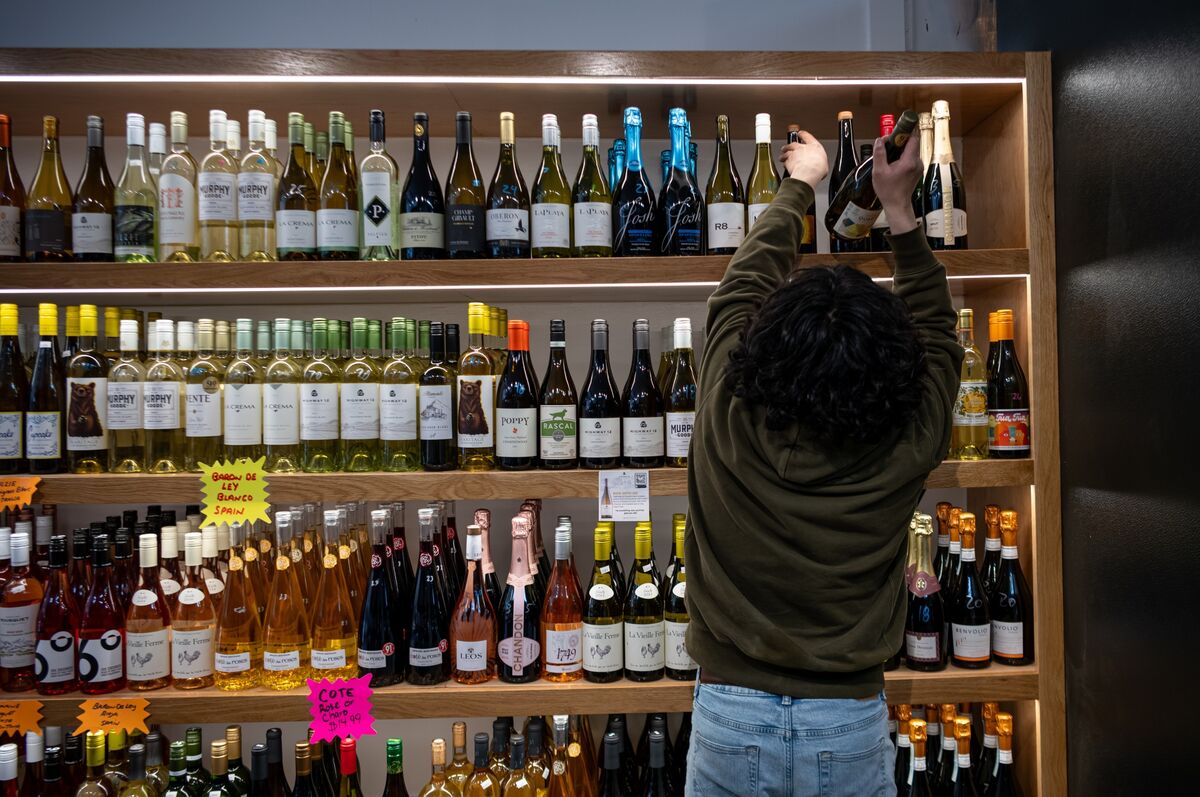
The second-largest U.S. wine and spirits distributor, RNDC, is nearing the end of its more than 125-year existence after a Chapter 11 process that preserved 6,000 jobs. Its creditors received a near-full recovery, according to the lawyer who advised the company.
Analysis
The important read-through is about recoverability, not proof that alcohol distribution is a healthy business. A near-full creditor recovery alongside jobs being preserved is consistent with valuable transferable assets or operating capabilities—but the article does not specify the transaction structure, who employs the workers, or how much value came from asset sales versus continued operations. Do not extrapolate this outcome to other distressed distributors without those details.
For competitors such as Southern Glazer’s Wine & Spirits, an orderly exit could create an opportunity to absorb supplier relationships, accounts, or talent. But the benefit is conditional: in alcohol distribution, state-level licensing and route-to-market arrangements can constrain how quickly capacity or customers transfer. Suppliers including Constellation Brands, Brown-Forman, and Diageo could face short-term service or bargaining disruption if coverage changes; any durable impact depends on successor agreements and the resulting concentration of distribution power.
Near term, this is unlikely to be a broad public-equity catalyst. Over 1–3 months, the key evidence is the identity and scope of any successor arrangements, customer retention, and creditor distributions. Over 6–18 months, watch whether consolidation improves distributor scale or instead raises supplier dependence and reduces negotiating leverage. The contrarian point: strong creditor recovery is a resolution outcome, not evidence that bankruptcy risk across the sector has fallen. The article provides no public-company exposure or deal terms sufficient to establish a directional trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.35
Key Decisions for Investors
- No immediate trade: the distributor is not publicly traded, and the article does not identify a listed buyer or quantify exposure for public suppliers.
- Set an alert for successor, asset-sale, and state-license disclosures. A named acquirer with material customer transfers would make a competitor read-through more actionable; absent that, treat potential share gains as speculative.
- Monitor public beverage suppliers’ commentary on distributor coverage, shipment continuity, and channel inventory over the next 1–3 months. Evidence of lost placements or delayed shipments would be a negative signal; stable service would weaken the disruption thesis.
- Falsify the consolidation-benefit thesis if customer or supplier relationships fail to transfer, or if state licensing blocks a rapid handoff. Conversely, broad, durable transfers to a named competitor would strengthen the case for a relative-beneficiary view, but the article alone does not support a position.
More News
- Binance CFO exits days after catastrophic $6 billion crypto hack
- Decisive election. Dramatic stock swings. How we handled the market last week
- Berkshire Hathaway more than doubles buybacks in third quarter as earnings decline
- Berkshire shares surge as Wall Street swoons amid AI fears
- Paraguay’s ousted president charged over banking scandal
- CoreWeave seeks truce with Texas Governor-elect Hinojosa