
VINFAST EXPANDS DEALERSHIP NETWORK, REINFORCING LONG-TERM COMMITMENT TO THE U.S. MARKET
Source: PR Newswire
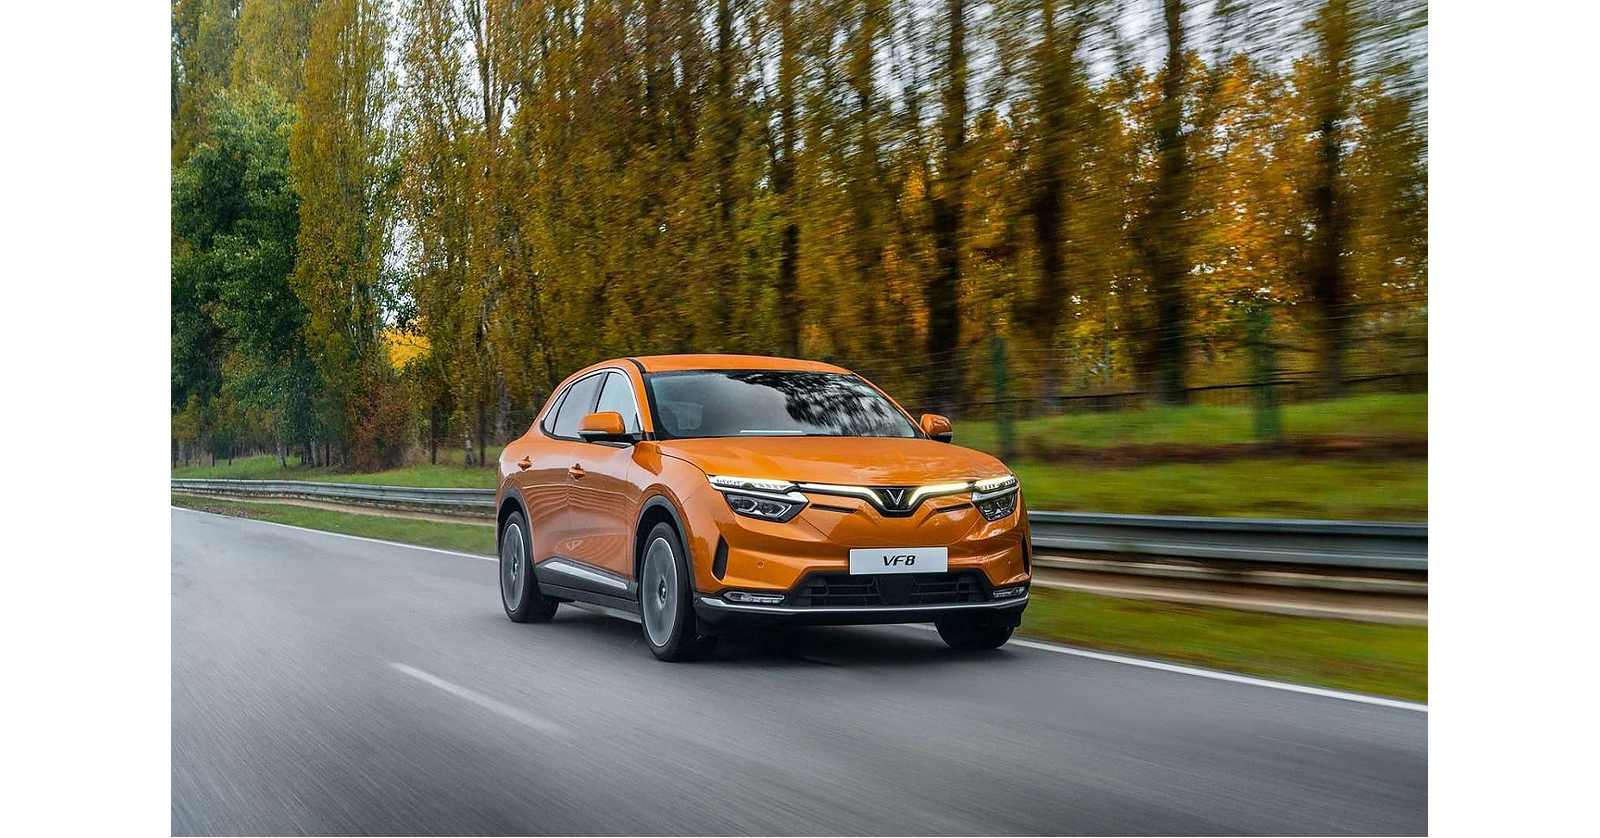
VinFast finalized franchise agreements for three U.S. sales-and-service dealerships in Redondo Beach and Tustin, California, and Philadelphia, Pennsylvania, with operations scheduled to begin in September. The locations will support sales, maintenance, warranty, and aftersales service for the VF 8 and VF 9 electric SUVs, while VinFast continues to seek additional U.S. partners. The company is also expanding its certified pre-owned EV program, with factory warranty coverage of up to 10 years, reinforcing its longer-term North American distribution strategy.
Analysis
The relevant question is not footprint count but dealer economics: a franchised model shifts working-capital, facility, and local service-capacity obligations away from VFS, yet meaningful U.S. demand still requires dealers to accept inventory risk and sustain satisfactory per-unit gross profit. Three locations are too small to alter fixed-cost absorption or volume forecasts; the near-term read-through is limited to whether the company can recruit additional independent operators without escalating floorplan support, incentives, or buyback commitments. Watch subsequent filings for dealer receivables, inventory growth, warranty reserves, and selling expense per delivered vehicle rather than treating network announcements as proof of retail traction.
A more capable service and CPO channel can modestly improve residual values and reduce purchase friction, but it also creates a mark-to-market test of prior vehicle pricing. If used VF 8/VF 9 values clear materially below new-vehicle transaction prices after subsidies, the company may face higher lease residual risk, trade-in losses, and pressure to discount new inventory; that would impair gross margin before any volume benefit. This is a 6-18 month operational issue, not a September earnings catalyst.
VFS's thin public float/history of sharp retail-driven moves makes the immediate response potentially disconnected from the underlying financial materiality. Consensus may over-credit a dealer rollout for solving product-market fit and brand awareness; incumbent dealer groups already have service density, financing relationships, and used-vehicle liquidity. The stronger falsifier would be evidence of sequential U.S. deliveries rising while automotive gross margin excluding one-offs improves and cash burn does not accelerate over the next two reporting periods.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.32
Ticker Sentiment
Key Decisions for Investors
- No directional VFS position on this announcement alone; treat any sharp rally as liquidity-driven unless the next two quarterly reports show expanding U.S. deliveries, stable incentive intensity, and improving operating cash burn.
- For a high-risk tactical expression, consider selling out-of-the-money VFS call spreads only after an announcement-driven spike and only where borrow/options liquidity permits; use a defined-risk structure because concentrated ownership and low float can produce discontinuous squeezes. Reassess within 1-3 months as dealer additions and delivery data emerge.
- Monitor franchised-dealer disclosures for inventory guarantees, floorplan subsidies, warranty reserve growth, and CPO residual outcomes. A material increase in these support costs would support a bearish view; absence of disclosure is not confirmation of favorable economics.
- Prefer established U.S. EV/auto distribution exposures over VFS for a service-network recovery thesis: watch GM and F as less binary beneficiaries if EV service utilization and used-EV financing normalize, while avoiding a direct pair until comparable delivery and margin data are available.
More News
- Italy to deploy warships to protect shipping through Bab al-Mandeb
- Oil prices fall for 3rd day as supply concerns ease, diplomacy in focus
- Pokémon card curbs send shares of Japanese online marketplace Mercari on a bumpy ride
- Saudi Pivots Oil Routes After Pipeline Attack
- US to Sell F-35s to Saudi Arabia in $24.3 Billion Deal
- How record diesel prices will rip through the U.S. economy. Trucks and rails are only the start
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- How to Evaluate Consensus Estimates Platforms With AI
- Weekly Update: Adding Live MBO Level 3 Data - Liquidity Heatmap, OFI Charts, and More