
RenX Enterprises Sets Microtec Turbo Mill in Place at Myakka City; Engineered Substrate Commissioning Remains on Track for Fourth Quarter of 2026
Source: Newswire
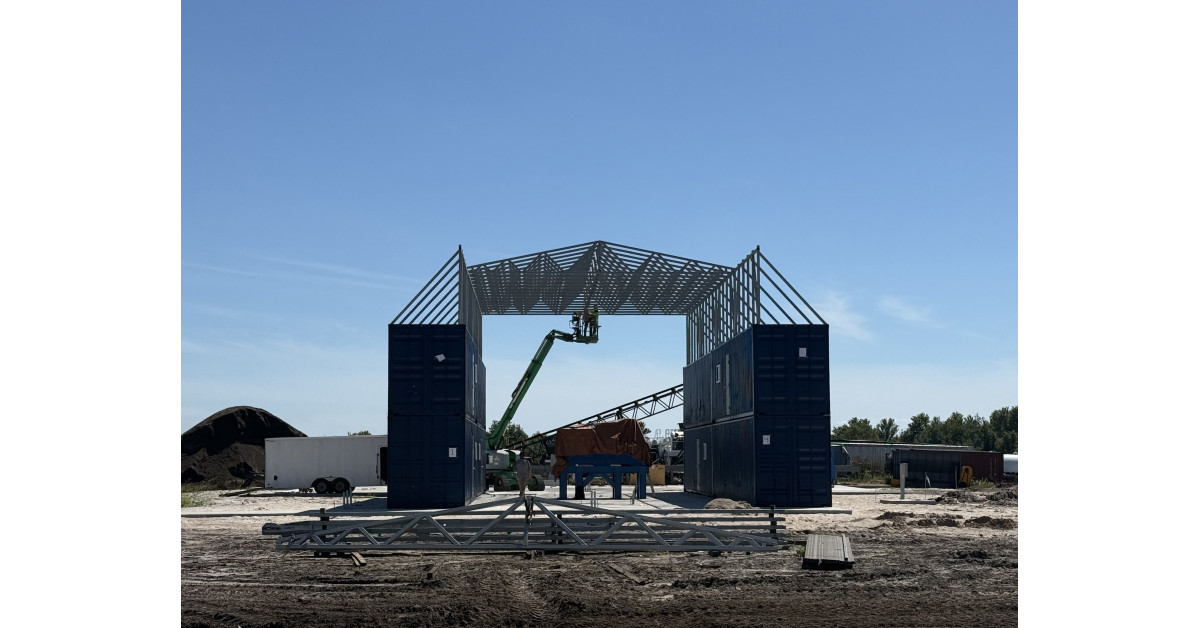
RenX completed the fourth of seven installation milestones for its Microtec UTM 1200 Turbo Mill at Myakka City, Florida, with commissioning still targeted for Q4 2026. The remaining work includes material-handling integration, utility interconnection and energization; the mill is intended to convert lower-value woody biomass into higher-margin engineered substrate. RenX reported $15.0 million in trailing-12-month revenue through June 30, 2026, including a record $4.26 million in Q2 revenue, but commercial sales from the new substrate line remain contingent on successful commissioning and customer qualification.
Analysis
The investable issue is not mechanical installation but conversion of a low-value residual stream into a qualified, repeat-purchase product. RENX’s valuation will remain driven by liquidity and execution credibility until it discloses three measurable items: installed throughput, realized selling price/ton, and signed customer volumes. Without contracted offtake, the claimed gross-margin step-up is an untested manufacturing assumption rather than an earnings catalyst; initial qualification cycles with commercial growers could extend beyond commissioning by one or two planting seasons.
Near-term upside in the next 1-3 months is likely event-driven and potentially illiquid: completion of electrical interconnection and energization can support incremental retail interest, but neither establishes revenue. The critical gating risk is utility timing and integrated-system performance—material handling, dust control, controls, and feedstock consistency are where greenfield processing projects commonly lose uptime and margin. Any funding need before stable substrate sales would dilute the value of the operating milestone, particularly given the company’s stated refinancing/going-concern risks and reliance on legacy-asset monetization.
The more differentiated 6-18 month opportunity is regional substitution for imported peat/bark, but local freight savings accrue only if product quality is consistent enough to offset customer switching costs and agronomic risk. Large incumbents in growing media and horticultural inputs—Scotts Miracle-Gro (SMG), Sun Gro/Westlake-related channels, and regional mulch/soil suppliers—have established distribution and customer relationships; RENX may need introductory pricing, which could delay the initially implied margin expansion. Consensus may overvalue a sequence of construction updates: first commercial reorder rates, not first production, are the relevant proof point.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.38
Ticker Sentiment
Key Decisions for Investors
- No core long recommendation before commissioning. Treat RENX as a catalyst watchlist through Q4 2026; consider only a small, liquidity-adjusted tactical position after energization if cash runway extends at least 12 months without an equity raise.
- Require a disclosed throughput run-rate, gross margin per ton, and binding offtake/customer purchase orders before underwriting 2027 EBITDA. Absence of these disclosures within 60-90 days of commissioning is a negative signal regardless of successful startup.
- If RENX rallies materially on installation updates before commercial sales, use the strength to avoid/add no exposure rather than chase; the likely asymmetry remains downside from delay, dilution, or underutilization versus upside already implied by promotional milestone reporting.
- Set thesis-falsification alerts for: commissioning slipping beyond Q4 2026; a financing or debt-extension filing; Nasdaq compliance notices; or first-production data showing low utilization, discounting, or no repeat orders. Any one warrants reassessing the substrate-margin thesis.
- NDAQ has no direct operating sensitivity to RENX’s project economics; do not infer a read-through trade from the listing venue.
More News
- Meta stock enjoys best month since 2022 on AI momentum
- New report finds that rapid expansion of tokenization is giving rise to new styles of investing
- Why is Moderna stock down 4% today?
- Robinhood stock rises as analysts applaud AI agents, trading tools
- Why is Robinhood Markets stock rallying today?
- Freedom Capital reiterates CoreWeave stock Buy rating at $151 target