
Curve Dental Introduces Curve Memberships, Helping Practices Strengthen Patient Retention & Profitability Through Membership-Driven Care
Source: PR Newswire
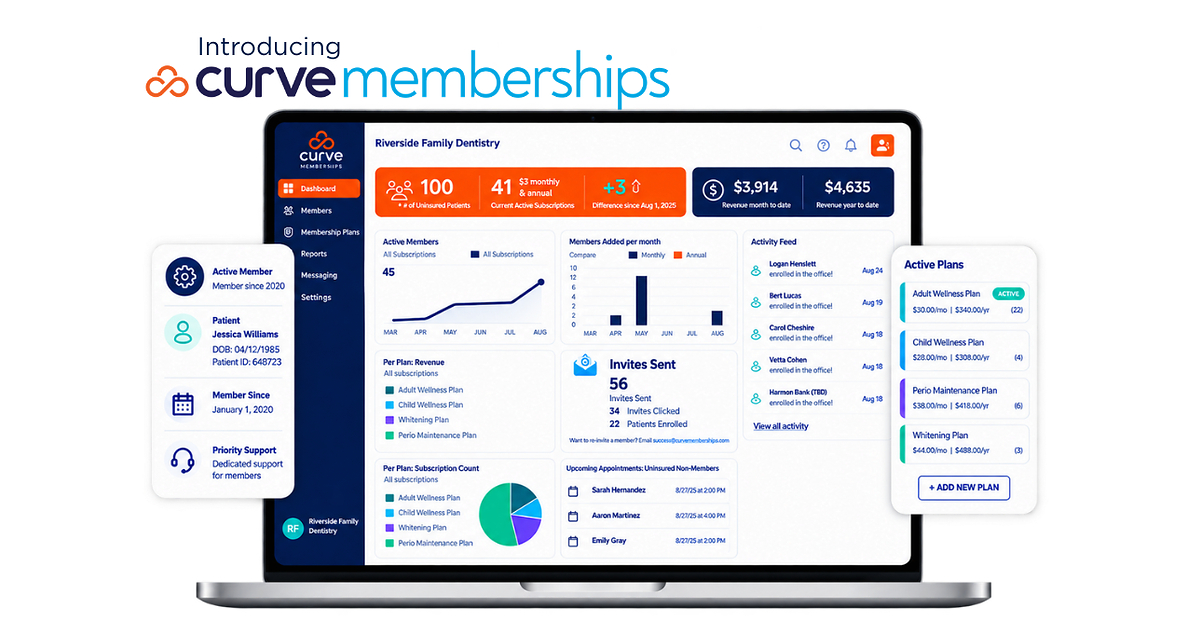
Curve Dental launched “Curve Memberships,” an AI-enabled, cloud-integrated membership enrollment and billing feature that auto-delivers personalized invitations and auto-posts recurring membership payments in Curve. The pitch targets the 1 in 5 working-age U.S. adults without dental benefits, aiming to make enrollment simpler and grow more predictable recurring revenue without adding front-desk workload. Curve also reaffirmed its $200 million R&D commitment and said the rollout begins to eligible Curve customers this month.
Analysis
This reads more like a retention/ARPU packaging update than a meaningful new revenue stream. The near-term market impact is likely negligible, but the strategic signal is that vertical software vendors are trying to own more of the payment and collections layer, which is where the durable economics sit. If this works, the benefit accrues first to the platform operator through higher net revenue retention and lower churn, not to the end customer.
The second-order risk is cannibalization: membership plans can smooth cash flow while also shifting mix toward lower-acuity, price-sensitive visits. That can improve collection timing without improving per-visit economics, so the important question is whether utilization rises faster than discounting. The real catalyst path is 1-3 quarters of cohort data showing attach rate, retention, and gross margin per member; without that, this is just feature parity.
Contrarianly, the market may overestimate the moat from "AI + automation" language. The defensible part is workflow integration and billing connectivity, which can raise switching costs, but the feature itself is easy to copy. Public dental proxies like HSIC and PDCO only become relevant if integrated membership and payments start displacing incumbent software/payment attach; absent that, this is mostly a private-company product announcement, not a listed-equity trade.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.18
Key Decisions for Investors
- No immediate position in TDAY or TISI on this release; treat it as a watch item rather than a trade until there is disclosed evidence of attach-rate or NRR lift over the next 1-2 quarters.
- Watch HSIC and PDCO as the closest public read-throughs to dental software/payment workflow share; fade any sympathy rally unless their own commentary confirms channel disruption or slower software attach.
- Set a conditional short list: if future disclosures show membership-plan adoption below expectations or meaningful margin dilution from discounted recurring plans, revisit shorts in legacy dental workflow/payment names (HSIC, PDCO) on a 1-3 month horizon.
- For broader vertical-SaaS exposure, prefer to wait for proof before buying the theme; no options or pair trade is justified here unless a public peer reports measurable uplift in collections, churn, or payment take-rate.
More News
- Philip R. Lane: Interview with Le Temps
- US, China Talks Focus on Trade, AI, Investment
- Alibaba shares jump as new AI chip, data center buildout plans unveiled
- AMD joins the $1 trillion club as chip rally surges - our AI Strategy saw it early
- Taiwan benchmark Taiex rises to record intraday high as tech stocks advance
- Paramount agrees invest $1.5 billion in domestic movies and create a board for editorial independence at CNN, CBS as part of deal for Warner Bros.
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- AllMind Discusses Ontario's AI Economy with Minister Stephen Crawford and Supply Ontario CEO James Wallace
- AI Research Tools for SEDAR+, UK and ASX Filings