
ECOVACS at IFA Berlin 2026: Named as No.1 Brand in Global Home Robotics, Bringing Robotics to More of Everyday Life
Source: PR Newswire
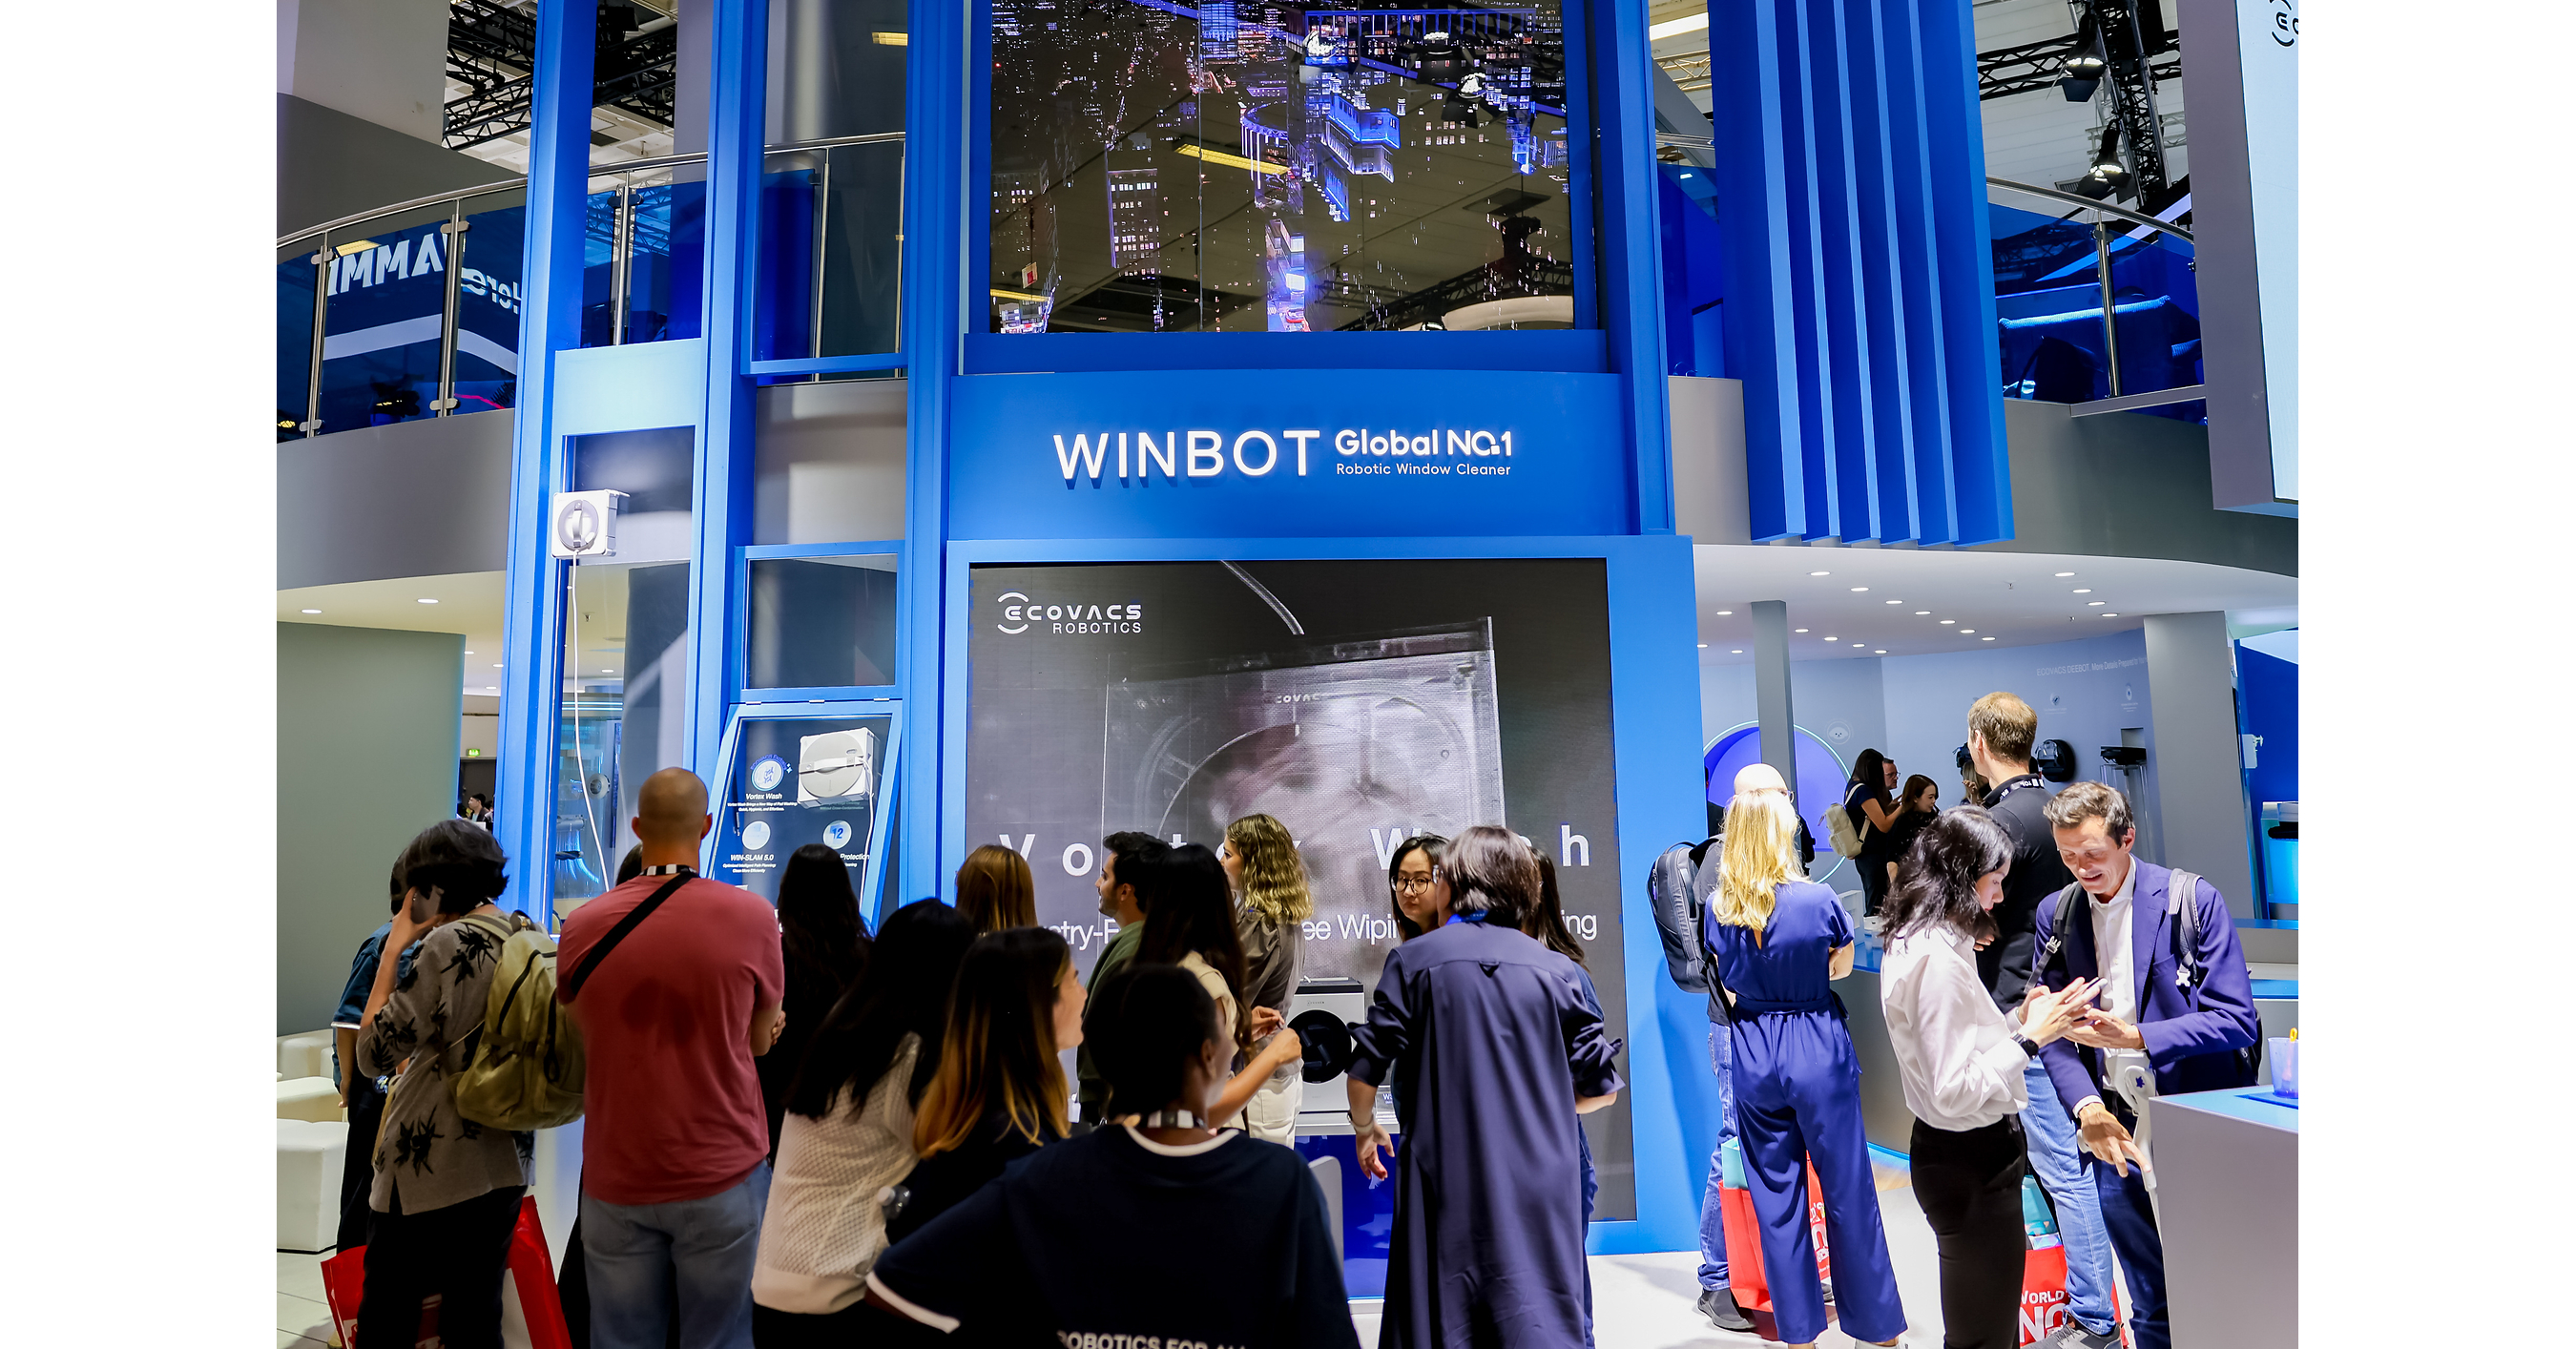
ECOVACS was named the global No.1 home robotics brand by Forbes China and reported strong momentum in 1H 2026, with service-robot shipments up 44.1% YoY and revenue from new categories (window cleaners, lawn mowers, pool cleaners) up 75.1% in international markets. International markets contributed 51% of total revenue in Q2 2026 for the first time, reflecting broader scaling beyond China. The company also highlighted RMB 554 million of R&D investment in 1H 2026 and 3,100+ patents to support multi-category expansion.
Analysis
The key market read-through is not “robotics demand is strong,” but that scale players are turning home robotics into a platform business: reuse of core sensing/motion stacks lowers marginal R&D and speeds category rollouts, which should widen the gap between vertically integrated leaders and smaller single-product brands. That is bearish for fragmented consumer-hardware names like IRBT and, to a lesser extent, premium appliance brands that rely on feature cadence rather than a true robotics stack; it also raises the odds of price competition as categories mature, which can cap gross margin even when unit growth stays healthy.
Near term, this is mostly a marketing event unless the next two quarters show mix improvement and lower promo intensity. Over 1–3 months, watch for channel sell-through in Europe/US and whether newer outdoor categories contribute meaningfully to profit versus just topline. Over 6–18 months, the real test is whether lawn/pool robotics stay niche affluent-homeowner products or become a recurring replacement cycle; if attach rates stall, working-capital intensity and support costs can offset shipment growth.
The consensus risk is over-interpreting shipment leadership as durable earnings power. A stronger second-order thesis is that robotics adoption increases the value of the home software layer: mapping, voice, device orchestration, and app ecosystems. That makes GOOGL a better indirect beneficiary than the hardware names, while the most exposed shorts are companies without manufacturing scale or software lock-in. Falsifiers: a sustained jump in IRBT-style category margins, or ECOVACS-style leaders proving they can expand categories without discounting.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
moderately positive
Sentiment Score
0.45
Key Decisions for Investors
- Pair trade: long GOOGL / short IRBT over 3-6 months. Rationale: if home robotics becomes more autonomous, the ecosystem layer accrues value, while commoditized hardware players face margin compression and pricing pressure. Risk/reward favors relative outperformance if hardware competition stays intense; cover if IRBT shows two consecutive quarters of gross-margin expansion.
- Do not chase consumer-hardware longs on the announcement alone. Wait for next earnings prints from robotics/appliance names to confirm whether shipment growth is translating into operating leverage; absent that, this is likely a sentiment event rather than a fundamental inflection.
- If needing low-cost optionality, use a modest 3-6 month GOOGL call spread instead of outright stock. Thesis is incremental upside from smart-home/AI orchestration adoption, but keep sizing small because the linkage to this news flow is indirect.
- Set an alert on IRBT into the next guidance cycle: if revenue growth does not reaccelerate while promotional intensity rises, consider a tactical short on strength. If management shows sustained ASP stability, the bear case weakens.
More News
- Indonesian stocks plunge to six-year low as MSCI downgrade fears mount
- Indonesia Said to Meet Monday With MSCI Over Shock Index Threat
- Nifty Bank Heavyweights HDFC, ICICI in Focus After Weekend Earnings
- Putin reportedly suggests summit with Trump and Xi to decide fate of Ukraine
- China's CXMT sees shares drop over 6% as investors look past chipmaker's profit turnaround
- Asian stocks skid, Wall Street and bonds aided by oil slip