
CIIF 2026 New Material Industry Show Unveils Scenario-Driven 'Six Material Islands' Layout to Accelerate Global Supply Chain Integration
Source: PR Newswire
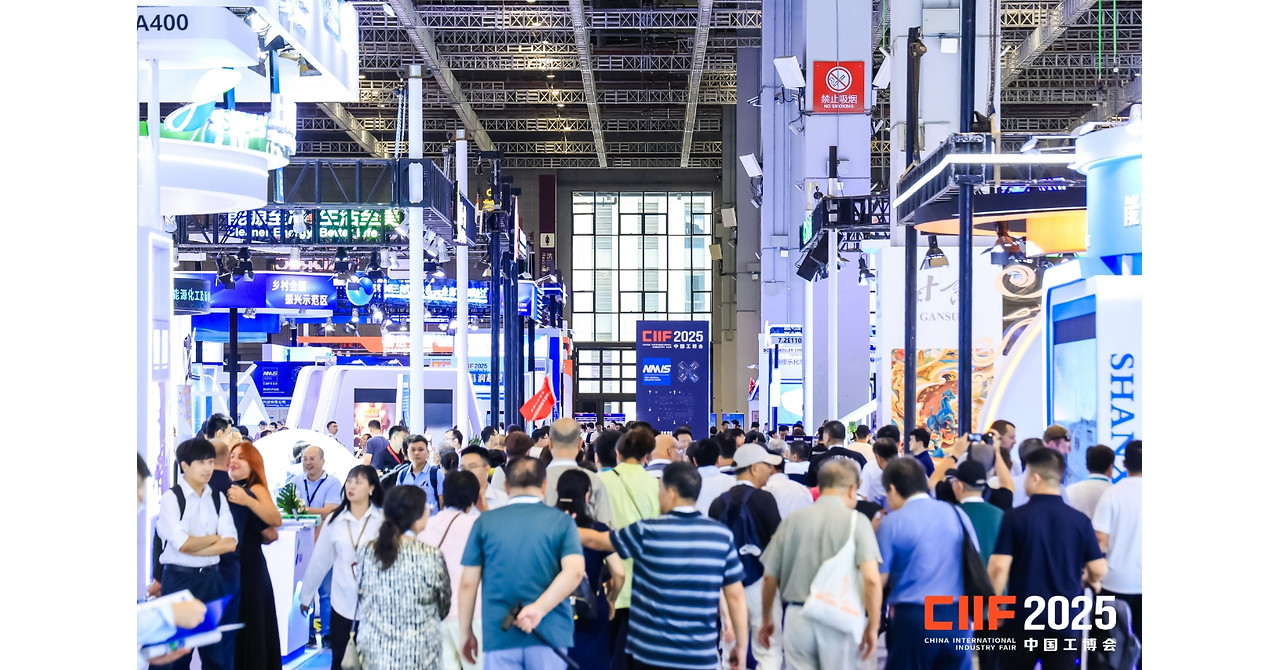
The China International Industry Fair's New Material Industry Show will be held in Shanghai on October 12-16, 2026, bringing together more than 300 global exhibitors through a new six-'Material Islands' layout intended to link materials suppliers with downstream buyers. The event will spotlight aerospace, batteries and hydrogen, AI and humanoid robotics, automotive materials, biomanufacturing, and advanced materials including superconductors and 3D-printing inputs. Nearly 40 Shanghai pilot-scale materials builders and more than 10 industry forums will support supply-chain matchmaking and discussion of China's 15th Five-Year advanced-materials roadmap.
Analysis
This is not a standalone earnings or demand catalyst; it is a policy-adjacent industry-marketing signal whose investable value lies in identifying where Chinese procurement and pilot-scale capacity may consolidate ahead of the next five-year planning cycle. The likely beneficiaries of any subsequent localization push are qualified incumbents with certification history rather than early-stage materials vendors: CRRC (601766.SS) and Kingfa (600143.SS) in engineered materials applications, Dongfang Tantalum (000962.SZ) in strategic metals, and Sinopec Shanghai Petrochemical (600688.SS) where domestic specialty-material qualification converts into higher-value product mix. The second-order constraint is not laboratory innovation but scale-up yield, customer qualification, and export-control access to specialized equipment and inputs.
Near term, the event itself should not move liquid equities materially; press-release claims offer no basis for forecasting orders, pricing, or capex. Over the next 1-3 months, actionable evidence would be provincial pilot-base subsidies, named OEM supply agreements, or domestic-content requirements tied to aerospace, grid storage, and robotics procurement. Over 6-18 months, a more explicit advanced-materials roadmap could compress the valuation discount on China-listed specialty-material suppliers, but it could also create oversupply in battery, PV, and carbon-fiber value chains if capacity incentives outrun end demand.
The contrarian view is that investors may over-extrapolate broad "AI materials" and solid-state-battery visibility into revenue inflections. These categories remain gated by reliability qualification and customer adoption, so equipment and established processors may monetize earlier than material developers. A credible thesis requires evidence of utilization, gross-margin expansion, and repeat commercial orders—not product demonstrations or pilot announcements.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No directional trade on the exhibition alone; treat it as a research-screening event rather than a catalyst. Revisit China specialty-materials exposure only after named customer awards or government procurement language is released within 1-3 months.
- Create a watchlist of 000962.SZ, 600143.SS, 601766.SS, and 600688.SS; require two confirmations before entry: order/backlog disclosure and evidence that specialty-product gross margins or utilization are improving. Falsify on flat guidance, rising receivables, or new capacity announcements without contracted demand.
- For a policy-confirmation trade over 6-12 months, prefer a quality pair: long Kingfa (600143.SS) versus a broad China battery-materials basket, conditional on engineered-plastics volume and margin acceleration. The thesis is that qualified application materials are less exposed to commodity-style oversupply than cathode/anode supply; exit if Kingfa's automotive/industrial mix weakens or battery-material pricing stabilizes materially.
- Monitor solid-state battery and aerospace-material announcements for equipment orders rather than prototype claims. A disclosed commercial production line, OEM qualification, or sustained pilot utilization would be a buy-trigger for the relevant supplier; absent those data, avoid speculative exposure to pre-revenue solid-state battery names.
More News
- AI’s Grip on Financial Markets Was Never Clearer on the Way Down
- Tech stock rout, driven by US AI fears, continues in Asian trading
- Asian Markets Tally Losses From Worsening Global Rout
- Magnificent 7 loses $1 trillion. The most eye-popping stats from Thursday's tech stock plunge
- Wall Street’s best post-midterm rally in 44 years lasted just one day—then $3 trillion vanished as chip stocks plunged over AI fears
- How Wall Street's postelection rally got obliterated — and what's next