
HNS 2026 | Huawei совместно с отраслевыми организациями представила в Европе технический документ по стандартам и технологиям высококачественных интеллектуальных кампусных сетей со скоростью 10 Гбит/с
Source: PR Newswire
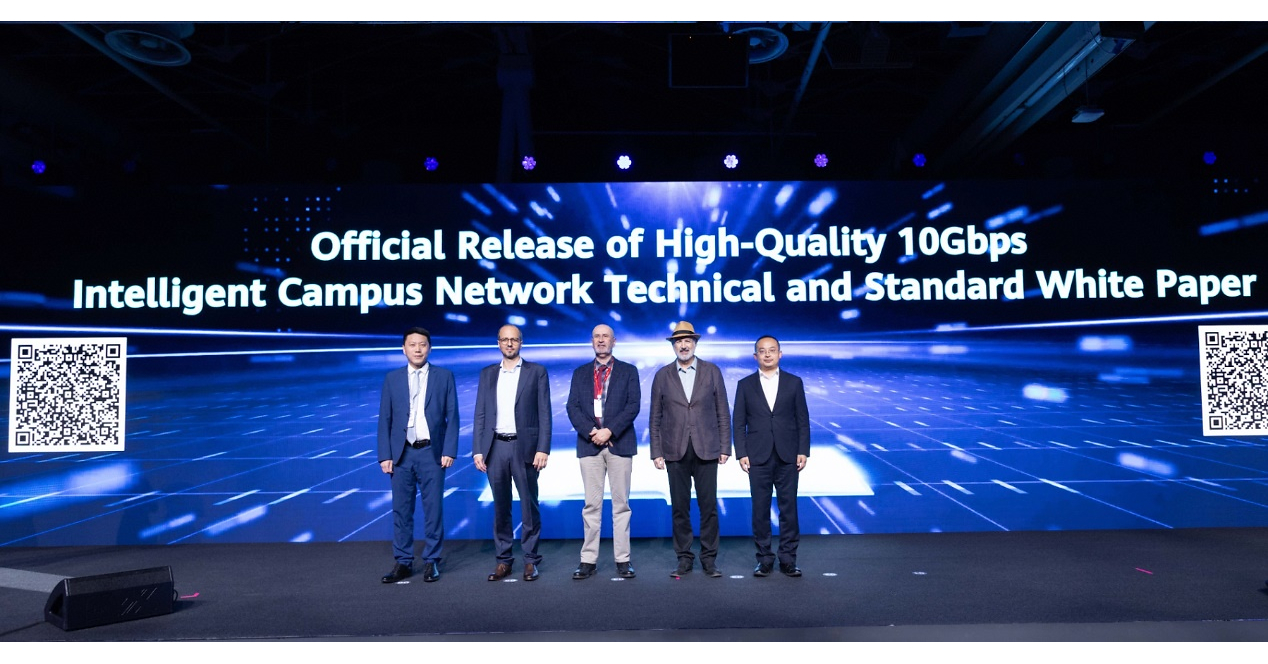
At HNS 2026 in Florence, Huawei and industry organizations introduced a white paper on standards and technologies for 10 Gbps intelligent campus networks, alongside an updated Stellar Intelligent Campus Network solution. Huawei says its Wi-Fi 7 Advanced technology can double network performance and its NetMaster system can reduce mean time to repair by 90%; the solution also emphasizes security, autonomous management and energy efficiency. The announcement is a product and standards update, with no financial results or customer deployments disclosed.
Analysis
This is a standards-and-positioning signal, not evidence of near-term order acceleration. Huawei is trying to make its campus-network architecture a reference point; if the paper is adopted in procurement specifications, the payoff would be gradual: greater influence over refresh cycles and ecosystem choices, with potential pressure on Cisco, HPE/Aruba, Nokia and other campus-network vendors to match the feature set or defend differentiation. The key swing factor is whether European public-sector, healthcare and industrial buyers will treat Huawei as an eligible supplier. Security scrutiny, procurement restrictions and existing vendor relationships could limit addressable demand even if the technical proposition resonates.
The commercial claims are unverified company assertions. In particular, reported Wi-Fi performance gains and MTTR reduction do not establish customer-level ROI, willingness to pay or deployments. Quantum-resistant encryption language also needs validation against deployed products, standards and independent security assessment. The structural opportunity is real—more connected devices and bandwidth-intensive campus applications can support network refreshes—but it is a multi-year replacement cycle, not a catalyst implied by a white paper launch. Near term, the release is unlikely to support a fundamental trade absent evidence of orders, partner commitments or procurement wins. The contrarian angle: market attention may overvalue headline bandwidth and undervalue integration costs, security eligibility and the slow conversion of technical standards into budgets.
AllMind Terminal
AI-powered research, real-time alerts, and portfolio analytics for institutional investors.
Request TrialMarket Sentiment
Overall Sentiment
mildly positive
Sentiment Score
0.30
Key Decisions for Investors
- No directional trade on this announcement alone. Treat the modestly positive tone as a watch item; seek independently verifiable European deployments, contract wins and partner commitments before assigning revenue impact.
- Monitor Cisco, HPE/Aruba, Nokia and other campus-network suppliers for signs of competitive response or lost bids. A credible Huawei-led specification gaining procurement traction would be a medium-term competitive risk; restrictions or buyer exclusions would instead favor eligible incumbents.
- For the next 1–3 months, verify whether the white paper is cited in tenders and whether customers validate performance, energy savings and MTTR claims. Without those signals, assume limited immediate earnings relevance.
- Falsifiers: evidence of broad European procurement exclusion for Huawei would weaken the adoption thesis; conversely, multiple named deployments plus independent ROI evidence would strengthen it. Avoid treating Huawei’s stated performance improvements as independently established facts.
More News
- Australian data center operator NextDC's shares plunge 40% after it slashes earnings forecast
- ‘I don’t care how it’s done’: Trump pressures Ukraine to cut peace deal
- Super Micro’s stock soars after surprise update — with Dell and HPE shares joining the rally
- As Macron visits Gulf, can France forge its own energy-for-security future?
- Australian AI data centre operator NextDC shares shed 44% on revenue delay
- SpaceX posts first operating profit as public company as AI revenue nearly triples to $7.6 billion—cruising past Starlink
From AllMind Research
- Anthropic IPO Preview: Valuation, Timing, and What to Watch
- Shein After the IPO: Venue, Valuation, and What Must Be Proved
- What AI Research Tools Should a Small Hedge Fund Buy First?
- What a Concept From Nature Tells Us About How C-Suite Executives Actually Think About AI
- How to Track Earnings Call Sentiment Across Companies